
CHILE · ANALYSIS
Key Facts
- What is happening South Korea’s government plans to double AI and chip spending to 21.3 trillion won (US$15.8 billion) in its 2027 budget, which feeds demand for copper from Chile and Peru.
- Why it matters Most of the copper pull comes from data centres, power and cooling rather than from the chips, and mine supply is struggling to respond.
- The numbers Cochilco, Chile’s state copper commission, forecast on 30 October 2026 that Chilean output would fall 8.4% to 4.94 million tonnes in 2026 and that the 2026 average price would be US$6.18 per pound.
- Who is who Codelco is Chile’s state miner, Cochilco is its forecasting agency, and China’s smelters turn Chilean and Peruvian concentrate into refined metal.
- What to watch Chile’s October trade data, expected around 7 November 2026, and the Imacec activity index, expected around 1 December 2026.
- What it means for you US copper buyers face prices near US$6 per pound and a 50% tariff on semi-finished copper, which raises the cost of data-centre wiring and power equipment.
AI chips drive copper demand mostly through data centres, power grids and cooling, not through the chips themselves. For US readers, that shows up in copper prices near US$6 per pound, tariffs on imported metal and the cost of building American data centres.
Chile and Peru are South American copper producers whose concentrate is shipped mainly to Asian smelters. This analysis, drawn from the Asia Intelligence Brief of 2 November 2026, explains how Seoul’s chip spending reaches their mines and what could go wrong.
From Seoul’s Budget to a Chilean Mine
South Korea’s Cabinet approved a record 2027 budget of nearly 821 trillion won (about US$599 billion), the Korea Times reported on 1 September 2026. Of that, 21.3 trillion won (US$15.8 billion at the conversion used in the Rio Times brief) goes to three megaprojects: semiconductors, physical AI and AI data centres.
The Korea Times puts the rise at 97.2% on this year’s spending. Items named include 2.6 trillion won for physical-AI demonstrations, 10,000 GPUs (graphics processors) for a national foundation model, and a special semiconductor account for capacity expansion.
The Rio Times brief ties Korean and Taiwanese chip demand to Chilean and Peruvian copper and lithium. This analysis tests the copper half of that claim, and the research found no official Chilean or Peruvian statistic that links the Asian chip boom to copper.
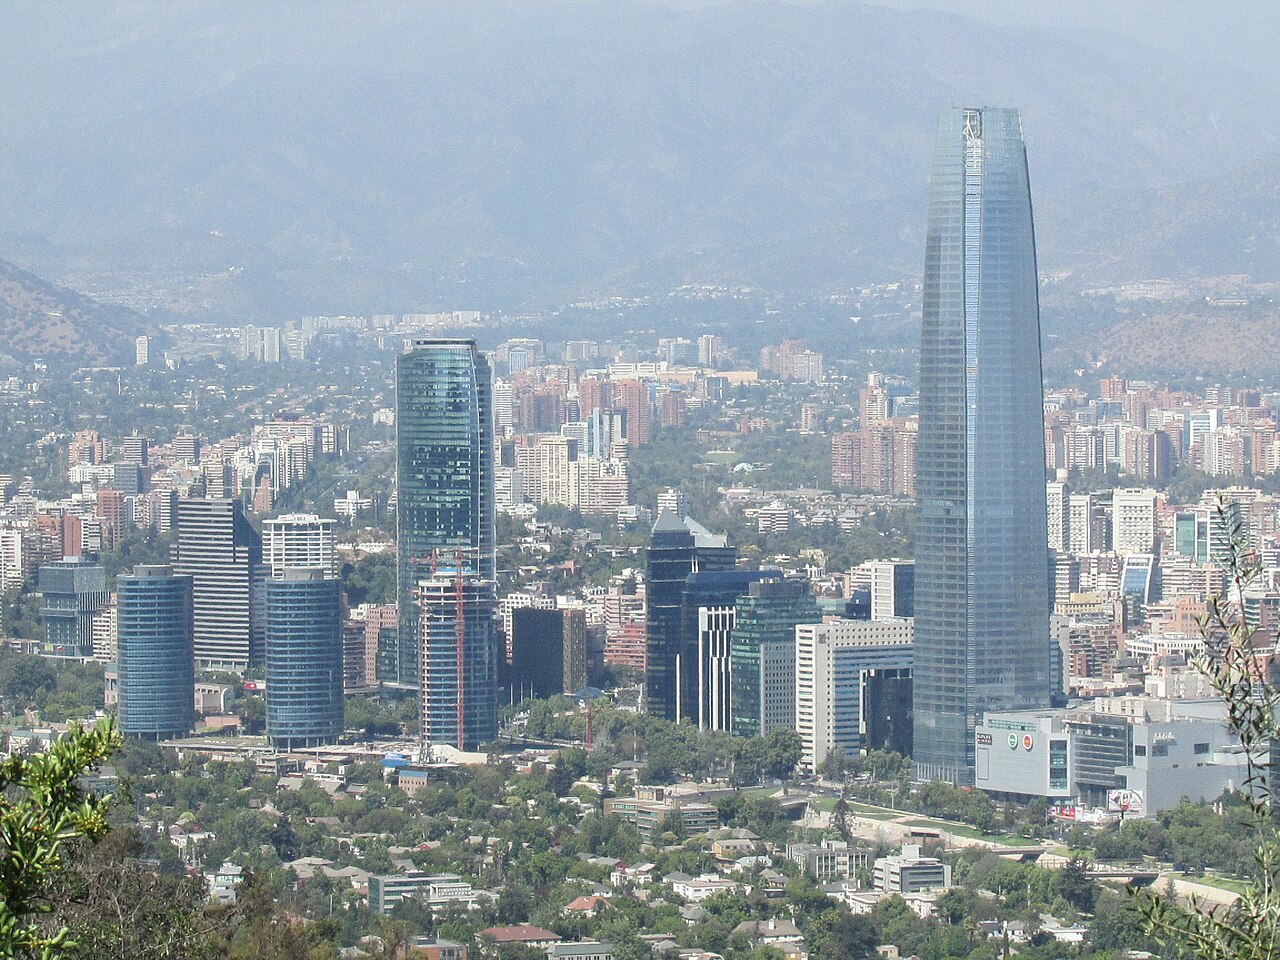
Where Copper Sits in Chips and Data Centres
Copper inside the chips themselves is tiny. The demand comes from the buildings around them: power supply, cooling and grid connections.
No primary source found for this analysis splits copper demand between chips and buildings, so the chip-content share is unquantified. The estimates below are analyst figures, not official data.
- A traditional data centre uses 5,000 to 15,000 tonnes of copper, and large AI-optimised sites up to about 50,000 tonnes, according to a Skillings summary of analyst estimates.
- J.P. Morgan Global Research estimates that data centres will consume about 475,000 tonnes of copper in 2026, roughly 1.7% of a global market of about 28.7 million tonnes, according to Skillings.
The research found no data on Korean or Taiwanese copper imports tied to chip fabrication plants. Seoul’s budget is therefore a signal of direction, not a measured tonnage.
Live Market IntelligenceChile — Live Market Board
Rio Times · Live Market Intelligence
Chile — Live Market Board
+1.44%
167,921.80
-0.75%
69,779.20
-0.01%
10,401.54
+1.44%
2,848,945
—
2,490.92
+0.04%
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IPSA | 10,401.54 | +1.44% | — | 10,254.15 | 10,722 | 10,633 | — |
| USD/CLP | 983.47 | -0.57% | +5.64% | 989.13 | 991.87 | 979.07 | — |
| COPPER | 6.65 | +2.24% | +29.44% | 6.51 | 6.66 | 6.54 | 37,751 |
| SQM-B | 59,350 | +5.00% | +41.63% | 56,525 | 59,500 | 56,800 | 139,333 |
| COPEC | 6,587 | +1.26% | -0.72% | 6,505 | 6,678 | 6,523 | 651,577 |
| BSANTANDER | 78.27 | +0.22% | +18.23% | 78.10 | 79.08 | 78.04 | 29,319,739 |
| FALABELLA | 6,537 | +0.57% | +12.38% | 6,500 | 6,569 | 6,451 | 521,197 |
| ENELAM | 83.60 | -0.61% | -7.37% | 84.11 | 85.95 | 83.33 | 17,436,403 |
| CENCOSUD | 1,818 | -0.12% | -37.29% | 1,820 | 1,836 | 1,810 | 1,172,754 |
| CMPC | 935.00 | -0.52% | -28.63% | 939.90 | 939.76 | 933.04 | 507,661 |
| BANCO CHILE | 192.44 | +0.90% | +20.05% | 190.73 | 192.99 | 190.73 | 16,978,917 |
| LATAM AIR | 22.04 | +2.04% | +4.75% | 21.60 | 22.20 | 21.81 | 859,178,133 |
| SOUTHERN COPPER | 192.19 | +3.32% | +50.65% | 186.01 | 193.86 | 185.75 | 649,631 |
China, the Smelter in the Middle
Chinese smelters turn Chilean and Peruvian concentrate into refined copper that data-centre builders eventually buy. Smelters charge miners a treatment fee for this work, and the fee shows who holds the upper hand.
S&P Global reported on 9 October 2026 that the 2026 benchmark charge for Chinese smelters was US$0 per tonne, down from US$21.25 in 2025. A zero benchmark charge means mine supply, not smelting capacity, is the bottleneck.
That favours miners over processors. China’s copper ore and concentrate imports in the first half of 2026 were roughly flat, down 0.84% year on year at 14.61 million tonnes, according to SMM, citing customs data, and monthly imports ran above 2.3 million tonnes from April to June.
Imports from Chile in that half were 4.2808 million tonnes, a 29.3% share of the total and down 8.3% year on year. Search summaries say Peru overtook Chile as China’s top concentrate supplier in June 2026, with 638,168 tonnes or 27.3% of imports.
That figure was not verified at source.
Chile and Peru Supply, Prices and US Tariffs
Chile Is Producing Less
Cochilco’s third-quarter report of 30 October 2026, summarised by the Rio Times, projects Chilean mine output of 4.94 million tonnes in 2026, down 8.4%, and 5.08 million tonnes in 2027, up 3%. Output from January to September was 3.63 million tonnes, down 8.5% on the year.
In August, Cochilco had forecast 5.27 million tonnes for 2026, down 2.6%, citing lower ore grades, maintenance and a weak start to the year. The newer, deeper cut shows how quickly supply expectations have worsened.
Cochilco itself pointed to “the limited response of mine output to demand that keeps growing”. Codelco, the state miner, has been led by Executive Chairman Jorge Gómez Díaz since the board named him on 3 June 2026.
Cochilco data show Codelco’s own output at 564,000 tonnes of fine copper in the first half of 2026, down 11% from 634,000 tonnes a year earlier, with restrictions at El Teniente and Chuquicamata and lower ore grades blamed for the drop. Higher prices have offset lower volumes.
Copper exports from January to September 2026 were US$49.25 billion, up 18.7% and 52.5% of all exports, at an average price of US$6.09 per pound, the Banco Central reported. President José Antonio Kast’s government holds the policy levers, and Daniel Mas Valdés serves as both Mining Minister and Economy Minister.
The research found no official plan from either to raise output quickly.
Peru Is Gaining Ground
Peru’s copper exports from January to August 2026 were US$26.513 billion, up 54.8%, Andina reported citing official data. Energy and Mines Minister Guillermo Shinno said, as reported by SMM, that Peru expects to add about 1 million tonnes a year of copper within five to six years.
Reporte Minero says eight projects are due to start construction in 2026 with US$7.6 billion of investment.
Price and US Tariffs
Cochilco raised its 2026 average price forecast to US$6.18 per pound and its 2027 forecast to US$5.95 from US$5.10. Its refined-balance forecast is a surplus of 144,000 tonnes in 2026.
Comex copper hit a record of about US$6.71 per pound on 13 May 2026, and London Metal Exchange prices were above US$14,000 per tonne in mid-May. A 50% Section 232 tariff on semi-finished copper and derivatives has applied since 1 August 2025.
A proclamation of 2 April took effect on 6 April 2026, splitting products into Annex I-A at 50% and Annex I-B at 25%, with derivatives made from US-smelted metal paying the higher of 10% or the MFN rate and products with under 15% metal content exempt. Law firm Steptoe describes a proposed second phase with a 15% tariff on refined copper from 2027 and 30% in 2028.
This could not be confirmed as official, and US-listed miners such as Freeport-McMoRan and Southern Copper were not reviewed for this analysis.
Three Scenarios
In a stabilising scenario, Chilean output recovers to 5.08 million tonnes in 2027 as Cochilco projects, and Peru’s new projects arrive on schedule. Supply would then catch up with demand and prices would drift toward Cochilco’s 2027 forecast of US$5.95 per pound.
In a tightening scenario, Chilean output stays near 4.9 million tonnes while AI building continues, and prices could revisit the May highs. Smelters would stay starved of ore, and the tariff cost to US builders would grow.
In a cooling scenario, the Korean budget stalls or AI investment slows, and Cochilco’s projected surplus weighs on prices. These are scenarios, not forecasts of fact.
What It Means for You
If you buy or build with copper, the 50% and 25% tariff tiers and the 10% rate for derivatives made with US-smelted metal matter as much as the London price. A proposed refined-copper tariff from 2027, if confirmed, would add a further cost for US data-centre developers.
If you own shares in US-listed copper miners, check each company’s quarterly guidance against Chile’s 8.4% forecast decline and Peru’s export growth. Chile’s exports earned more in 2026 despite lower volumes, which shows price can outrun tonnage.
For Latin America, the lesson is uneven. Chile gains revenue but loses volume, while Peru gains both and now competes with Chile for the Chinese market.
What Is Not Known
No source found for this analysis shows how much of Asia’s chip and AI spending becomes physical copper demand. The chip-content share and the Korean and Taiwanese import data remain gaps.
The final design and timing of any US refined-copper tariff are unconfirmed. Current copper prices are not confirmed.
What to Watch
- Chile’s October trade data, expected around 7 November 2026.
- The October Imacec from the Banco Central de Chile, expected around 1 December 2026.
- The Banco Central’s December Monetary Policy Report, and Cochilco’s monthly output releases.
- US Commerce Department or White House action on refined-copper tariffs.
The dates above are expectations and were not confirmed against the bcentral.cl calendar. Readers should check the official calendar before relying on them.
Related reading: Chile Culture, the Key Figures to Know in 2026; Chile Politics Explained, Who Holds Power in 2026; Chile Geopolitics Explained 2026; more from Chile.
Frequently Asked Questions
How do AI chips increase copper demand?
Mostly indirectly. Data centres need copper for power, cooling and grid connections, and analysts estimate 5,000 to 15,000 tonnes for a traditional site and up to about 50,000 tonnes for a large AI site. The chip-content share is not quantified.
How much is South Korea spending on AI and chips in 2027?
The budget sets aside 21.3 trillion won (US$15.8 billion at the conversion used in the Rio Times brief) for semiconductors, physical AI and AI data centres. The Korea Times reported on 1 September 2026 that this is up 97.2% on this year.
Is Chile’s copper output rising or falling?
Falling. Cochilco’s 30 October 2026 report projects 4.94 million tonnes in 2026, down 8.4%, and 5.08 million tonnes in 2027, up 3%. In August it had forecast 5.27 million tonnes for 2026.
Is Peru overtaking Chile in copper?
In sales to China, trade press says so for June 2026, with Peru at 638,168 tonnes of concentrate and 27.3% of imports. That figure was not verified at source. Peru’s copper exports from January to August 2026 were US$26.513 billion, up 54.8%, according to Andina.
What is the copper price forecast for 2026 and 2027?
Cochilco forecasts an average of US$6.18 per pound for 2026 and US$5.95 for 2027, up from US$5.10 in its earlier view. It also expects a refined surplus of 144,000 tonnes in 2026.
What US tariffs apply to copper?
A 50% Section 232 tariff has applied to semi-finished copper and derivatives since 1 August 2025. A proclamation of 2 April took effect on 6 April 2026, splitting products into Annex I-A at 50% and Annex I-B at 25%, with derivatives made from US-smelted metal paying the higher of 10% or the MFN rate and products with under 15% metal content exempt. A proposed tariff on refined copper is unconfirmed.
Sources: riotimesonline.com, koreatimes.co.kr, miningreporters.com, newsquawk.com, news.metal.com, riotimesonline.com. Retrieved 2 November 2026.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
In depth