Open Bank Account Honduras Foreigner 2026 — Residency, RTN and Dollar Accounts
GUIDES · HONDURAS
Key Facts
- —What it is A deposit account at a Honduran bank, held by a foreign resident or a visitor.
- —Who it’s for Retirees, rentistas, property owners and remote workers who need local payments or incoming wires.
- —What it costs The tax number is free; opening deposits and monthly fees are set by each bank.
- —Why it matters Rentista and pensionado residency requires income received through a Honduran financial institution.
- —The catch The cheap simplified savings account is reserved by rule for Honduran nationals only.
The open bank account Honduras foreigner question in 2026 turns on one thing — whether your papers match what the law already tells banks to collect.
Honduras lets foreigners open accounts, and the rules to open bank account Honduras foreigner applicants meet sit in national law. What decides your wait is the residency card, the free tax number and clean proof of income.
What Open Bank Account Honduras Foreigner Rules Require
Honduras runs no special regime for foreign depositors. The open bank account Honduras foreigner path follows the same anti-money-laundering rulebook as everyone else.
That rulebook is the regulation issued under the Special Law Against Money Laundering, Decree 144-2014. It was published in the official gazette on 28 May 2016.
The regulation defines valid identification for a foreigner as a passport or a residency card. For Hondurans it accepts the identity card, the driving licence or the passport.
Your file must also carry your full name, nationality, exact address and telephone number. Banks then add your monthly income, economic activity, workplace and the source of your funds.
One shortcut is closed to you. The simplified basic savings account, which opens with 10 lempiras (about US$0.37), is reserved for Honduran nationals.
That restriction comes from a banking commission circular issued in December 2022. A foreigner therefore goes through the full customer due-diligence file instead.
A foreigner usually has to open the account in person, at a bank branch in Honduras. Expect signatures, copies of every passport page and a short interview about how the account will be used.
Why Residency Status Decides Your Timeline
A residency card does more than prove identity. It answers most of what the open bank account Honduras foreigner checklist asks about you.
The law lets a bank in Honduras open an account for a foreigner holding only a passport. Each bank still applies its own risk policy on top of the law, and those policies differ.
Residency itself pushes you toward a local account. The immigration service requires rentista applicants to show monthly income of at least US$2,500.
Pensionado applicants must show a pension of at least US$1,500 a month. Investor applicants must show US$50,000 invested, plus a US$5,000 deposit at the central bank.
In each case the money must be received in Honduras through an institution of the national financial system. So the bank file and the residency file depend on each other.
That circle is the practical heart of the process. Most applicants solve it by starting both files in the same trip, rather than one after the other.
The RTN, Your Address and Proof of Income
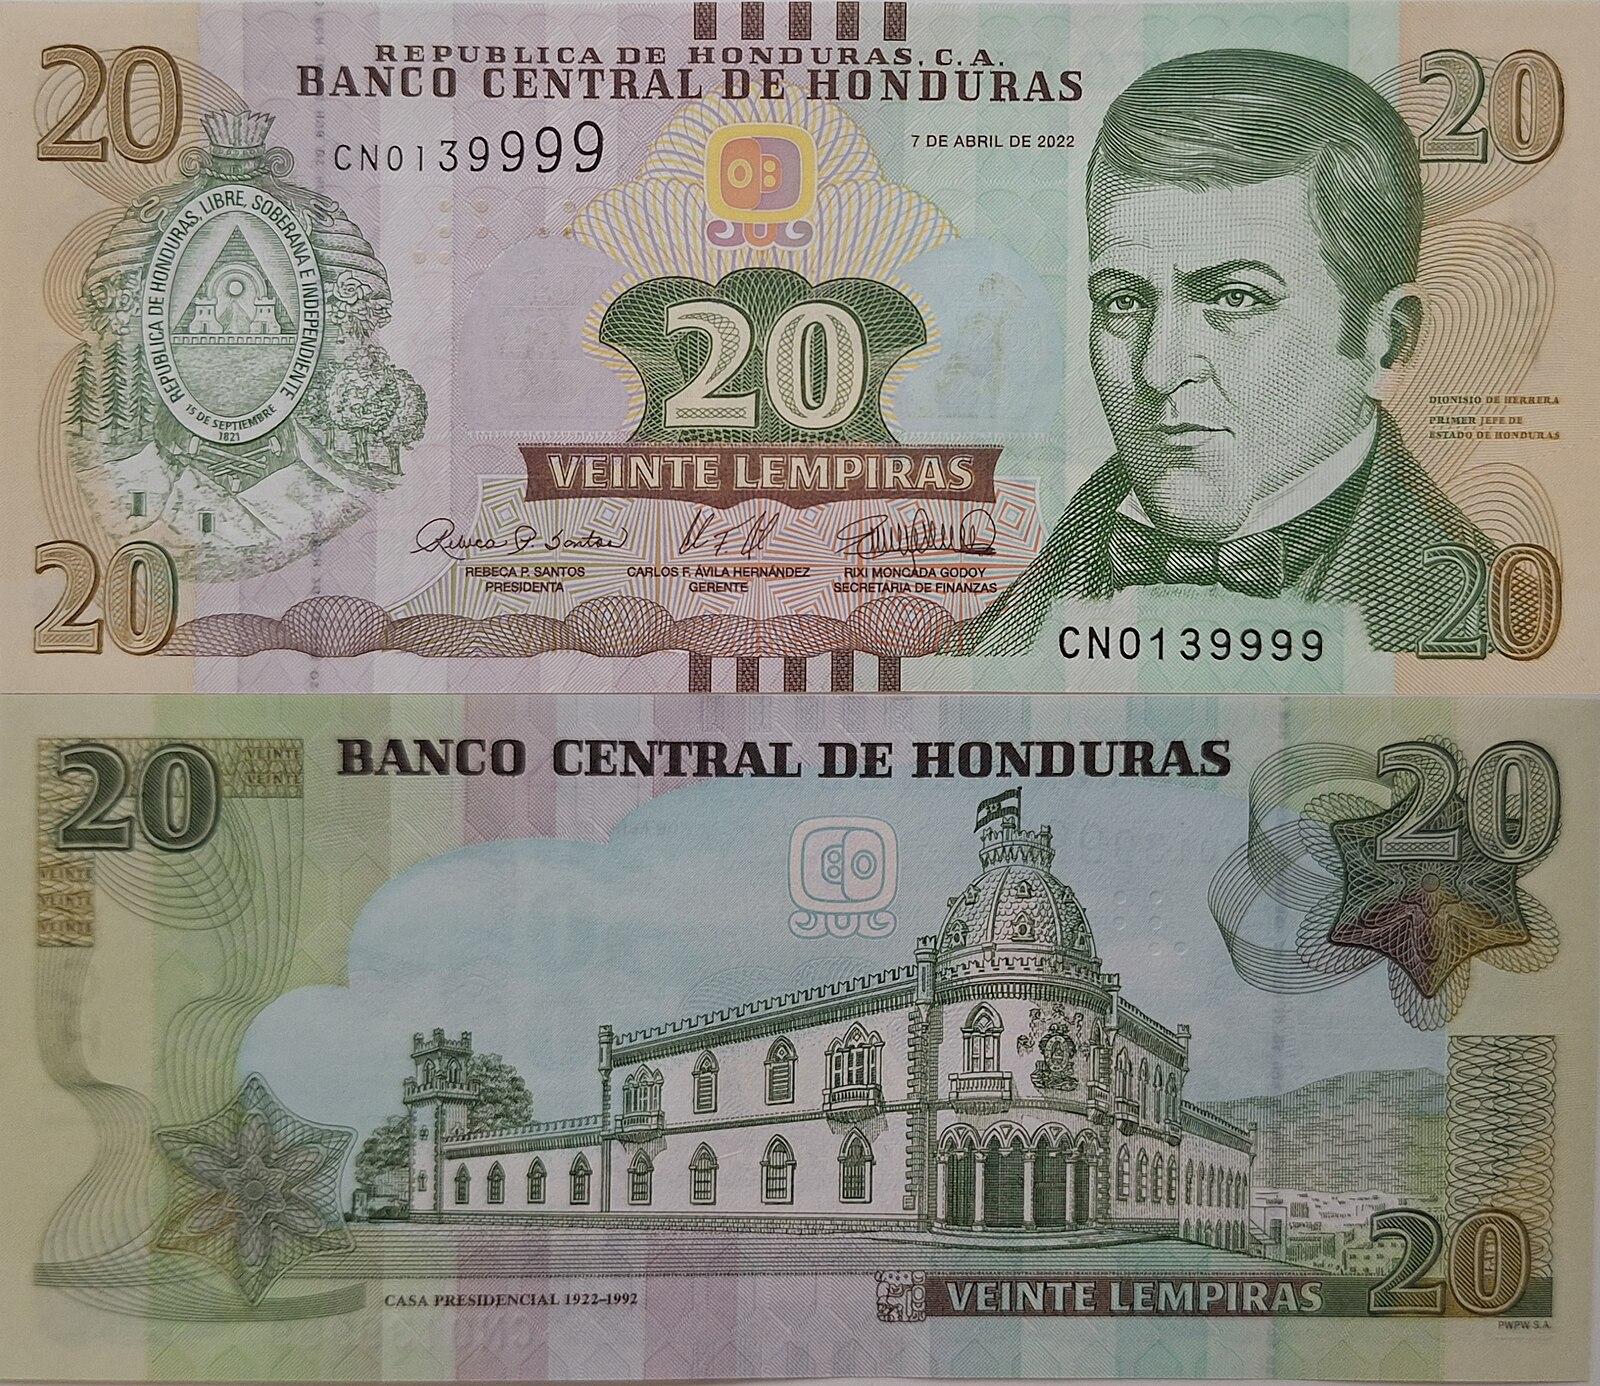
The RTN is the national tax registry number, issued by the revenue service. The service says registration is free and lists opening a bank account among its everyday uses.
Proof of address is usually a utility bill, a lease or a letter from your landlord. Your file must show an exact address, down to the municipality.
Proof of income can be a pension statement, an employment letter or bank statements. What the bank is testing is whether the origin of the money is clear.
The account file a foreigner opens at a bank in Honduras is not finished on opening day. For higher-risk customers the rules require an annual refresh of identification data.
They also require the bank to verify a new customer’s information within six months. A request for updated papers months later is routine, not suspicion.
Dormant accounts carry their own rule. When an inactive account is reactivated, the bank must update the customer’s data first.
Lempira and US Dollar Accounts
Honduras keeps its own currency, the lempira, and is not dollarised. Dollar accounts exist anyway, by regulation rather than by bank favour.
A central bank regulation allows foreign-currency deposits as chequing, demand, savings and term accounts. It dates from December 2006 and was reformed in March 2012.
The banking commission supervises compliance with that regulation. Which dollar products a branch will actually open still depends on the bank.
The rate matters for anyone funding an account from abroad. The reference rate moved from 26.3737 lempiras per dollar on 2 January 2026 to 26.7657 on 20 July 2026.
At 23 September 2026 exchange rates, the lempira trades at about 26.89 to the dollar. That is a slow, managed slide, not a peg and not a free float.
The central bank sells dollars through auctions, a mechanism it reactivated in April 2023. Direction matters more than any single day’s quote, and the drift has been gently downward.
A dollar balance helps if your bills and income are in dollars. It costs you if you really spend in lempiras and end up converting twice.
Which Banks, and What Deposit Insurance Covers
Fifteen private banks are listed as contributors to the national deposit insurance fund. They include Banco Atlántida, BAC Credomatic, Ficohsa, Banco de Occidente, Banpaís, Banco Lafise and Banco Promérica.
Savings and loan associations, finance companies and branches of foreign private banks also contribute. Membership is a legal duty, not a marketing badge.
The cover is written in dollars and converted into lempiras. The law fixes it at US$9,632.92 for each depositor at each institution, reconverted every January.
For 2025 that worked out at 245,706 lempiras (about US$9,100) per depositor. Cover applies only if an institution is declared in forced liquidation.
Foreign-currency deposits are covered too, and can be paid in the same currency or in lempiras. That detail matters if you hold dollars rather than lempiras.
Deposit insurance is a poor reason to choose one bank over another. It is a good reason to think about how much you keep in a single institution.
Wires, Remittances and FATCA for US Citizens
Honduran banks are used to dollars arriving from abroad. Remittances reached US$7,692.2 million between January and July 2026, up 11.2 percent on a year earlier.
Those flows are worth more than a quarter of national output. A wire from a pension fund or an employer is ordinary work for a compliance team.
The rules require the same data on every transfer, whatever the amount. That means both names, both account numbers, the date, the amount and a transaction reference.
Your passport or residency card number travels with the transfer. A mismatch between the name on the wire and the name on the account is the usual cause of delay.
Honduras signed a Model 1 agreement with the United States on 31 March 2014. It entered into force on 19 February 2015.
Under that model, Honduran banks report US account holders through their own authorities. A US citizen should expect tax-residency questions and a request for a US taxpayer number.
The Bay Islands, Daily Banking and the Regional Picture
Roatán and the other Bay Islands raise the same questions as the mainland. The rules are national, so a foreigner can open a bank account in Honduras under the same law anywhere.
What changes on the islands is choice and convenience. Fewer branches means fewer products, and a mainland trip is sometimes the faster route.
Property buyers usually want the account open before closing. A local account with dollar capability simplifies paying deposits, lawyers, taxes and utilities.
Mobile and online banking arrive after the account exists, not before. Ask at the branch which channels your account type includes, and what each one costs.
Against its neighbours, Honduras sits in the middle. El Salvador uses the US dollar, so the currency question disappears there.
Guatemala, like Honduras, keeps its own currency and offers dollar accounts beside it. What sets Honduras apart is the rule routing residency income through a local institution.
The open bank account Honduras foreigner process rewards patience, not speed. The file you assemble once, cleanly, is the file your bank will ask you to refresh for years.
Connected Coverage
Taxes in Honduras for Expats 2026 — Territorial Rules, Rates and What You Owe
Honduras Visa and Residency 2026 — Routes, Income Rules and What They Cost
Honduras Lets Foreigners Buy One Coastal Home on 3,000 Square Metres
What Is Not Known
The deposit insurance fund had not published a maximum insured amount for 2026 when this guide was written. The 2025 figure of 245,706 lempiras (about US$9,100) is the last one on record.
No official source publishes minimum opening deposits or monthly fees across Honduran banks. Each institution sets its own tariff, and the figures quoted by comparison sites are not verified here.
Whether a given branch will open an account on a passport alone is an internal risk decision. Those policies are not public, and they differ between banks and between branches.
International transfer fees and correspondent routes are not published centrally. Nor is there an official service standard for how long an account approval should take.
How many foreigners hold Honduran accounts is not published by the regulator. There is therefore no official measure of how often applications are refused.
Sources: Checked against the National Institute of Migration, the National Banking and Insurance Commission, the Deposit Insurance Fund, the Revenue Administration Service, the Central Bank of Honduras and the United States Treasury.
- inm.gob.hn
- pplaft.cnbs.gob.hn
- circulares.cnbs.gob.hn
- fosede.hn
- tsc.gob.hn
- sar.gob.hn
- bch.hn
- home.treasury.gov
Frequently Asked Questions
Can a foreigner open a bank account in Honduras without residency?
The anti-money-laundering rules accept a passport as valid identification for a foreigner. A residency card still makes the file easier, because it ties you to a Honduran address and a tax record. Each bank applies its own risk policy on top of the law.
What documents do I need to open a bank account in Honduras?
A passport or residency card, your nationality, an exact address and a telephone number. Banks also record your monthly income, your economic activity, your workplace and the source of your funds. The RTN tax number is registered free with the revenue service.
Can foreigners open US dollar accounts in Honduras?
Yes. A central bank regulation allows foreign-currency deposits as chequing, demand, savings and term accounts. Which dollar products a branch will open still depends on the bank.
Does FATCA affect US citizens banking in Honduras?
Honduras and the United States have a Model 1 agreement that entered into force in February 2015. Under that model, Honduran banks report US account holders through their own authorities. Expect tax-residency questions and a request for your US taxpayer number.
Are deposits in Honduran banks insured?
Private banks, savings and loan associations, finance companies and branches of foreign private banks contribute to the national deposit insurance fund. The cover is written in dollars, reconverted each January, and applies only in a forced liquidation. Foreign-currency deposits are covered as well.
Why do Honduran banks ask for updated documents later?
The rules require a bank to verify a new customer’s information within six months of opening. Higher-risk customers face an annual refresh of their identification data. An inactive account must also be updated before it can be reactivated.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
Read More from The Rio Times