US Bond Yield Tops 5% as China Sales Slow | Global Economy, Nov 16
Key Facts
- The US 10-year Treasury yield is 5.14%, up 29 basis points (0.29 percentage points) in five sessions, the rate the US government pays to borrow for a decade, and the price tag on almost every loan in the world.
- Wall Street’s fear gauge, the VIX, stands at 19.30, down 24.73% over five sessions even though it rose 3.21% on Friday; investors are calmer than the bond market’s message would suggest.
- Japan’s economy stalled in the third quarter, with growth of 0.0% on the quarter against 0.1% expected, and an annualised rate of -0.1% against 0.3% forecast, as shoppers and exporters both weakened.
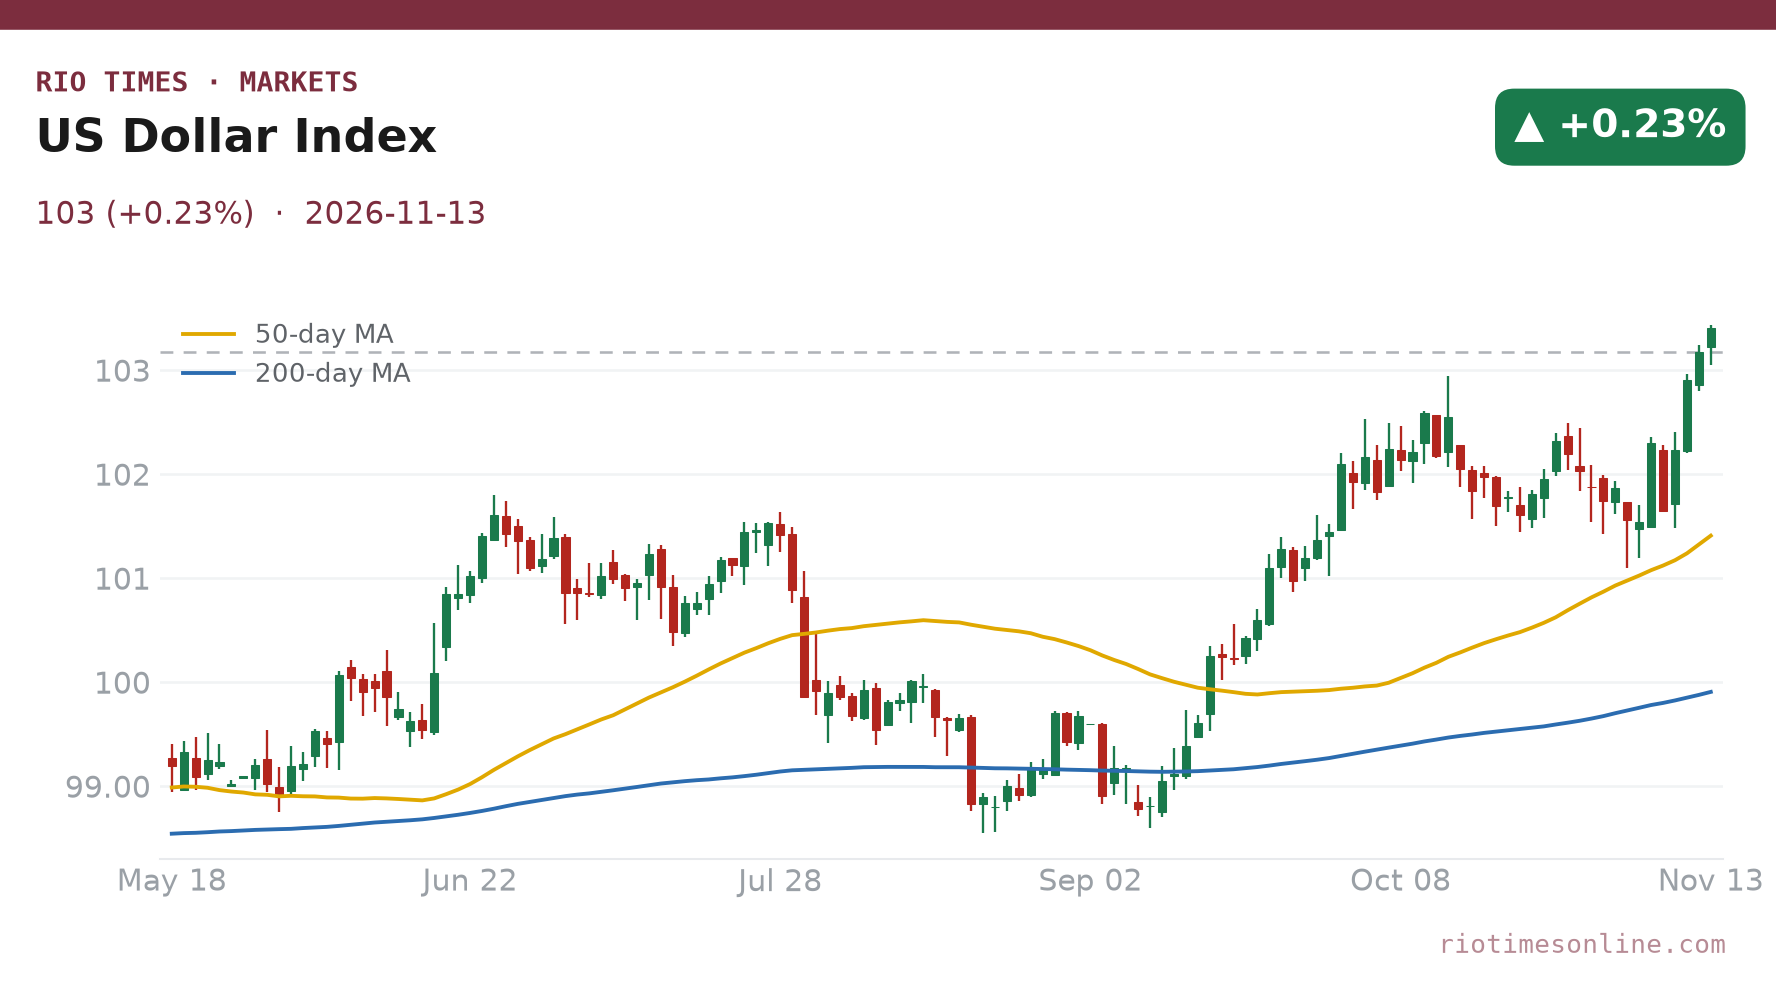
- The US dollar index reads 103.41, up 0.23% on Friday and 1.09% over five sessions, as higher US yields pull global money towards dollar assets.
- Oil is drifting lower, not higher: the USO fund, which tracks US crude, fell 0.34% on Friday and 1.91% over five sessions, while official US data showed commercial crude stocks up 4.7 million barrels to 414.4 million.
Today’s Focus
The world’s most important interest rate has climbed 29 basis points in a week, to 5.14% on the US 10-year Treasury. That is the cost of lending to Washington for ten years, and everything from mortgages to company bonds is priced off it.
The odd part is that stocks did not flinch. The S&P 500, the broad index of 500 large US companies, is up 2.51% over five sessions, and the VIX fear gauge has fallen sharply — yet both closed Friday lower, and the Nasdaq is 8.9% below its 6 October peak.
Our best-supported reading, with medium confidence, is that bond investors are repricing the Federal Reserve’s next move after hot inflation data. Core consumer prices rose 0.3% in October, as they did in August and September, and traders have moved towards a quarter-point rate rise in December.
Overnight, Japan added a soft note: its economy flat-lined in the third quarter, which keeps one of the world’s largest economies from offering any help.
What matters today. Whether the 10-year yield holds above 5% — if it does, stocks must justify their prices against a risk-free return that is hard to ignore.
| Instrument | Level | Session |
|---|---|---|
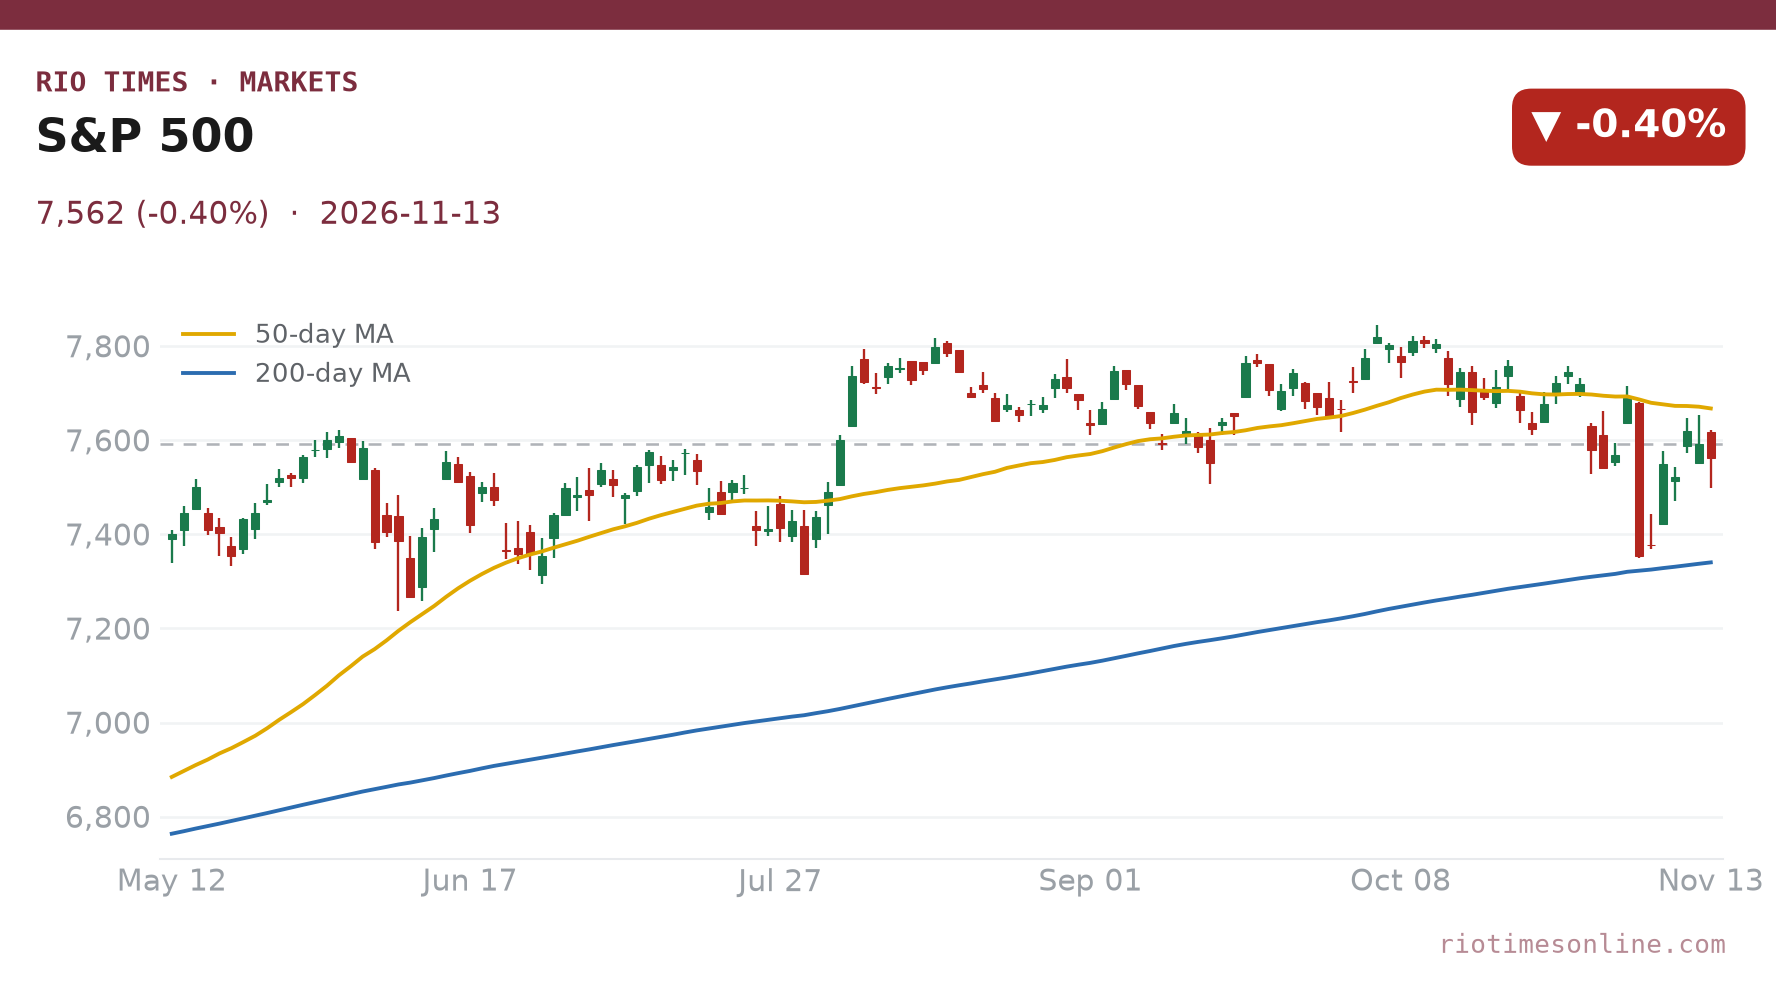
| S&P 500 (US) | 7,562 | -0.40% |
| Ibovespa (Brazil) | 172,458 | +0.66% |
| USD/BRL | 5.6675 | +0.46% |
Source: market close, 13 November 2026.
01 The world in one read
Friday closed with the market pulled in two directions. Stocks were slightly lower, the dollar firmer and government bond yields higher — a pattern that usually signals worry about interest rates, not about growth.
Japan’s third-quarter figures added a weaker note from Asia, with consumers and exports both shrinking. China’s house prices fell 2.4% in October from a year earlier, a smaller drop than the 2.8% decline of the month before. China’s October activity data, published early Monday, also came in soft: retail sales rose 0.4% on the year against 0.8% forecast, factory output 4.8% against 5.3%, and fixed-asset investment fell 8.1% year to date.
The week ahead is dense: US retail sales, industrial production and the ZEW, a German investor-sentiment survey, all land on Tuesday. Together they will test whether the bond market’s caution is justified.
The evidence points one way: a higher dollar, a 29 basis point jump in the 10-year yield and a weaker gold price all say investors expect rates to stay higher for longer. Equities say otherwise, with the VIX down 24.73% over five sessions, and the gap between the two cannot last for ever.
Our confidence is medium because futures pricing for the December Fed meeting moves daily. The variable to watch is Tuesday’s US retail sales, which will show whether the consumer can carry a 5% bond yield.
02 The global board
| Instrument | Level | Change | Read |
|---|---|---|---|
| US 10-year Treasury yield | 5.145% | +0.21% | Back above 5%; the story of the week |
| S&P 500 | 7,562 | −0.40% | Second down session in a row, 3.3% below its 6 October high |
| Nasdaq | 25,136 | −0.91% | Technology shares lead the retreat when yields rise |
| VIX fear gauge | 19.3 | +3.21% | Ticked up Friday but far below last week’s level |
| US dollar index | 103.412 | +0.23% | Firm as US yields attract global money |
| Gold | $3,874/oz | −0.16% | Gold pays no interest, so it suffers when yields rise |
| Silver | $48.6375/oz | −2.95% | Hit harder than gold, as industrial metals often are |
Read the table from the top: the bond yield is the cause, the rest are reactions. Technology shares feel it most because their profits lie further in the future and are worth less when money costs more.
The VIX is the odd one out. It sits well below where it stood a week ago, so the market is rattled by rates but not yet frightened. Rio Times · Live Market Intelligence
Live Market IntelligenceGlobal Markets — Live Board
Global Markets — Live Board
Instrument Last Change YoY Prev. High Low Volume
SPX
7,562
-0.40%
—
—
—
—
—
NDX
27,944
-1.22%
—
—
—
—
—
DJI
52,348
+0.10%
—
—
—
—
—
RUT
2,790
-0.31%
—
—
—
—
—
US10Y
5.1540
+1.00%
—
—
—
—
—
VIX
19.30
+3.21%
—
—
—
—
—
DAX
26,750
-0.08%
—
—
—
—
—
FTSE
10,903
+0.36%
—
—
—
—
—
CAC
8,369
+0.09%
—
—
—
—
—
STOXX
664.14
+0.02%
—
—
—
—
—
NIKKEI
60,035
-1.81%
—
—
—
—
—
HSI
23,844
+0.87%
—
—
—
—
—
KOSPI
5,139
-2.87%
—
—
—
—
—
CSI300
3,994
-0.56%
—
—
—
—
—
NIFTY
25,287
+0.57%
—
—
—
—
—
TSX
36,106
-0.09%
—
—
—
—
—
GOLD
3,875
-0.30%
-4.91%
3,886
3,904
3,863
31,606
SILVER
47.49
-3.14%
-6.19%
49.03
49.01
47.28
15,365
03 The main event — a 5.14% Treasury yield tests the rally
The 10-year Treasury yield is up 29 basis points in five sessions, to 5.14%. The move built through the week: the yield stood at 4.86% on 6 November and 5.00% on 11 November.
Cause one, with medium confidence: inflation. The US Bureau of Labor Statistics reported on 10 November that October consumer prices rose 0.4% on the month, with core prices (excluding food and energy) up 0.3%. The Fed’s last decision on 28 October was to hold its policy rate at 3.75–4.00%, with its next meeting on 9 December.
Cause two, with lower confidence: energy. Oil can feed through to inflation expectations, though crude has eased in November.
The bigger picture: the S&P 500 is 19.2% above its 30 March low of 6,344 but 3.3% below its 6 October high of 7,819, and has slipped 1.28% over 20 sessions. This looks like a pause in a long climb, not a new downturn — yet.
04 Policy and data
The Federal Reserve, America’s central bank, meets on 9 December. Traders lean towards a quarter-point rise, so the data between now and then carries extra weight.
Tuesday brings US retail sales (consensus +0.2% against 0.8% before), with the key ‘control group’ measure expected at +0.4%. Industrial production is forecast at +0.1% against 0.7% before.
In Europe, the German ZEW survey of current conditions is expected at -35 against -35.9 before; a reading near that confirms an economy that is struggling, not collapsing.
Japan’s third-quarter report (RT economic calendar) showed private consumption down 0.3% and external demand down 0.6% on the quarter. Capital spending was the one bright spot, up 1.6% against 1.5% expected, and Japan’s trade figures arrive on Tuesday night.
05 Commodities and currencies
Oil is easing, not surging. Official data from the US Energy Information Administration (eia.gov) show commercial crude stocks up 4.7 million barrels to 414.4 million in the week to 6 November, gasoline stocks up 1.8 million to 210.8 million and distillates up 4.1 million to 103.3 million.
More stock than expected is the likely reason the USO fund fell 0.34% on Friday. A fresh weekly stock report from the American Petroleum Institute lands on Tuesday night.
Gold is the casualty of high yields. The GLD gold fund is down 4.6% over five sessions and spot gold has slipped from US$4,134 on 9 November to US$3,874, because a bond paying 5.14% is a hard rival for a metal paying nothing.
The dollar index at 103.41 is the quiet winner. Its strength matters to every traveller and company that earns or owes money outside America.
Calendar detail for Friday 13 November (RT economic calendar): euro-zone GDP Growth Rate 1.3 (previous 1.2); Balance of Trade s.a -8.7 (previous -7.8); Balance of Trade -10.3 (previous -16.6). US Department of Agriculture weekly export sales: USDA Wheat Net Export Sales Next Year 0, USDA Corn Gross Export Sales 2922.3, USDA Beef Net Export Sales 9.6, USDA Soybean Meal Net Export Sales Next Year -0.2, USDA Pork Gross Export Sales 41.5, USDA Beef Gross Export Sales 12.2, USDA Upland Cotton Gross Export Sales 162.3, USDA Wheat Gross Export Sales 198.7, USDA Soybean Oil Net Export Sales 1.7, USDA Wheat Net Export Sales Total 182.8, USDA Soybean Net Export Sales Total 1166, USDA Soybean Oil Net Export Sales Total 1.7, USDA Soybean Gross Export Sales 1388.2, USDA Soybean Net Export Sales Next Year 11.2, USDA Corn Net Export Sales Next Year 594.4, USDA Corn Net Export Sales Total 3475.8, USDA Pork Net Export Sales 39.5, USDA Corn Net Export Sales 2881.4, USDA Wheat Net Export Sales 182.8, USDA Soybean Meal Net Export Sales 360.9, USDA Soybean Meal Net Export Sales Total 360.7, USDA Soybean Net Export Sales 1154.8, USDA Upland Cotton Net Export Sales 157.3 (figures as published, in the agency’s reported units).
Also due today: China’s October data, Industrial Production YTD 5.3 (previous 5.3); Unemployment Rate 5.1 (previous 5.2); Retail Sales YTD 1.04 (previous 1.13); USDA Soybean Export Inspections (previous 1896.151), USDA Wheat Export Inspections (previous 248.536), USDA Corn Export Inspections (previous 905.267) are scheduled for the US afternoon.
06 The Latin American read-through
The pressure shows up first in currencies. The Brazilian real weakened 0.46% on Friday to 5.6675 per dollar, the weakest in its 12-month range, while the Colombian peso lost 1.08% to 3,315.
Mexico’s peso was firmer, at 18.5525 per dollar (−0.27%), and Chile’s peso was little changed at 994.88. Stocks were mixed: Brazil’s Ibovespa, its main stock index, rose 0.66% to 172,458, while Mexico’s IPC fell 0.84%.
Higher US yields draw money back to America, which is the old pressure on emerging markets. Brazil’s Ibovespa is 17.5% below its 9 October peak of 209,067 but 11.9% above its 12-month low of 154,064 from 7 November 2025.
Our own history gives a calmer note. The Ibovespa has fallen 15.60% over 20 sessions; in the 10 earlier cases of a fall that large since 2007, it was higher 20 sessions later in 6 of 10 (60%), with a median gain of 2.9% and a worst case of 19.8% lower. History is not a forecast.
Today Brazil publishes its IBC-BR activity index (consensus −0.29% against 0.3% before) and an IGP-10 inflation reading (a Brazilian price index) expected at 0.8% against 1.76% before. Tomorrow Colombia reports growth, forecast at 1.6% against 1.3% before.
07 What to watch
- US 10-year yield at 5%: A close below 5% would ease pressure on stocks and emerging-market currencies; a rise further above it would tighten conditions.
- US retail sales, 17 November: Consensus is +0.2% against 0.8% before; a strong figure strengthens the case for a Fed rise on 9 December.
- Fed meeting, 9 December: The next rate decision from America’s central bank, and the date by which the hike question gets answered.
- S&P 500 at 7,819: The 6 October high is the level that stocks need to beat to show the rally has resumed; round-number support lies near 7,500.
Background: Nasdaq Falls 0.9% as US Bond Yield Tops 5%.
Background: US 10-Year Yield Tops 5% as Gold Drops 0.2%.
Frequently Asked Questions
Why do US Treasury yields matter to everyday investors?
They set the cost of borrowing across the world, from mortgages to company loans. When the 10-year yield rises, safer assets look more attractive and shares often come under pressure.
What is a basis point?
A basis point is one hundredth of a percentage point. A rise of 29 basis points means the yield went up by 0.29 percentage points.
Why is gold falling when markets are nervous?
Gold pays no interest. When Treasury yields climb to 5.14%, holding bonds becomes a better deal than holding gold, so the GLD gold fund has fallen 4.6% in five sessions.
How does this affect Latin America?
Higher US yields tend to strengthen the dollar and pull money out of emerging markets. The Brazilian real at 5.6675 per dollar and the Colombian peso at 3,315 both weakened on Friday.
Market data: The Rio Times
This article was produced by The Rio Times’ automated AI newsroom. Editorial responsibility: Matthias Camenzind, Publisher and Editor-in-Chief. The Rio Times also runs Ask Rio Times, which answers from 100,000+ of our own articles, the daily Latin America Power Map, and prediction-market odds on elections and markets.. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.