YPF Sells Two Mendoza Oil Clusters for US$405 Million to Separate Buyers
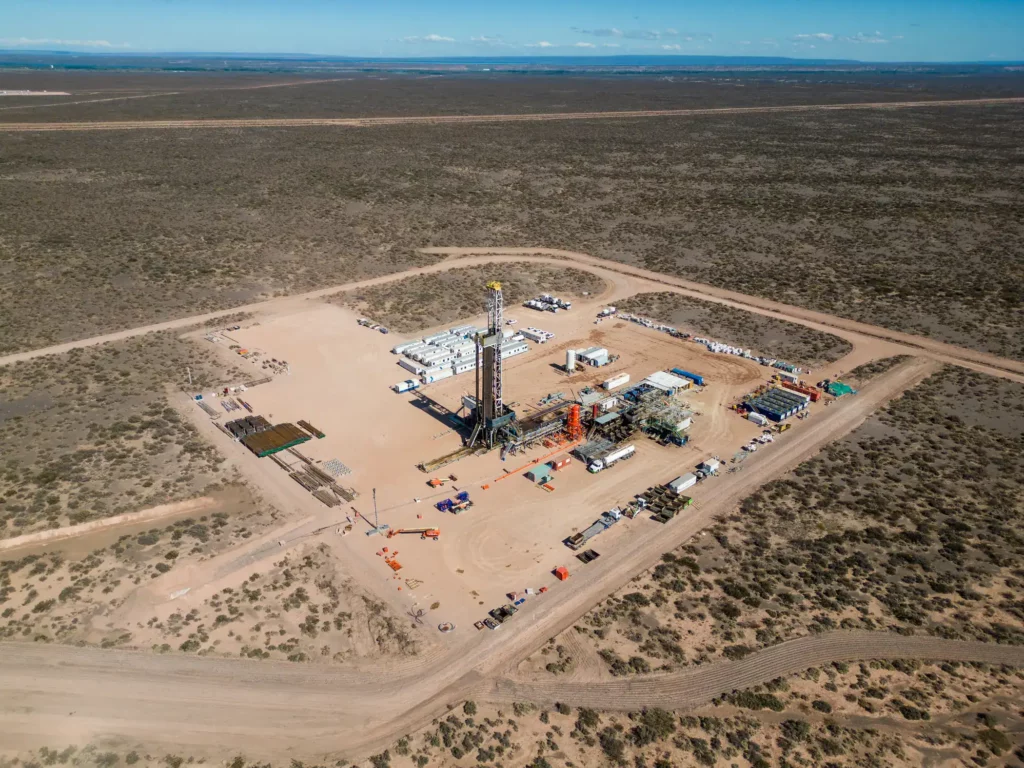
YPF has agreed to sell two clusters of mature conventional oil assets for a combined US$405 million to two separate buyer groups, shedding roughly 17,000 barrels per day as Argentina’s state-controlled producer concentrates capital on Vaca Muerta.
YPF’s US5 Million Exit From Two Mature Clusters
YPF, the oil company controlled by the Argentine state, has agreed to sell two packages of mature conventional assets for a combined US$405 million. Together the clusters account for roughly 17,000 barrels per day of production. The acreage lies in the provinces of Mendoza and La Pampa. Both packages are conventional, rather than the shale acreage that now drives the company’s growth plans.
The two clusters went to different buyers. The Chachahuén cluster, agreed at US$200 million with economic effect from 1 June 2026, was sold to Energía Mendocina S.A. and Compañía Andina de Petróleo y Gas S.A., companies linked to Grupo Álvarez and Integra Capital. The ‘Mendoza No Operado’ cluster, agreed at US$205 million and backdated to 1 January 2026, went to San Benito Upstream S.A.U., a vehicle linked to Pecom. Neither buyer took both packages.
Effective dates of this kind are standard in upstream deals, since they determine which party is credited with the cash flow generated between that date and the formal closing. Here the two packages carry different starting points, one prospective and one retroactive. That difference alone can move the amounts finally exchanged at completion.

Inside the Chachahuén Package
The Chachahuén cluster was agreed at US$200 million and takes economic effect from 1 June 2026. The buyers are Energía Mendocina S.A. and Compañía Andina de Petróleo y Gas S.A., both linked to Grupo Álvarez and to Integra Capital, and Pecom is not a party to this half of the transaction. The package groups four concessions: Chachahuén Sur, Cerro Morado Este, Puesto Hernández and Chihuido de la Sierra Negra.
Combined output is about 10,000 barrels per day of oil, which makes Chachahuén the larger of the two packages in volume terms despite carrying the slightly lower price. The other cluster contributes roughly 7,000 barrels per day, so the implied value per flowing barrel is higher for the non-operated stakes. Such comparisons are only a rough guide. Valuations in mature conventional deals depend on reserves, decline rates, operating costs and future obligations as much as on current output.
Live Company IntelligenceYPF Sociedad Anonima — the full investor dossier
The Mendoza No Operado Stakes
The second package was agreed at US$205 million, with economic effect backdated to 1 January 2026, and was acquired by San Benito Upstream S.A.U. It comprises a 30.01% interest in the CNQ-7 Gobernador Ayala concession and 50% interests in CNQ-7A and Jagüel Casa de Piedra. The blocks sit between the provinces of Mendoza and La Pampa. These are partial participations rather than whole-field positions, and together they represent roughly 7,000 barrels per day.
The cluster’s name, Spanish for ‘Mendoza not operated’, points to the nature of the holdings: interests in blocks that YPF did not itself operate. A non-operating partner funds its share of investment and receives its share of production, but day-to-day decisions rest with the operator. Selling such positions removes capital commitments over which the seller has limited direct control.
Reporting on the transaction links it to El Corcobo, describing the US$205 million as the payment that completes Pecom’s control of the area by acquiring the interests it lacked in Malargüe and La Pampa. On that reading, the sum is the same US$205 million already contained in the US$405 million total. It should be read as one component of the overall deal value, not as an additional payment on top of it.
Who the Buyers Are
Pecom is the oil company of the Pérez Companc family, a name long associated with Argentine energy. San Benito Upstream S.A.U., the vehicle named in the non-operated transaction, carries the Argentine corporate form used for single-shareholder companies, a structure commonly employed to ring-fence a defined set of assets. Dedicated entities of this kind are routine in upstream acquisitions.
Argentine energy trade press, citing Energy Secretariat production filings, reported that Pecom had already become the country’s second-largest conventional crude producer before this deal, after buying the Manantiales Behr area in Chubut for US$410 million. The Mendoza No Operado package adds to that base rather than creating it. Ranking by conventional output is also not the same as ranking by total production, since the national mix has shifted heavily toward unconventional barrels from Vaca Muerta.
On the Chachahuén side the counterparties are Energía Mendocina S.A. and Compañía Andina de Petróleo y Gas S.A., identified in reporting as linked to Grupo Álvarez and to Integra Capital. That grouping is a smaller and less familiar name in the upstream sector than the Pérez Companc business. Its arrival as the holder of four Mendoza concessions is one of the more consequential details of the announcement for the province.
Plan 4×4 and the Pivot to Vaca Muerta
YPF has framed the sales as part of what it calls Plan 4×4, a strategy of divesting conventional assets in order to concentrate investment in Vaca Muerta, the shale formation in the province of Neuquén. The logic is portfolio concentration: fewer and larger positions in the acreage the company considers most competitive. Each disposal both raises cash and removes future spending obligations.
Shale development is capital-intensive at the front end, with drilling, completion and transport commitments that compete directly with maintenance work in older fields. Producers pursuing that path typically fund it by recycling proceeds from lower-growth assets rather than by expanding borrowing indefinitely. Concentration also reduces the overhead of managing scattered concessions across several provinces, while increasing exposure to the fortunes of a single play.
Why Mature Conventional Fields Suit a Different Owner
Mature conventional fields rarely stop producing because the oil is exhausted; they become marginal when the cost of lifting each barrel rises faster than its value. Water output climbs, wells require more frequent intervention and surface facilities age. Inside a large diversified producer, those fields compete for capital against projects promising far steeper growth, and they usually lose.
A specialised owner can treat the same assets differently. Lower corporate overhead, closer operational focus and a tolerance for modest but predictable returns can make fields viable that a larger company would rank last in its queue. Consolidating operating and non-operating interests in one area also removes partner-level friction from investment decisions. Buyers inherit well integrity, environmental and eventual abandonment obligations, which are normally reflected in the price.
What the Deals Mean for Mendoza and La Pampa
Under Argentina’s legal framework, provinces own the hydrocarbons within their territory and grant the concessions that allow companies to produce them. Provincial governments are therefore direct stakeholders whenever interests change hands, and transfers of concession rights generally require their consent. Royalties from blocks such as these are a recurring line in provincial budgets, which makes production trends a fiscal matter as well as a commercial one.
For Mendoza, a province with a long conventional oil history, the arrival of owners focused on that type of asset can be read as a vote of confidence in fields a larger company had chosen to deprioritise. The local questions are investment, employment and whether output stabilises. La Pampa is affected because part of the acreage crosses into its territory, requiring coordination between two administrations on permitting and royalties.
What to Watch Next
The first checkpoints are procedural: satisfaction of closing conditions, any required provincial and regulatory approvals, and the adjustments that follow from the effective dates. Deals with backdated economics are routinely settled with working-capital and cash-flow true-ups, so the amounts finally exchanged can differ from the headline numbers. Confirmation of completion, rather than announcement, is the point at which a transfer becomes final.
The second question is whether the programme continues. If YPF keeps executing Plan 4×4, further conventional packages could reach the market, and the identity of the buyers will show how deep the pool of interested Argentine operators runs. The third is operational, and it now has two answers rather than one: what Pecom does with roughly 7,000 barrels per day of newly acquired production through San Benito Upstream, and what the Chachahuén buyers do with the 10,000 barrels per day they have taken on.
More: Argentina news in English, every day from The Rio Times.
Frequently Asked Questions
How much is YPF receiving for the two clusters?
The two packages were agreed at a combined US$405 million. The Chachahuén cluster accounts for US$200 million and the ‘Mendoza No Operado’ cluster for US$205 million. Together they represent about 17,000 barrels per day of production. Because the effective dates differ from the closing dates, the amounts finally settled can be adjusted.
Who is buying the assets?
There are two separate buyer groups. The Chachahuén cluster was sold to Energía Mendocina S.A. and Compañía Andina de Petróleo y Gas S.A., companies linked to Grupo Álvarez and Integra Capital. The ‘Mendoza No Operado’ cluster was acquired by San Benito Upstream S.A.U., a company linked to Pecom, the oil business of the Pérez Companc family. Argentine energy trade press, citing Energy Secretariat production filings, reported that Pecom had already become the country’s second-largest conventional crude producer before this deal, after buying the Manantiales Behr area in Chubut for US$410 million.
Why is YPF selling fields that are still producing?
The company has presented the sales as part of Plan 4×4, which involves divesting conventional assets to concentrate investment in the Vaca Muerta shale in Neuquén. Mature conventional fields need continuous maintenance spending simply to hold production roughly flat. Inside a portfolio that also contains shale, capital tends to be directed toward the higher-growth option. Selling raises cash and removes future obligations at the same time.
What is the El Corcobo payment mentioned in coverage of the deal?
Reporting describes the US$205 million as the sum Pecom paid YPF to complete its control of El Corcobo by acquiring the interests it lacked in Malargüe and La Pampa. On that account it is the same US$205 million contained within the US$405 million headline figure. It should not be added to the total as a separate transaction. The overall consideration disclosed for the two clusters remains US$405 million.
Sources: YPF, Infobae, Río Negro.
This article was produced by The Rio Times’ automated AI newsroom. Editorial responsibility: Matthias Camenzind, Publisher and Editor-in-Chief. The Rio Times also runs Ask Rio Times, which answers from 100,000+ of our own articles, the daily Latin America Power Map, and prediction-market odds on elections and markets.. How we use AI · Report an error