Wheat Drops 3.29%; Corn, Soy Slip — the Grains Wrap
Key Facts
- The wheat-tracking fund WEAT lost 3.29%, settling at US$23.81 as Black Sea export jostling and softer export demand clipped appetite.
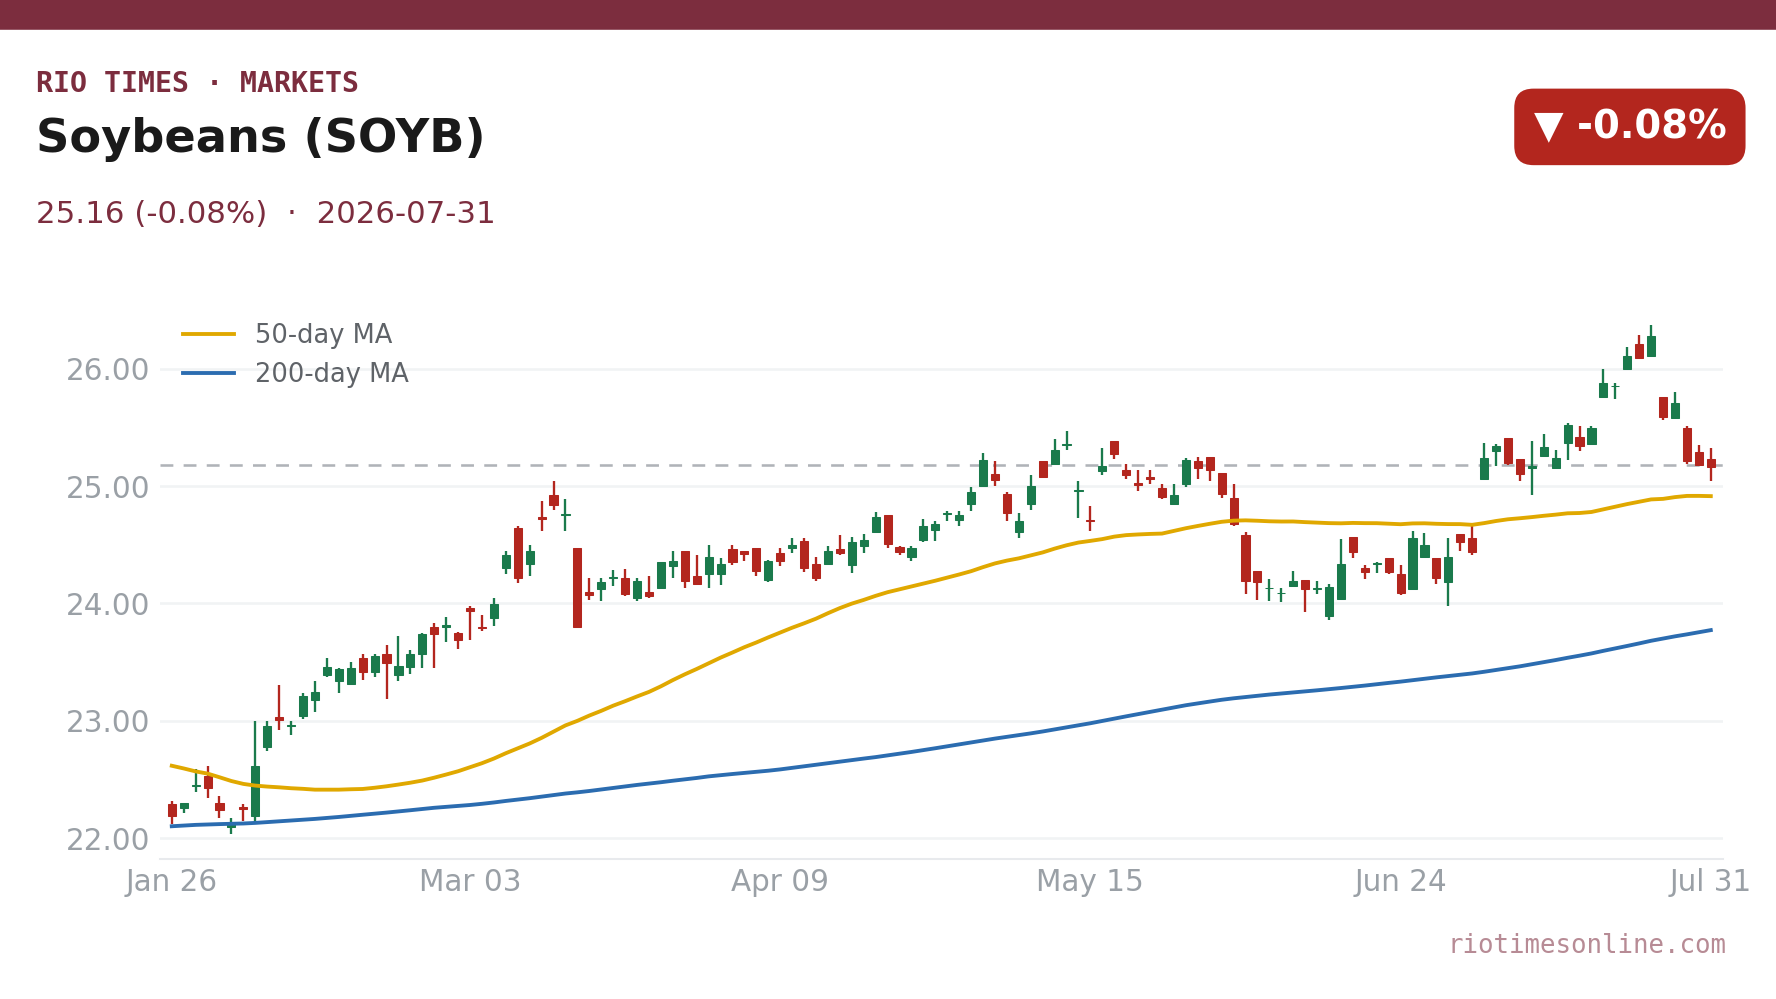
- Soybean proxy SOYB edged 0.08% lower to US$25.16, with the shallow move reflecting a tug-of-war between Brazilian harvest pace and steady Chinese near-term bookings.
- Corn tracker CORN declined 0.62% to US$17.65, pressured by Brazil’s advancing safrinha harvest and a slight easing in Chicago benchmark futures.
- Brazil’s near-record second-crop corn haul is barrelling toward ports at a rapid clip, keeping a physical lid on FOB premiums and pulling the CORN proxy lower in the session.
- Argentina’s peso firmed 0.27% against the dollar, removing one of the usual spurs to the farmer selling that weighs on soybean and corn proxies.
- Chinese importers booked panamax cargoes for August-September soy delivery, though the routine purchases proved insufficient to lift SOYB out of its tight negative range on the day.
Today’s Focus
The grain board finished in the red on Friday, July 31, 2026, with wheat falling hardest. The wheat-tracking fund WEAT sank 3.29% to US$23.81, making it the clear underperformer, while SOYB ticked 0.08% lower to US$25.16 and CORN shed 0.62% to settle at US$17.65.
That wheat rout came as traders fretted over a pop in Black Sea logistics insurance and thinner demand for US cargoes at current price levels. Meanwhile, corn and soy faced a wall of new supply from South America, with Brazilian safrinha corn reaching terminals in vast quantities.
China was present in the soy market, nibbling at fresh cargoes for late-summer delivery, but the flow was too orderly to spark a rally in SOYB. With no fresh trade-distorting headline out of Beijing, the market was content to drift, tracking the real and peso minute by minute.
In a single session, wheat handed back several weeks of slow-won gains, leaving the board with a distinctly defensive posture as traders assess whether this is a one-off flush or the start of a deeper correction tied to currency and shipping costs.
What matters today. The grains complex was softened by South American supply arriving at port in volume, with wheat suffering the sharpest blow — a 3.29% drop in the WEAT proxy — on the cost of moving Black Sea cargoes.
01 The session in one read
Grains investors saw red across the screen on Friday, July 31, 2026, yet the pain was far from uniform. A session earlier the board had looked quite different, with wheat rising while soybeans and corn slipped. While the wheat proxy WEAT plunged 3.29% to US$23.81, the soybean-tracking SOYB almost stood still, giving up just 0.08% to US$25.16, and the corn fund CORN split the difference with a 0.62% slide to US$17.65.
The immediate catalyst for wheat was the cost of war-risk insurance on vessels moving through the greater Black Sea corridor, where additional premiums pushed above 1% of a vessel’s value in late July after Russia and Ukraine escalated attacks on shipping. That freight burden, rather than any move in the US currency, did the damage: the dollar index was easing into month-end, not rising. Soybeans, by contrast, were anchored by the quiet regularity of Chinese forward bookings, which prevented SOYB from following wheat’s steep plunge even as it failed to generate a green number.
The directional story on Friday was a textbook currency-and-supply squeeze. Argentina’s peso firmed 0.27% against the dollar, removing one of the usual prompts for farmers to release stored soybeans and corn. The heavier weight on the board came from South American supply: Brazil’s safrinha corn is reaching terminals in volume, while WEAT stayed fragile on Black Sea freight friction. The variable to watch is Monday’s open in the Buenos Aires peso futures market—if the peso gaps weaker, a fresh wave of farmer selling could push CORN through its near-term support level.
02 The board
The wheat-tracking fund WEAT was the session’s starkest mover, settling at US$23.81, a 3.29% decline that wiped out a fortnight of cautious accumulation. The selling was persistent from the opening print, with no meaningful intraday bounce, suggesting systematic trend-followers were also pressing the short side.
CORN’s drop to US$17.65 was more mechanical: Brazilian growers accelerated deliveries of the freshly cut safrinha crop, creating a physical overhang that discounts the tracker. SOYB’s US$25.16 print, a mere 0.08% lower, was the session’s true outlier, supported by trade reports of continued Chinese buying of August-September arrival slots in the Brazilian port queue.
| Asset | Level | Change |
|---|---|---|
| Soybeans (SOYB) | US$25.16 | -0.08% |
| Corn (CORN) | US$17.65 | -0.62% |
| Wheat (WEAT) | US$23.81 | -3.29% |
Source: RT close, 2026-07-31. Where a commodity has no spot feed, an exchange-traded tracker or leading producer is shown as a labelled proxy.
Live Market IntelligenceThe live market board
Rio Times · Live Market Intelligence
Latin America — Cross-Market Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IBOV | 166,191.45 | -0.82% | +8.41% | 167,563.47 | 168,994 | 166,190 | — |
| IPSA | 10,465.26 | -1.52% | — | 10,627.08 | 10,741 | 10,346 | — |
| IPC MEX | 70,879.44 | +0.08% | +12.14% | 70,819.80 | 71,422 | 70,331 | 182,333,478 |
| MERVAL | 2,848,945 | — | -6.54% | 2,859,051 | — | — | — |
| COLCAP | 2,484.43 | -0.88% | — | — | — | — | — |
| USD/BRL | 5.50 | +0.83% | +2.01% | 5.46 | 5.51 | 5.42 | — |
| EUR/BRL | 6.17 | +0.51% | -0.29% | 6.14 | 6.17 | 6.09 | — |
| USD/MXN | 18.75 | +0.70% | +0.39% | 18.62 | 18.96 | 18.53 | — |
| USD/CLP | 977.94 | +1.18% | +3.33% | 966.50 | 980.85 | 962.10 | — |
| USD/COP | 3,238 | -0.39% | -16.12% | 3,250 | 3,259 | 3,206 | — |
| USD/PEN | 3.44 | -0.12% | +1.92% | 3.44 | 3.45 | 3.44 | — |
| USD/ARS | 1,545 | -0.19% | +5.95% | 1,548 | 1,547 | 1,544 | — |
| USD/UYU | 40.22 | +3.24% | +2.34% | 38.96 | 40.26 | 40.22 | — |
| USD/PYG | 6,358 | +9.88% | -8.84% | 5,787 | 6,358 | 6,031 | — |
| USD/BOB | 11.92 | +1.74% | +76.96% | 11.72 | 12.00 | 11.92 | — |
| USD/DOP | 59.79 | -1.17% | -6.36% | 60.50 | 60.57 | 59.79 | — |
| USD/CRC | 449.63 | +2.27% | -8.17% | 439.66 | 450.45 | 448.95 | — |
| USD/GTQ | 7.64 | +3.16% | +2.02% | 7.41 | 7.64 | 7.64 | — |
03 What moved it
Two forces did most of the work: Black Sea supply-chain friction and a wall of South American supply. Wheat felt the brunt because it carries the most immediate freight-insurance burden for cargoes traversing the Turkish Straits and the shallow-water ports of Ukraine. The usual macro scapegoat was absent — the dollar index finished near 99.8 on Friday, capping its weakest week in three months, so a rising US currency cannot account for the session’s losses.
Argentina, by contrast, was not the source of the pressure this session. The peso firmed against the dollar, and a stronger peso trims rather than boosts the local-currency value of each exported tonne — removing one of the usual prompts for growers to empty silo bags into the Rosario elevators. The weight came from Brazil, where the tail of a very large safrinha corn crop keeps moving to port, adding to the supply pressure that tugged CORN to its US$17.65 close.
04 The Latin American read
For Brazil and Argentina, the board tells a story of volume over price—a strategy that works until buyer appetite dims. Argentina’s farm belt, concentrated in Buenos Aires and Córdoba provinces, kept shipping corn and soy to the port elevators, though a firmer peso worked against the pace: when the currency strengthens, each exported tonne converts into fewer pesos and growers tend to hold. Session-level tonnage is not published in real time, so the flow is better read from weekly export-registration data than from same-day estimates.
Brasília has been building a buffer of its own, committing US$262 million to stockpile corn and rice against El Niño risk. Brazil’s Mato Grosso producers, staring at a bumper corn crop, are selling hand-to-mouth rather than warehousing, reasoning that the real’s slight wobble against the dollar gives them a slim but sufficient margin. This intensity of selling is keeping a hard lid on the CORN proxy, even as Europe’s maize crop looks stressed, and serves as a reminder that Latin America’s output muscle can cap the upside for global grain trackers even when the US currency is easing, as it was into the end of July.
05 The names to watch
Brazilian logistics titan Rumo and Argentine port operator Terminal 6 keep cropping up in sell-side notes as bellwethers for the speed of grain flow. Rumo does not publish weekly throughput, but it does report on a monthly and quarterly cadence, and its record 23.8 billion tonne-kilometres in the second quarter shows how much grain the rail network is now pushing toward Santos. For soy, shares of Brazilian crusher Caramuru Alimentos, while privately held, serve as a proxy for the sector’s margins, which held firm given the steady Chinese bid that kept SOYB nearly flat.
On the buy side, the soybean-tracking fund SOYB’s stability at US$25.16 reflects the market’s expectation that China’s COFCO will not retreat from its forward coverage, even as Brazilian physical premiums stand a touch above the five-year seasonal average. If these routine bookings continue at their current clip, SOYB is the proxy most insulated from the macro crosswinds that hammered WEAT and dragged CORN lower.
06 The outlook
The upcoming week hinges on whether the dollar steadies after drifting lower through late July; a renewed rise in the DXY would drag all three grain proxies lower in lockstep. Currency traders will also watch Buenos Aires, where a firmer peso reduces the incentive for the farmer selling that has been a reliable bearish driver for CORN. Energy costs feed the same freight equation, and the same-session oil wrap showed crude proxies holding firm. For wheat, the signal to monitor is the marine-insurance market: if underwriters keep ratcheting war-risk premiums for Black Sea hulls, WEAT could test another leg down, even with global wheat stocks tightening outside China.
07 What to watch
- Peso parallel rate: If Argentina’s unofficial dollar rate strengthens by the Monday fix, farmer selling may slow and provide some reprieve for CORN.
- Black Sea vessel insurance: Any sign that war-risk premiums on bulk carriers are levelling off could trigger a sharp snapback rally in WEAT.
- Rumo rail volumes: Weekly corn and soy throughput data from Rumo will signal whether the Brazilian export flood is peaking or still building.
- China October coverage: Crusher margin spreads in Dalian will indicate whether COFCO extends its forward buying, keeping SOYB anchored near US$25.16.
Frequently Asked Questions
Why did wheat fall 3.29% on 31 July 2026 when corn and soybeans barely moved?
The wheat tracker WEAT fell from US$24.62 to US$23.81 because Black Sea freight costs bit hardest. Additional war-risk premiums for the region climbed above 1% of a vessel’s value in late July after Russia and Ukraine escalated attacks on shipping, lifting the delivered cost of cargoes. Corn and soybeans travel different trade routes and were largely spared.
Did a stronger US dollar cause the sell-off in grains?
No. The dollar index closed near 99.8 on 31 July 2026, capping its weakest week in three months and down roughly 1.6% over the month. Every major Latin American currency firmed against it that day. The pressure on the grains board came from Black Sea shipping costs and South American supply reaching port, not from currency strength.
How does a firmer Argentine peso affect corn and soybean selling?
It slows it. Argentine growers are paid in pesos for dollar-priced grain, so a stronger peso means each exported tonne converts into fewer pesos. That trims the incentive to empty silo bags. The peso firmed against the dollar on 31 July 2026, removing one of the usual prompts for the farmer selling that weighs on CORN and SOYB.
What are WEAT, CORN and SOYB, and why does The Rio Times quote them?
They are Teucrium exchange-traded funds that hold Chicago futures contracts in wheat, corn and soybeans. Where no clean spot feed exists for a commodity, we quote a listed tracker as a labelled proxy so readers see a real, dated closing price. They follow the underlying futures curve but are not identical to cash grain prices.
Sources: Teucrium, The Insurer, Conab
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.