Argentina · Economy
Key Facts
- —What happened Martín Redrado backed Milei’s BCRA charter rewrite, calling it a fix for past mismanagement.
- —How big a jump The reform would make preserving the peso the bank’s sole job, banning Treasury financing and money-printing.
- —The real story Redrado warned 2027 brings ‘tension’ as Argentines shift to dollars, with about US$2.5 billion outflowing monthly.
- —The catch Congress hasn’t approved the bill; Redrado also requested an unspecified ‘cerrojo’ on central bank reserves.
- —Who it touches Argentine savers, investors, and expats face peso pressure; regional central banks watch if reform boosts credibility.
- —What comes next Investors await the economic team’s dollar-outflow plan, eyeing reform passage and the bank’s rule adherence.
Former central bank chief supports Milei’s bill to end Treasury financing, but says dollar-saving will test the economy next year.
Martín Redrado, a former central bank governor, has backed the government’s plan to rewrite the BCRA charter. He also warned that 2027 will bring pressure as Argentines move savings into dollars.
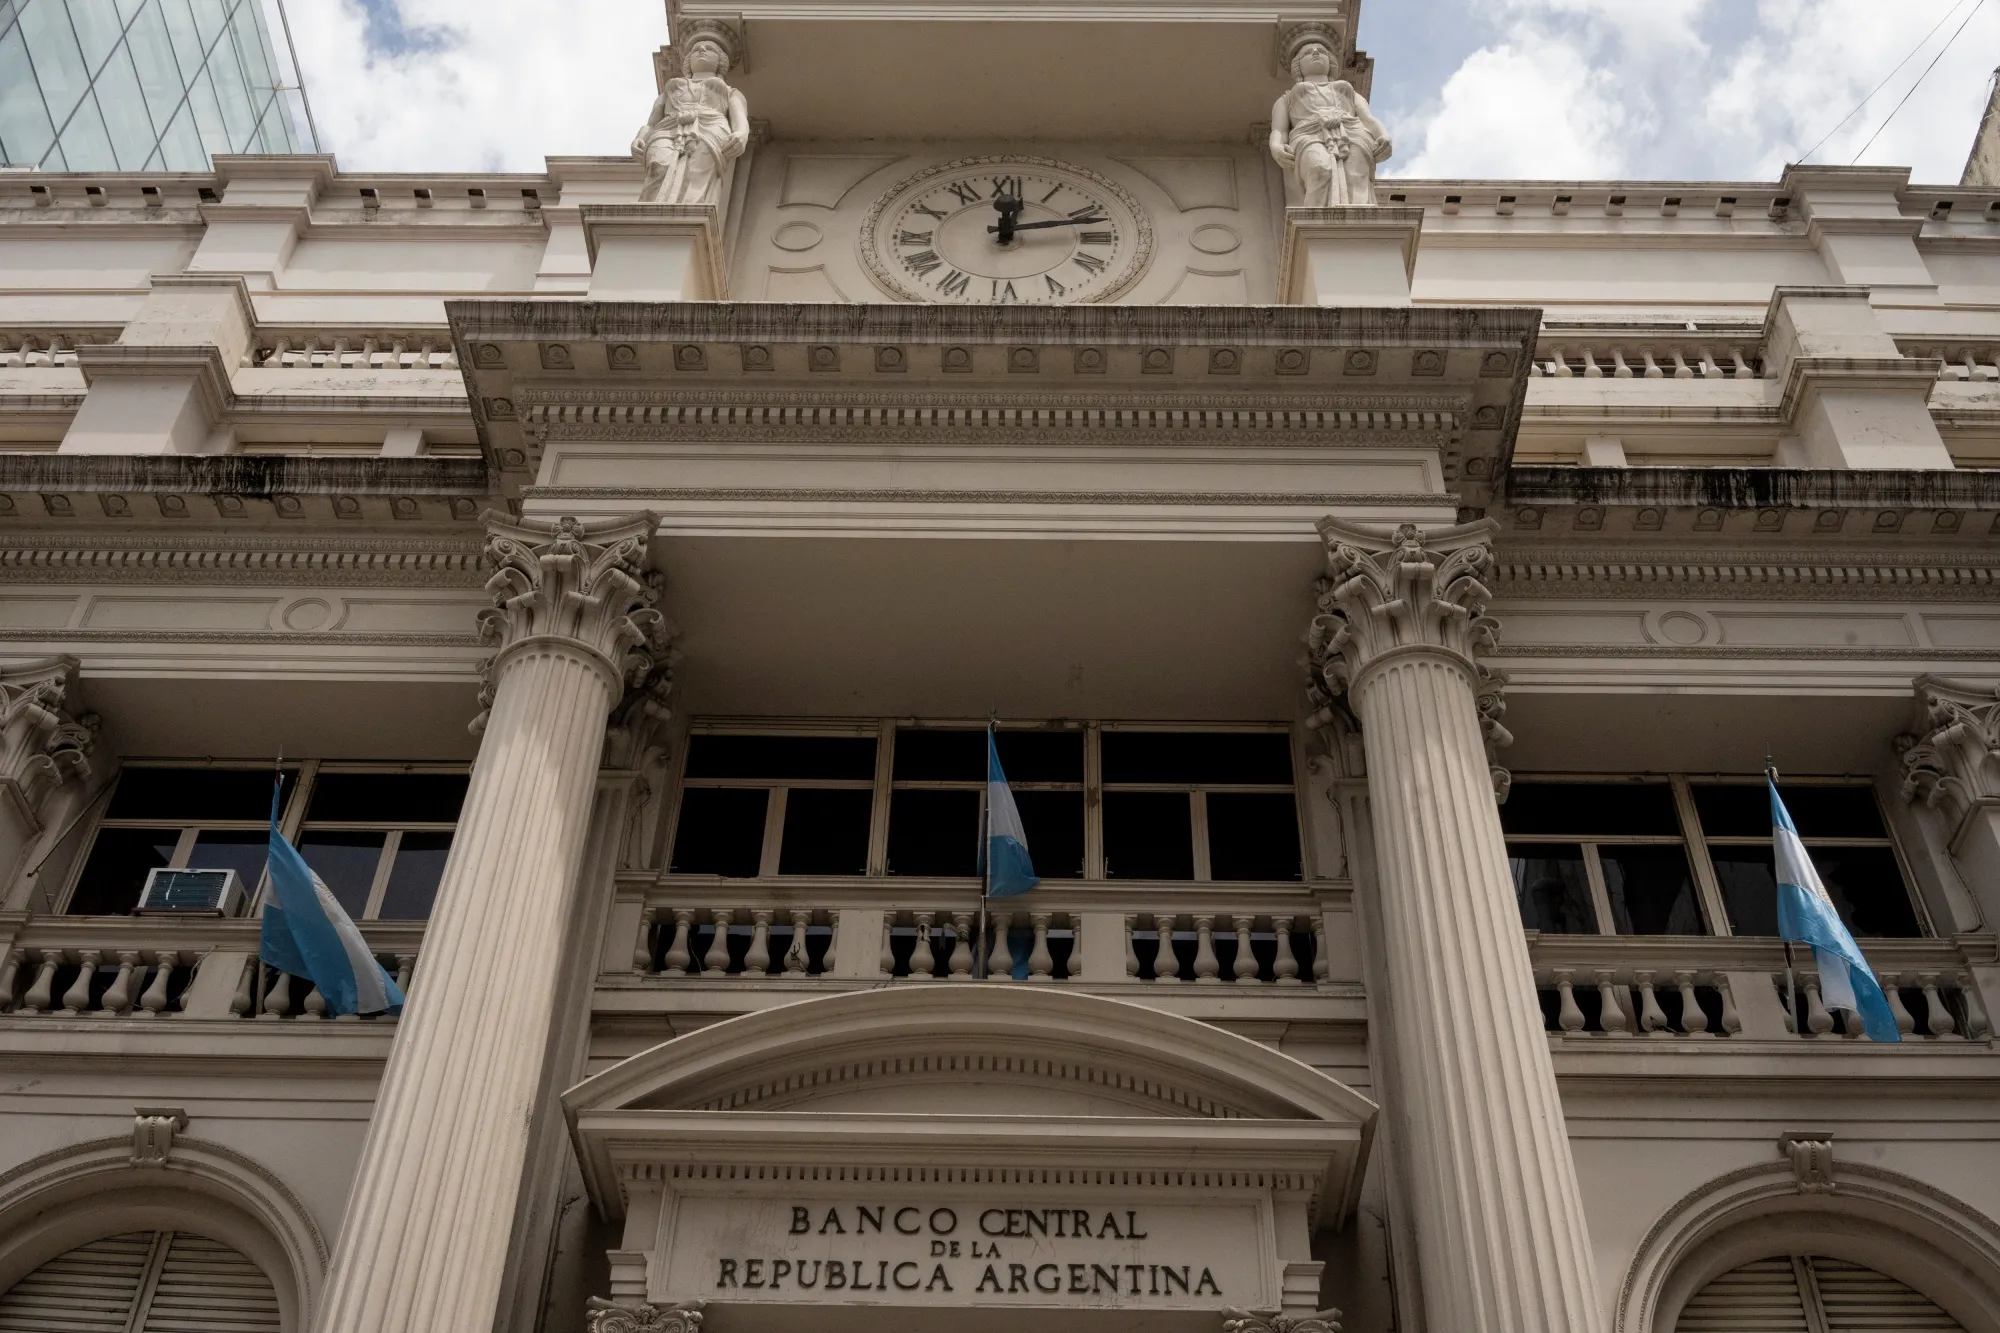
Redrado’s double message
Martín Redrado, who led the central bank from 2004 to 2010, gave his support to the reform. He described it as a fix for past mismanagement.
‘The central bank reform comes to resolve the mess made in 2010,’ he said on TN on 13 August 2026. He did not criticise the bill.
In fact, he framed it as a necessary correction to the ‘zafarrancho’—that’s a Spanish word for a chaotic scramble—that followed the 2010 changes.
But he also raised a red flag about the near future. ‘There is dollarization of portfolios, 2,500 million dollars per month leave in travel and savings,’ he said. That’s around US$2.5 billion a month flowing out of the country as people park money in dollars, either for trips abroad or as a store of value.
He added a direct warning: ‘Next year there will be tension, but I see the economic team preparing.’ That tension, he explained, comes from Argentines moving savings into dollars. It’s a pattern that has historically put pressure on the peso and on the central bank’s ability to defend it.
What the charter reform does
The bill rewrites the charter of the BCRA, Argentina’s central bank. Its main goal is to make preserving the value of the currency the bank’s single mandate.
That means inflation control becomes the one clear objective, replacing the multiple goals that previously muddied the bank’s mission.
The reform would ban the central bank from financing the Treasury. That means no temporary advances, no loans to the public sector, and no direct purchases of government paper in the primary market.
In plain terms, the government could no longer lean on the central bank to print money or use reserves to fund its spending.
It would also make the bank more independent. The grounds and majorities needed to remove central bank authorities would be stricter.
That’s a big change, as it would make it harder for any future government to fire the governor or board members for political reasons.
Profit distribution would be limited to real and liquid gains. The government also wants to close the mechanism of non-transferable letters, which it used to finance the Treasury with reserves.
Additionally, there’s a technical tweak: the cash that banks hold in their own vaults would now count toward their mandatory reserve requirements, a small adjustment that could free up a bit of liquidity for the banking system.
The ‘cerrojo’ request
On 14 August 2026, Redrado spoke again on the program Modo Fontevecchia, broadcast by +Perfil and Radio Perfil. He said the bill is a step forward.
That’s a clear endorsement, not a rejection.
But he asked to ‘close the lock’ on the central bank’s pesos and dollars. That means restricting how the bank can use its own funds.
He wants to ensure that the bank’s resources aren’t used loosely, which could undermine the reform’s credibility.
Redrado did not specify exactly what rules he wants. His point was that the bank should not have discretion to use its reserves freely.
He’s essentially asking for even clearer guardrails to prevent any future backsliding.
His comment fits with his earlier warning about dollarization. If people keep moving money into dollars, the central bank will face more pressure.
A strict ‘cerrojo’ on the bank’s own funds would sign to markets that the bank’s resources are safe from political meddling.
Why 2027 could be a test
Redrado’s warning focuses on next year. He said ‘there will be tension’ without giving details.
But the context is clear: dollarization pressures aren’t going away overnight.
The tension is likely to come from capital flight. He said 2,500 million dollars per month leave Argentina for travel and savings.
That’s a huge drain on reserves, especially for a country that has struggled to rebuild its buffer.
That is a large amount for a country with limited reserves. The central bank may have to defend the peso, which could be costly.
If people keep converting pesos to dollars, the bank will have to sell dollars from its reserves to keep the peso stable, and that could eat into its savings.
Redrado said the economic team is preparing. But he did not say what measures they are taking.
Investors will be watching closely for any signs of a plan to manage the outflow, whether that’s tighter capital controls, a faster disinflation push, or something else entirely.
Why this matters for the region
Argentina’s central bank reform is being watched across Latin America. Other countries also struggle with inflation and weak currencies.
From Brazil to Chile, central banks have fought hard to keep inflation in check, and they know how hard it is when governments try to lean on the monetary authority.
If the reform passes, it could set an example. A central bank that cannot finance the government is often seen as more credible.
That credibility can help lower inflation expectations, which in turn can make it easier to keep prices stable without having to slam the brakes on the economy.
But the dollarization warning is a reminder of the risks. When people lose confidence in a currency, they move to dollars, which can worsen the problem.
It’s a vicious circle: the more people flee the peso, the weaker it gets, and the more they want to flee.
For investors and expats in Argentina, this means watching both the law and the exchange rate. The peso’s value will depend on how the bank handles the pressure.
If the reform passes and the bank sticks to its new rules, that could be a positive sign. But if the tension Redrado predicts turns into a full-blown crisis, even the best charter might not be enough to steady the ship.
Frequently Asked Questions
What is the BCRA charter reform?
It is a bill proposed by President Milei’s government to change the rules of Argentina’s central bank. The bill would make preserving the currency’s value the bank’s only goal and ban it from financing the Treasury.
What did Martín Redrado say about the reform?
He supported it, saying it resolves the ’mess made in 2010.’ But he also warned that 2027 will bring tension because Argentines are moving savings into dollars.
Has the reform been approved?
No. It is still a bill. It has not been passed by Congress.
Who is the current central bank governor?
Santiago Bausili. Martín Redrado is a former governor, not the current one.
Connected Coverage
Milei’s Reform Package Heads to Congress as Argentina Lifts Its Dollar Ceiling
Argentina Pushes Central Bank Reform Toward August 19 Vote
Milei’s Central-Bank Reform Would Ban Argentina’s Money-Printing
Sources: tn.com.ar; perfil.com; youtube.com; multimediosprisma.com; losandes.com.ar
In depth
This article was produced by The Rio Times’ automated AI newsroom. Editorial responsibility: Matthias Camenzind, Publisher and Editor-in-Chief. The Rio Times also runs Ask Rio Times, which answers from 100,000+ of our own articles, the daily Latin America Power Map, and prediction-market odds on elections and markets.. How we use AI · Report an error