Dow Jumps 3% as Gold Tops US$4,000 and Fear Fades | Global Economy, Nov 5
Rio Times Global Economy Briefing
The Big Three
- Wall Street rallies hard The Dow Jones Industrial Average closed at 53,356, up 3.03%, and the VIX fell 20.26% to 16.61. Fear drained out of the market.
- Rates relief lifts gold The US 10-year yield eased to 4.889% and the dollar index to 101.262. Gold jumped 3.23% to $4,066 an ounce.
- Central banks and payrolls loom The Bank of England and Brazil’s Copom are in focus today, and US payrolls follow on Friday. Each could reset the rate path.
United States
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| EIA commercial crude stocks (week to 30 Oct) | 409.8m bbl | n/a (-0.9m change) | Small draw |
| EIA distillate stocks | 99.3m bbl | -3.6m change | Sharpest draw in report |
| Non-farm payrolls (Fri, consensus 65k) | Due Friday | 29k | Key test for the Fed |
| Unemployment rate (Fri, consensus 4.2%) | Due Friday | 4.2% | Steady expected |
| Michigan sentiment (Fri, consensus 48) | Due Friday | 48 | Flat expected |
Europe & United Kingdom
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| Bank of England Bank Rate (12:00 UK) | Due today | 3.75% | Hike to 4% is live |
| BoE September vote | n/a | 6-3 to hold | Three wanted 4% |
| BoE inflation risk assessment | Tilted to the upside | n/a | Hawkish lean |
Asia-Pacific & Emerging Markets
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| China PMI (Oct, consensus 52.2) | 52 | 52.4 | Slight miss |
| China S&P Global Services PMI (Oct, consensus 51.5) | 50.8 | 51.6 | Miss, cooling |
| Morocco unemployment (Q3, consensus 12%) | 10.5% | 9.5% | Better than forecast |
| Brazil industrial production (Thu, consensus -0.2) | Due today | -0.6 | Contraction easing? |
| Brazil composite PMI (Thu, consensus 46.9) | Due today | 47.4 | Still contraction |
| Mexico interest rate decision (Thu) | Due today | 6.5% | Banxico on hold or cut |
| Instrument | Level | Session |
|---|---|---|
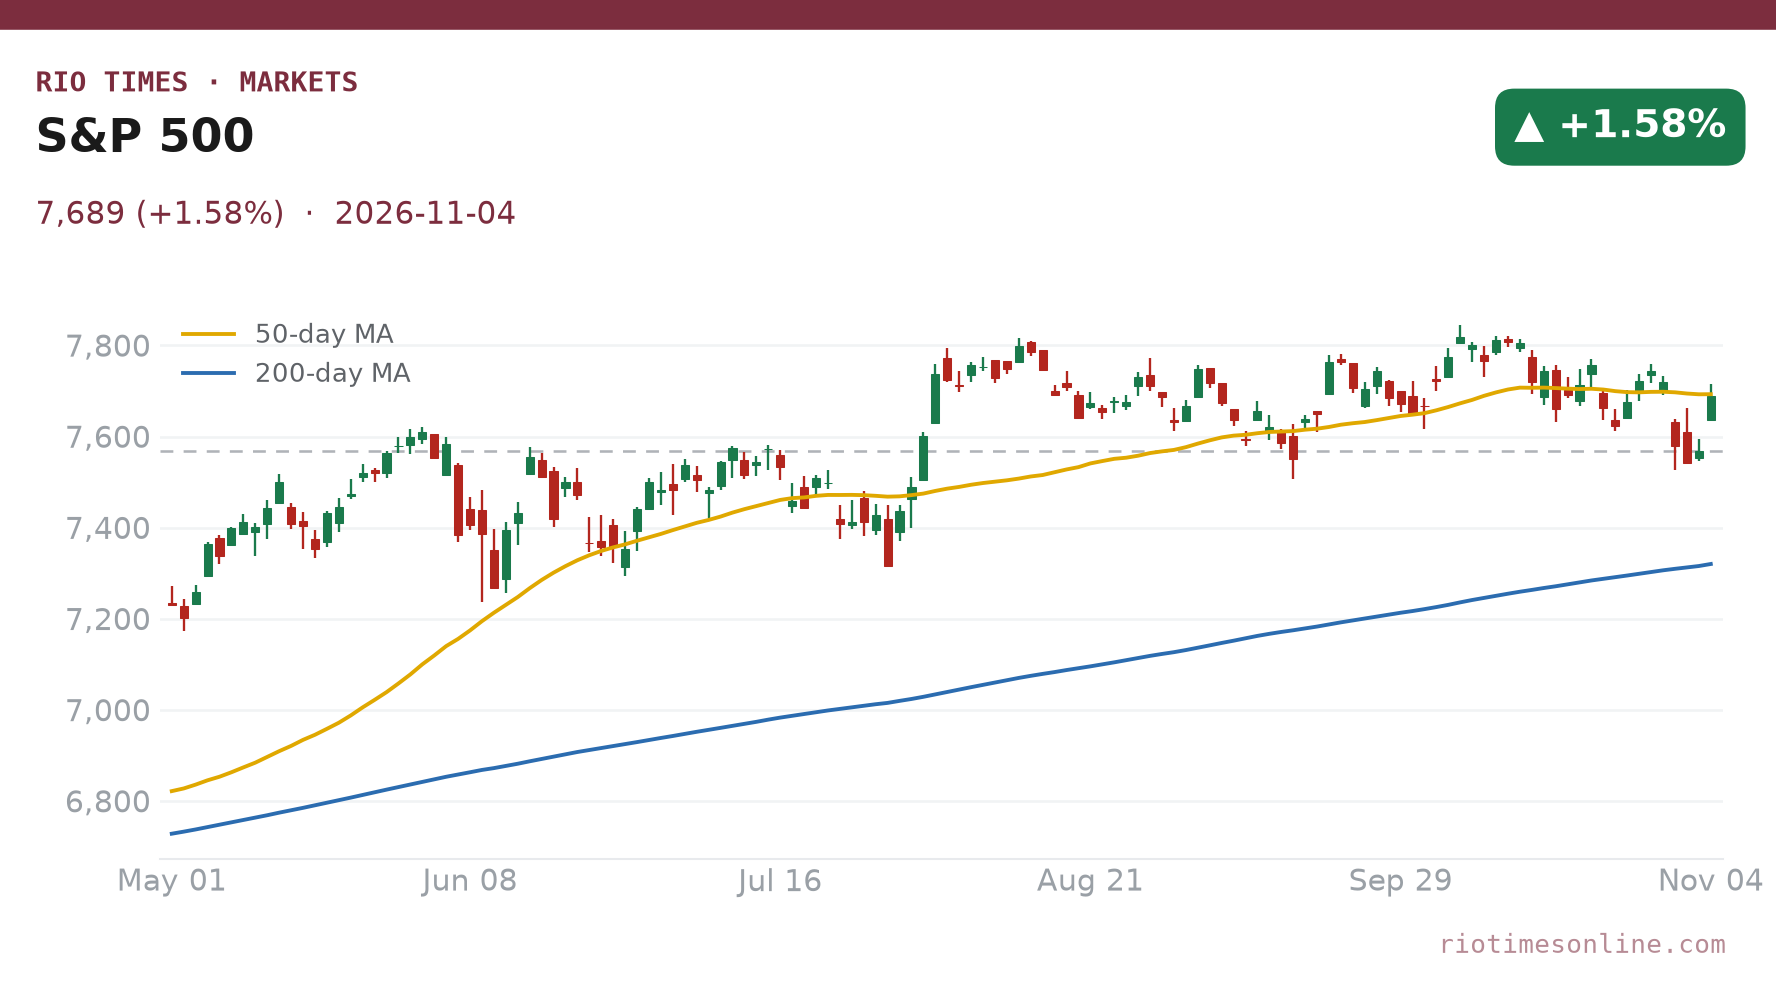
| S&P 500 (US) | 7,689 | +1.58% |
| Ibovespa (Brazil) | 167,563 | +1.23% |
| USD/BRL | 5.4592 | -0.56% |
Source: market close, 4 November 2026.
Today’s Economic Calendar — Thursday, November 5, 2026
| Time | Country | Event | Consensus | Prior |
|---|---|---|---|---|
| 03:35 | JP | 10-Year JGB Auction | — | 3.101 |
| 07:00 | DE | Factory Orders | 4.8 | -10.6 |
| 08:30 | DE | S&P Global Construction PMI | 44 | 43.5 |
| 10:00 | MX | Foreign Exchange Reserves | 254 | 255.95 |
| 10:30 | US | Challenger Job Cuts | 51 | 43.281 |
| 11:00 | DE | New Car Sales | 4.5 | 9 |
| 12:00 | BR | Industrial Production | -0.2 | -0.6 |
| 12:00 | BR | Industrial Production | -1.7 | -1.2 |
| 12:00 | MX | Gross Fixed Investment | -0.6 | 1.4 |
| 12:00 | MX | Gross Fixed Investment | 6.5 | 6.6 |
| 13:00 | BR | S&P Global Services PMI | 48.7 | 49.2 |
| 13:00 | BR | S&P Global Composite PMI | 46.9 | 47.4 |
| 13:30 | US | Nonfarm Productivity | 2.5 | 1.4 |
| 13:30 | US | Continuing Jobless Claims | 1710 | 1701 |
| 13:30 | US | Jobless Claims 4-Week Average | 196 | 196.75 |
| 13:30 | US | Unit Labour Costs | 0.7 | 1.2 |
| 13:30 | US | Initial Jobless Claims | 196 | 194 |
| 13:50 | US | Fed Hammack Speech | — | — |
Live Market IntelligenceGlobal Markets — Live Board
Rio Times · Live Market Intelligence
Global Markets — Live Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| SPX | 7,722 | +0.59% | — | — | — | — | — |
| NDX | 29,646 | +1.27% | — | — | — | — | — |
| DJI | 52,367 | +0.01% | — | — | — | — | — |
| RUT | 2,814 | +0.97% | — | — | — | — | — |
| US10Y | 4.9950 | +0.18% | — | — | — | — | — |
| VIX | 17.75 | -3.48% | — | — | — | — | — |
| DAX | 25,591 | +0.71% | — | — | — | — | — |
| FTSE | 10,687 | -0.75% | — | — | — | — | — |
| CAC | 7,887 | +0.51% | — | — | — | — | — |
| STOXX | 643.68 | +0.47% | — | — | — | — | — |
| NIKKEI | 63,268 | +1.73% | — | — | — | — | — |
| HSI | 23,041 | -0.23% | — | — | — | — | — |
| KOSPI | 5,638 | +3.09% | — | — | — | — | — |
| CSI300 | 4,050 | -1.32% | — | — | — | — | — |
| NIFTY | 22,750 | +0.66% | — | — | — | — | — |
| TSX | 36,123 | +0.50% | — | — | — | — | — |
| GOLD | 4,073 | +0.85% | +1.32% | 4,038 | 4,079 | 4,002 | 117,083 |
| SILVER | 54.49 | +0.70% | +17.02% | 54.11 | 54.64 | 52.71 | 34,428 |
01 Fear drains out of Wall Street
Wall Street rallied hard. The Dow Jones Industrial Average closed at 53,356, up 3.03%, while the S&P 500 rose 1.58% to 7,689 and the Nasdaq Composite gained 1.44% to 25,737.
Fear left the market. The VIX fell 20.26% to 16.61, a level that signals little panic.
The Dow outran the Nasdaq by a wide margin. That points to investors buying broad, older-economy companies rather than chasing technology alone, which is how a relief rally looks.
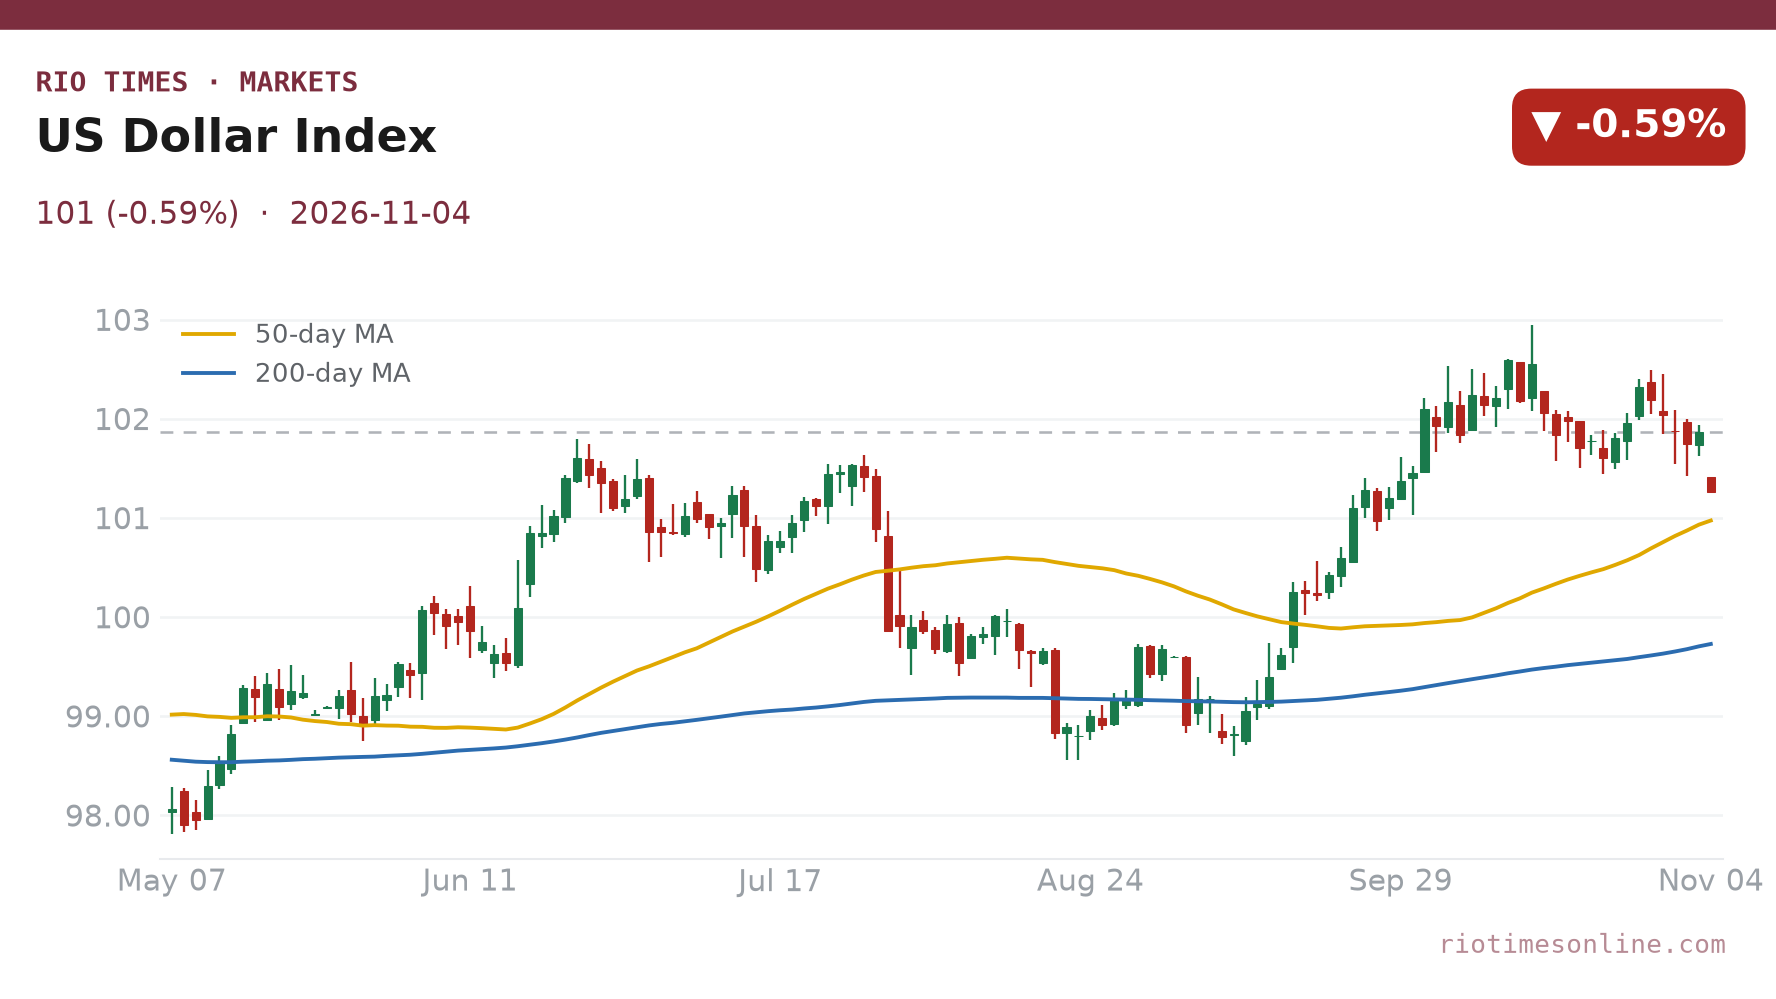
The same pattern shows in other assets. The US 10-year Treasury yield eased 1.71% to 4.889%, the dollar index slipped 0.59% to 101.262, and gold jumped 3.23% to US$4,066 an ounce.
The US Energy Information Administration’s weekly report (eia.gov) showed commercial crude stocks at 409.8 million barrels, down 0.9 million. Distillate fuel stocks fell 3.6 million barrels to 99.3 million, the sharpest draw in the report.
Other Wednesday data pointed to a cooling but firm US economy. The Institute for Supply Management (ISM) services index, a survey of US service firms, slipped to 54.5 from 54.9 against a 54.8 forecast, with new orders at 55.9 (59.8 before), business activity at 53.8 (56.5) and employment at 51.4 (50.1 before).
ADP, the payroll processor, counted 86,000 private jobs added in October against a 69,000 forecast and 90,000 before. The US trade deficit narrowed to US$105.0 billion in September from US$105.7 billion, against a forecast of US$108 billion.
In Europe, euro-area inflation (the flash estimate for the harmonised index) rose to 4.0% in October from 3.8%, with core inflation steady at 2.5% as energy prices pushed higher. In Latin America, Brazil’s Caged report, the labour ministry’s formal-jobs count, showed 121,300 net jobs in September against 171,000 expected and 165,830 before, the weakest September since 2020.
São Paulo’s IPC-Fipe consumer price index rose 0.44% in October from 0.51% in September, against a 0.7% forecast, and Mexico’s consumer confidence reading (forecast 45, previous 45.1) was not confirmed from INEGI, the statistics office, when we wrote this. The weekly US Energy Information Administration report also tracks crude at the Cushing, Oklahoma, hub (previous change -0.6 million barrels); the latest Cushing figure was not available to us.
02 Friday’s payrolls decide the Fed’s next move
The Federal Reserve held its target range at 3.75% to 4.00% on 28 October in a 10-2 vote, according to its statement. Governor Lisa Cook and Cleveland Fed president Beth Hammack dissented in favour of a quarter-point rise.
Futures markets now lean towards a December hike. A 10-year yield near 4.9% fits a market that still fears the next move is up, not down.
Friday’s jobs report is the test. Consensus is for 65,000 new jobs against 29,000 before, with unemployment steady at 4.2%.
Average hourly earnings are expected to rise 0.3% on the month, after 0.1%. A hot print would revive the hike case, while a miss would feed the rally.
03 London, Brasília and the dollar’s grip on Latin America
The Bank of England decides at 12:00 UK time today. Bank Rate is 3.75% after a 6-3 vote in September, with three members wanting 4%, and calendar forecasts point to a rise.
China offered a softer signal. Its October PMI came in at 52 against 52.2 expected, and the S&P Global services gauge fell to 50.8 against 51.5 expected.
For Brazil, a softer dollar and lower Treasury yields ease pressure on the real. They also give the central bank more room to cut.
Brazil’s Copom, the central bank’s rate-setting committee, held the Selic, its benchmark rate, at 13.75% on Wednesday in a unanimous vote. That ended five cuts in a row, so the question now is when cuts resume.
Brazil’s data is weak today. The composite PMI is expected at 46.9 against 47.4, and anything below 50 signals contraction.
Mexico’s central bank also decides today, with its rate at 6.5%. Both Latin American giants are cutting or pausing while the US debates a hike, and that gap makes a calm dollar essential.
What to watch today and this week
- Thursday: Bank of England decision at 12:00 UK; Banxico decision (prior 6.5%); Brazil industrial production (consensus -0.2) and PMIs.
- Friday: US payrolls (consensus 65k, prior 29k), unemployment 4.2%, earnings 0.3%; Michigan sentiment 48; Fed speakers Musalem and Bowman; Brazil trade balance (consensus 9, prior 7.74).
- Next week: Chile inflation on Friday (consensus 0.6% monthly); Colombia producer prices; Argentina industrial production (consensus -1%).
- Ongoing: December Fed hike pricing, Ueda’s remarks on the yen, and the dollar’s path against the real.
Frequently Asked Questions
How did US stocks close on 4 November 2026?
The Dow Jones closed at 53,356, up 3.03%. The S&P 500 rose 1.58% to 7,689 and the Nasdaq Composite gained 1.44% to 25,737.
Why did gold jump?
Gold rose 3.23% to US$4,066 an ounce as the 10-year yield eased to 4.889% and the dollar index fell to 101.262. Lower yields make non-yielding gold more attractive.
What is the Bank of England expected to do today?
It decides at 12:00 UK time. Bank Rate is 3.75% and calendar forecasts point to a rise to 4%, after three members voted for that in September.
What does this mean for Brazil?
A weaker dollar and lower US yields support the real and the case for Selic cuts. Copom held the Selic at 13.75% on 4 November, ending five straight cuts, so the focus is on when cuts resume.
What is the key data point this week?
US non-farm payrolls on Friday, with consensus at 65,000 jobs against 29,000 before. The result shapes expectations for the Fed’s December meeting.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.