Fed Hike Bets Lift US Yields, Nasdaq Gains 0.8% | Global Economy, Nov 4
Rio Times Global Economy Briefing
The Big Three
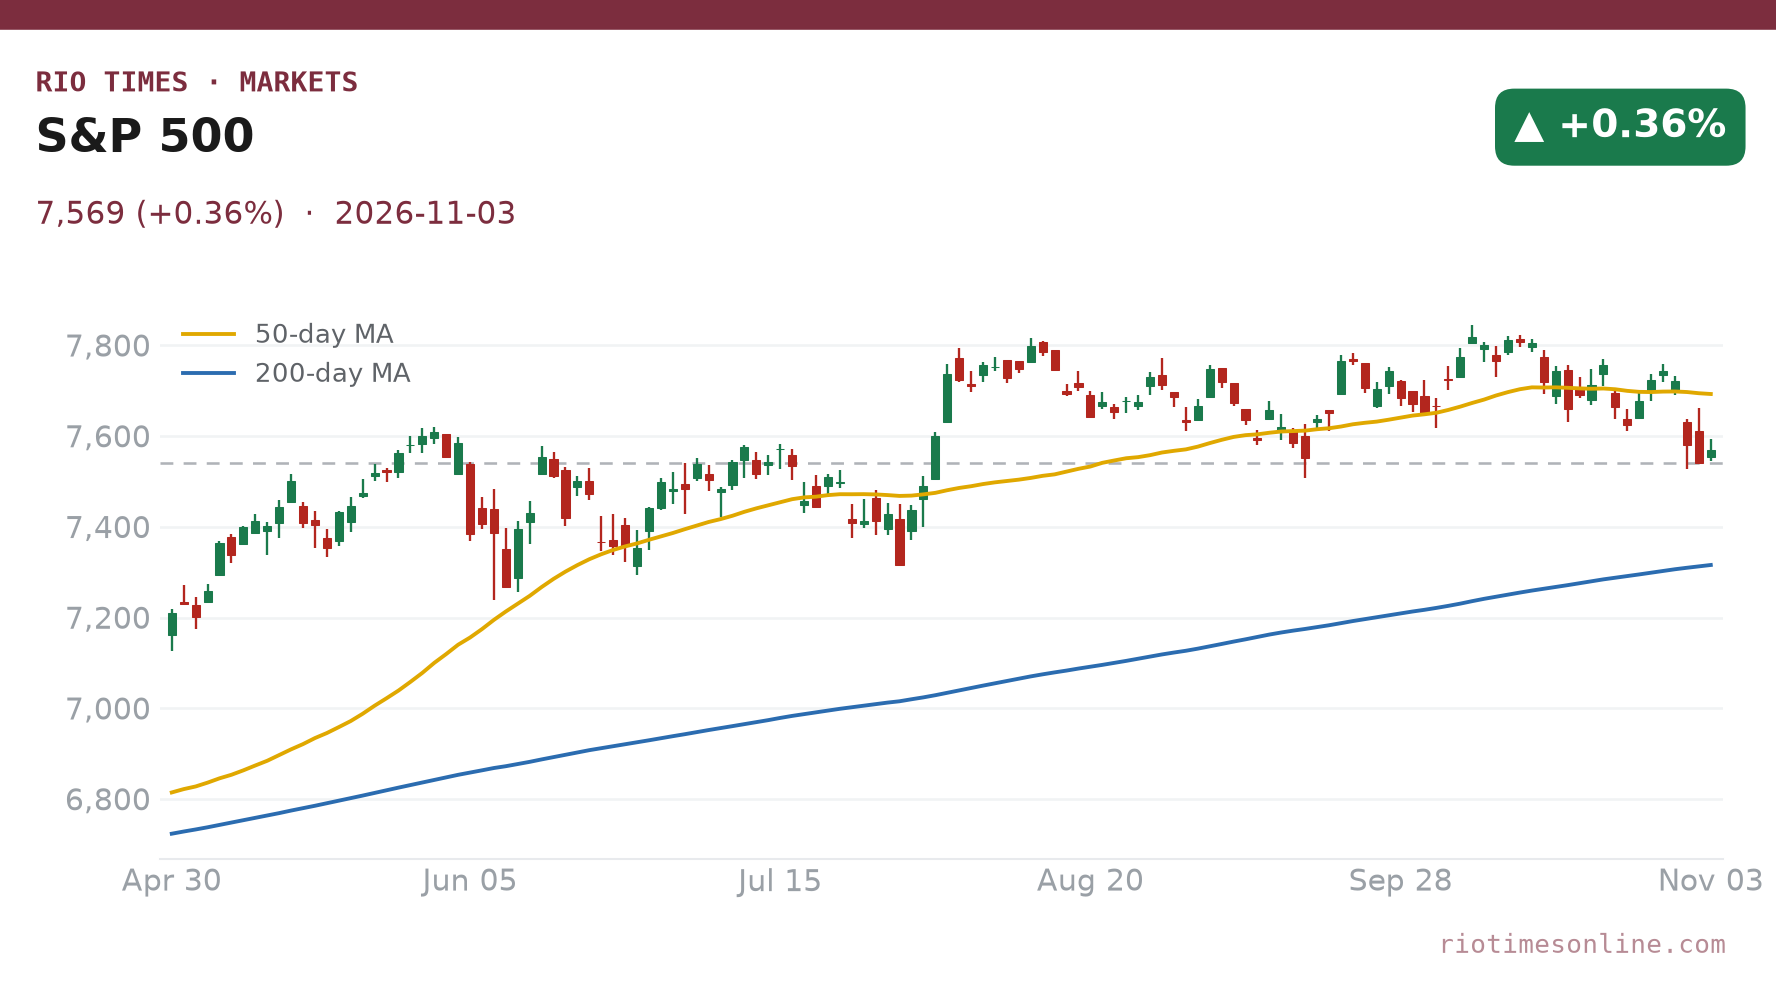
- Wall Street splits, with tech in front. The Nasdaq Composite rose 0.83% to 25,372 and the S&P 500 gained 0.36% to 7,569. The Dow Jones fell 0.38% to 51,787, so the rally was narrow.
- The 10-year Treasury yield sits at 4.974%, up 6.5 basis points (a basis point is one-hundredth of a percentage point). Polymarket bettors give a 74.5% chance of a Fed rate rise on 9 December. That keeps borrowing costs high for every emerging market.
- Brazil’s Copom decides on the Selic tonight. The calendar consensus is a hold at 13.75%, with a cut still debated. The decision lands against a weaker dollar index of 101.39 and a US 10-year yield of 4.974%.
United States
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| EIA commercial crude stocks (week to 23 Oct) | 410.6m barrels (-1.9m) | n/a | Draw supports crude |
| EIA gasoline stocks (week to 23 Oct) | 209.2m barrels (+3.9m) | n/a | Build hints at soft demand |
| EIA distillate stocks (week to 23 Oct) | 102.8m barrels (-1.5m) | n/a | Draw tightens diesel |
| Initial jobless claims (Thu) | Due; consensus 195k | 194k | Watch for labour cracks |
| Nonfarm productivity (Thu) | Due; consensus 2.5% | 1.4% | Fed cost-pressure gauge |
Europe & United Kingdom
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| German factory orders (Thu) | Due; consensus 4% | -10.6% | Rebound expected after a slump |
| German construction PMI (Thu) | Due; consensus 44 | 43.5 | Still in contraction |
| German new car sales (Thu) | Due; consensus 4.5% | 9% | Slower growth expected |
| Bank of England decision (Thu) | Due | n/a | Key for sterling |
| Bundesbank’s Nagel speaks (Thu) | Due | n/a | Tone on ECB policy |
Asia-Pacific & Emerging Markets
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| Egypt composite PMI (Oct) | 47.2 (consensus 48) | 47.2 | Miss; activity still shrinking |
| Mexico fiscal balance (Sep) | -222.34 | -737.3 | Deficit narrows sharply |
| Brazil Selic decision (Wed) | Due; consensus 13.75% | 13.75% | Hold expected |
| Brazil composite PMI (Thu) | Due; consensus 46.9 | 47.4 | Contraction seen |
| Brazil industrial production (Thu) | Due; consensus -1.7% | -1.2% | Factory weakness |
| Japan average cash earnings (Thu) | Due; consensus 3.8% | 3.8% | Wage growth steady |
| Instrument | Level | Session |
|---|---|---|
| S&P 500 (US) | 7,569 | +0.36% |
| Ibovespa (Brazil) | 165,529 | -1.42% |
| USD/BRL | 5.49 | +0.97% |
Source: market close, 3 November 2026.
Today’s Economic Calendar — Wednesday, November 4, 2026
| Time | Country | Event | Consensus | Prior |
|---|---|---|---|---|
| 01:45 | CN | PMI | 52.2 | 52.4 |
| 01:45 | CN | S&P Global Services PMI | 51.5 | 51.6 |
| 08:00 | BR | IPC-Fipe Inflation | 0.7 | 0.51 |
| 10:30 | DE | 30-Year Bund Auction | — | 3.8 |
| 10:30 | DE | 15-Year Bund Auction | — | 3.5 |
| 11:30 | CL | Monetary Policy Meeting Minutes | — | — |
| 12:00 | US | MBA Mortgage Applications | — | 3.4 |
| 12:00 | US | MBA Mortgage Market Index | — | 195 |
| 12:00 | US | MBA 30-Year Mortgage Rate | — | 7.37 |
| 12:00 | US | MBA Mortgage Refinance Index | — | 516.8 |
| 12:00 | US | MBA Purchase Index | — | 134.1 |
| 12:00 | MX | Consumer Confidence | 45 | 45.1 |
| 12:00 | MX | Consumer Confidence n.s.a | — | 45.2 |
| 13:15 | US | ADP Employment Change | 65 | 90 |
| 13:30 | US | Treasury Refunding Announcement | — | — |
| 13:30 | US | Balance of Trade | -108 | -105.6 |
| 13:30 | US | Imports | 429.1 | 420.8 |
| 13:30 | US | Exports | 320.3 | 315.2 |
Live Market IntelligenceGlobal Markets — Live Board
Rio Times · Live Market Intelligence
Global Markets — Live Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| SPX | 7,722 | +0.59% | — | — | — | — | — |
| NDX | 29,646 | +1.27% | — | — | — | — | — |
| DJI | 52,367 | +0.01% | — | — | — | — | — |
| RUT | 2,814 | +0.97% | — | — | — | — | — |
| US10Y | 4.9950 | +0.18% | — | — | — | — | — |
| VIX | 17.75 | -3.48% | — | — | — | — | — |
| DAX | 25,591 | +0.71% | — | — | — | — | — |
| FTSE | 10,687 | -0.75% | — | — | — | — | — |
| CAC | 7,887 | +0.51% | — | — | — | — | — |
| STOXX | 643.68 | +0.47% | — | — | — | — | — |
| NIKKEI | 63,268 | +1.73% | — | — | — | — | — |
| HSI | 23,041 | -0.23% | — | — | — | — | — |
| KOSPI | 5,638 | +3.09% | — | — | — | — | — |
| CSI300 | 4,050 | -1.32% | — | — | — | — | — |
| NIFTY | 22,750 | +0.66% | — | — | — | — | — |
| TSX | 36,123 | +0.50% | — | — | — | — | — |
| GOLD | 4,073 | +0.85% | +1.32% | 4,038 | 4,079 | 4,002 | 117,083 |
| SILVER | 54.49 | +0.70% | +17.02% | 54.11 | 54.64 | 52.71 | 34,428 |
01 A rally with one foot on the brake
Wall Street ended mixed. The Nasdaq Composite rose 0.83% to 25,372 and the S&P 500 gained 0.36% to 7,569, while the Dow Jones lost 0.38% to 51,787.
That split tells the story. Money chased growth shares, while the older industrial names that dominate the Dow gave a little back.
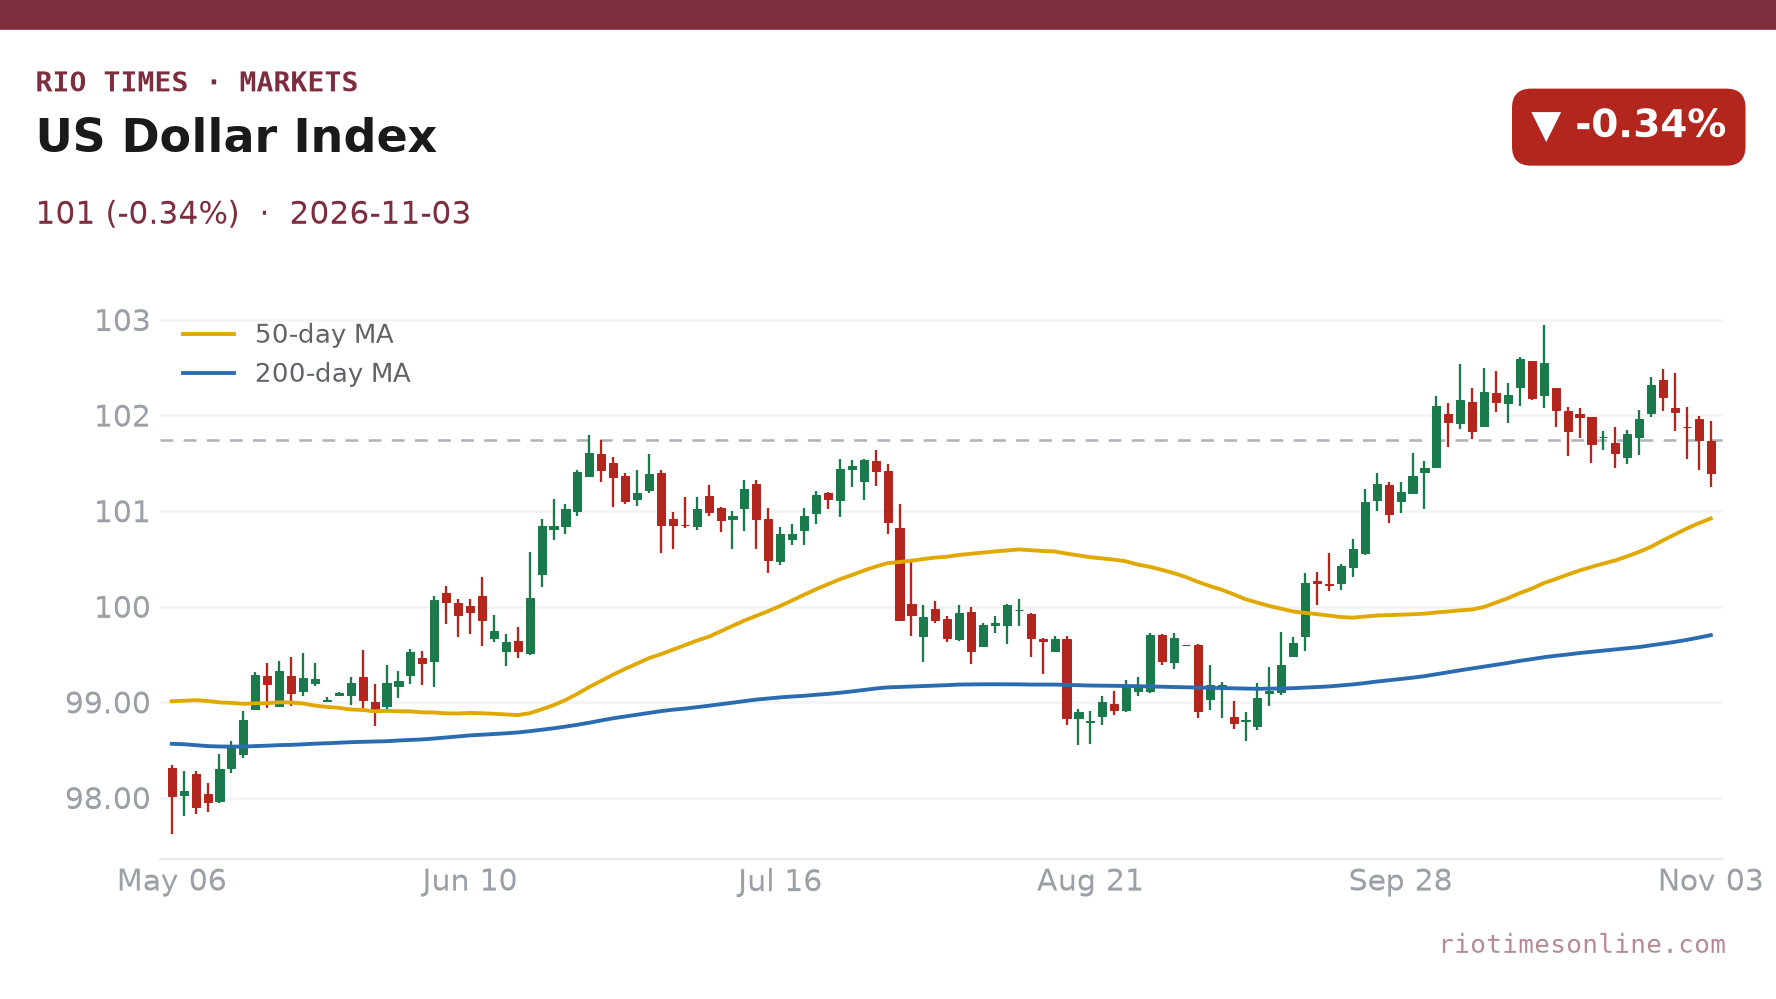
The S&P 500 is still 2.3% below its 28 October close of 7,744, so Tuesday’s gain was a partial recovery, and the dollar index is down from 102.32 on 27 October to 101.39. The VIX eased 1.51% to 20.83, which is calm but not complacent.
Americans voted in midterm elections on Tuesday, and we have no confirmed result to report.
02 The Fed leans towards a hike
The 10-year Treasury yield stands at 4.974%, up 6.5 basis points on the day and still below its 28 October level of 5.021%. The Fed’s statement of 28 October says it held rates at 3.75% to 4.00% by a 10-2 vote.
Governor Lisa Cook and Cleveland Fed President Beth Hammack voted for a quarter-point rise. Polymarket bettors give a 74.5% chance of a hike on 9 December.
Inflation is the reason, with September CPI reported at 3.7% and energy prices far above last year. The labour market is the counterweight, with September payrolls reported at just 29,000.
Hammack and Fed colleague Tom Barkin speak on Thursday, and the October jobs report follows on Friday.
What Prediction Markets Say
Polymarket’s “Fed Decision in December?” market, with US$11.6 million traded, prices a 25 basis point increase on 9 December at 74.5%, no change at 23.5%, and a 50 basis point or larger increase at 1.6% (as of 11:14 p.m. ET, 3 November). These are bets, not polls.
Why we show this: prediction markets turn real-money bets into a live probability that moves within minutes of the news, which is why investors, campaigns and newsrooms in the United States now follow them closely. We show them next to polls and official results, never instead of them.
03 Brazil waits for Copom as the dollar softens
Brazil’s central bank announces its Selic decision tonight, and the calendar consensus is a hold at 13.75%. Some traders still bet on a small cut, so the wording matters as much as the number.
For foreign investors, the Selic is the price of owning Brazilian bonds and the real. A US 10-year yield of 4.974% narrows the gap between Brazilian and American returns.
The dollar index fell 0.35% to 101.39, which helps emerging-market currencies at the margin. Gold slipped 0.25% to US$3,938 an ounce as higher yields made it costlier to hold.
Oil is the other thread. The EIA’s latest weekly report, for the week ending 23 October, showed commercial crude stocks of 410.6 million barrels, down 1.9 million, while gasoline stocks rose 3.9 million to 209.2 million (eia.gov/petroleum/supply/weekly).
Mexico’s central bank decides on Thursday, with the previous rate at 6.5%. Egypt’s composite PMI came in at 47.2 against a 48 consensus, a reminder that growth across emerging markets remains uneven.
Tuesday’s releases were not in our calendar feed when we published, so we cannot report actual results. Consensus for the US JOLTs Job Openings, a survey of vacancies, was 7.13 million (previous 7.079 million) and for JOLTs Job Quits 3.05 million (previous 3.066 million).
Brazil’s S&P Global Manufacturing PMI, a factory survey where readings below 50 mean contraction, had a consensus of 43 (previous 44.8). Mexico’s S&P Global Manufacturing PMI had a consensus of 50.1 (previous 50.3), and Mexican Business Confidence 48.2 (previous 48).
Today at 10:00 Lisbon time the euro area publishes its Harmonised Inflation Rate (previous 0.2) and Core Inflation Rate (consensus 2.5%, previous 2.5%). At 15:00 the US ISM Services Business Activity index, a services-sector survey, is due (consensus 56, previous 56.5), and at 15:30 the EIA Cushing Crude Oil Stocks Change (previous −0.624 million barrels), a gauge of storage at the main US oil hub.
Source: RT economic calendar (RT).
What to watch today and this week
- Thursday: Bank of England decision; US jobless claims (consensus 195,000) and productivity (consensus 2.5%); Fed’s Hammack and Barkin speak; Banxico rate decision; Brazil PMIs and industrial production.
- Friday: US October jobs report, the last big labour read before the 9 December Fed meeting.
- Next week: US October CPI on 10 November, the key test of the case for a hike.
- Ongoing: the 9 December FOMC, and Copom’s guidance on the Selic path.
Frequently Asked Questions
What did the Fed decide in October?
The Fed held rates at 3.75% to 4.00% on 28 October by a 10-2 vote. Two officials wanted a quarter-point rise.
Will the Fed raise rates in December?
Polymarket bettors give a 74.5% chance of a hike on 9 December. Friday’s jobs report and next week’s CPI will move that.
What is the Selic and why does it matter?
It is Brazil’s benchmark interest rate, now 13.75%. It drives returns on Brazilian bonds and the strength of the real.
Why do US Treasury yields matter for Brazil?
A 10-year yield of 4.974% makes dollar assets more attractive. That can pull money away from emerging markets and weaken their currencies.
How did US stocks close?
The S&P 500 rose 0.36% to 7,569 and the Nasdaq Composite gained 0.83% to 25,372. The Dow Jones fell 0.38% to 51,787.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Read More from The Rio Times