Brazil Bad-Loan Provisions Hit US$9.1 Billion as Defaults Climb
Brazil's four largest banks set aside about R$47 billion (US$9.1 billion) against bad loans in the second quarter, while industrial investment plans sank to a 2026 low.
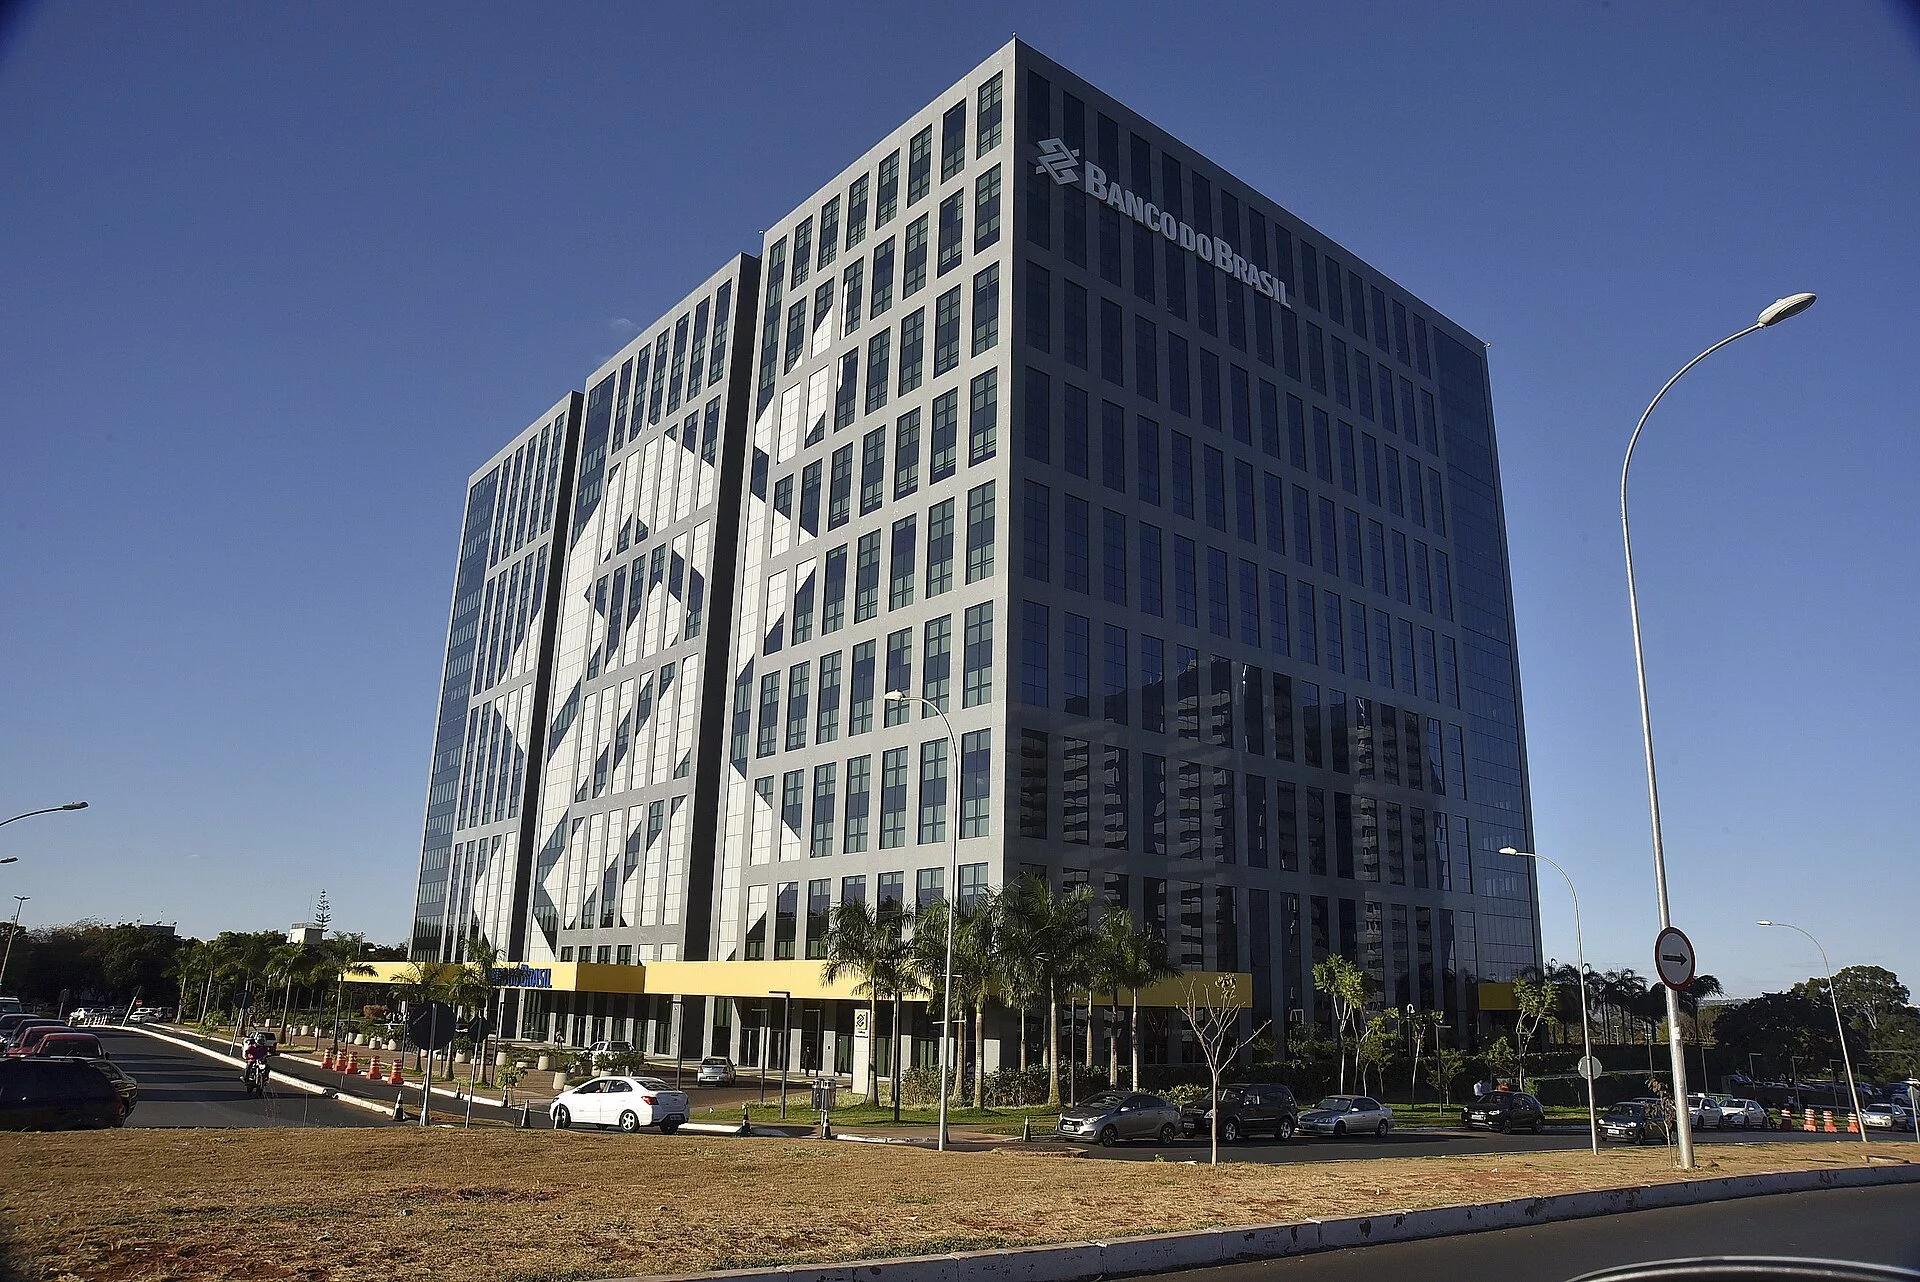
Brazil · Business
Key Facts
- —What happened Brazil’s four largest banks set aside roughly US$9.1 billion (R$47 billion) for bad loans in the second quarter of 2026.
- —How big a jump The provision pile grew from about US$7.7 billion (R$40 billion) in a single quarter, outpacing loan-book growth.
- —The real story Defaults are climbing: 4.7% of all bank credit was over 90 days overdue in June, near a record.
- —The catch All four banks stayed profitable, with Itau earning US$2.4 billion (R$12.4 billion) in the same three months.
- —Who is hit hardest Banco do Brasil, the biggest farm lender, saw overdue agriculture loans roughly double to 6.27% in a year.
- —What comes next Third-quarter results from late October will show whether the provisions buffer has peaked.
Factory bosses are flinching too: the CNI investment-intention index slid to 52.6 in August, its weakest reading of 2026.
Brazil bad-loan provisions at the country’s four largest banks climbed to roughly R$47 billion (US$9.1 billion) in the second quarter of 2026. That is cash parked aside for loans the lenders expect to sour.
On Thursday, the CNI industry confederation added a second warning light, reporting the weakest investment appetite of the year.
What Brazil Bad-Loan Provisions Actually Are
A provision is money a bank sets aside because it expects some borrowers to stop paying. It is an educated guess about tomorrow’s pain, booked today.
Because that cash comes straight out of profit, banks raise it reluctantly. So the jump in Brazil bad-loan provisions matters well beyond the trading floor.
The R$47 (about US$9.05)Billion Number, Bank by Bank
Add up the four second-quarter filings and the total lands at about R$47 billion, or roughly US$9.1 billion. Money Times, using data from Elos Ayta, reached the same headline number.
Banco do Brasil booked R$18.5 billion (US$3.6 billion). Itau Unibanco followed with R$10.5 billion (about US$2 billion), Bradesco with R$10.0 billion (about US$1.9 billion) and Santander Brasil with R$7.7 billion (about US$1.5 billion).
In that tally the pile grew from R$40 billion (about US$7.7 billion) in a single quarter. Bank of America notes provisions have been rising faster than the loan books behind them.
Santander Brasil shows the trend most sharply. Its provisions rose 20.6% from the first quarter and 11.5% from a year earlier, when they were R$6.86 billion (about US$1.3 billion).
Live Company IntelligenceBanco do Brasil S.A. — the full investor dossier
Banco do Brasil Takes the Hardest Hit
The state-controlled lender reported adjusted profit of R$3.9 billion (US$755 million) on 12 August. That is a fraction of what its private rivals earned.
Meanwhile Itau posted R$12.4 billion (US$2.4 billion) for the same three months. Bradesco made R$7.05 billion (about US$1.4 billion), while Santander Brasil slipped to R$3.0 billion (about US$578 million).
Banco do Brasil released the figures on 12 August. Profit was up 3.3% on the year and 13.9% on the quarter, yet it still trailed far behind Itau.
Bradesco, by contrast, grew profit 16.2% to R$7.05 billion (US$1.4 billion). Santander Brasil fell 17.6% to R$3.014 billion (US$582 million).
Why the Farm Belt Matters
Banco do Brasil is the country’s biggest agricultural lender, so the farm cycle lands directly on its books. Overdue farm loans reached 6.27% at the end of June.
A year earlier that ratio sat at 3.16%. In other words, bad debt in agriculture has roughly doubled in twelve months.
Shorter arrears tell the same story. Farm loans overdue by 30 days or more jumped from 7.35% to 8.97% between the first and second quarters.
The Default Numbers Behind the Buffer
Central bank data show 4.7% of all bank credit was more than 90 days overdue in June. That is a full percentage point higher than a year before.
May was marginally worse at 4.74%, the highest since the series began in 2011. Still, June sits within a whisker of that record.
Itau’s cost of credit reached R$10.139 billion (about US$2 billion), equal to 2.7% of its loan book. Bradesco’s expanded provision expense rose 22.6% on the year.
Households Are Stretched Thin
Household arrears stood at 5.6% in June, the worst reading on record. Company arrears hit 3.2%, the highest since November 2017.
Brazilian families now owe close to half of their annual income. Debt payments swallow almost 30% of monthly earnings, another record.
Household indebtedness hit a record 49.9% of annual income in February. Debt service reached 29.7% of monthly income, also the highest since the series began.
Rates Are Falling, but Slowly
The central bank cut the Selic to 14.00% on 5 August, its fourth straight quarter-point trim. Even so, borrowing costs remain punishing.
Governor Gabriel Galipolo says policy is still deliberately contractionary. Because rates bite with a lag, the damage from 15% money is only now surfacing.
The path down has been cautious. Rates began 2026 at 15.00%, then eased to 14.50% in April and 14.25% in June before August’s unanimous cut.
Banks Are Quietly Pulling Back
Reuters reported on 14 August that the big lenders are steering away from unsecured, higher-risk loans. Instead they favour collateral and better-off customers.
Itau chief executive Milton Maluhy said the outlook had worsened at the margin. As a result, the bank is tilting towards secured lending and away from unsecured consumer credit.
Bradesco chief Marcelo Noronha said appetite for lower-income clients is much lower than in the past. Santander trimmed exposure to people earning under R$4,000 (US$770) a month.
Factories Lose Their Appetite to Invest
On 20 August the CNI said its investment-intention index fell 0.6 point to 52.6. That marks a third consecutive decline and the weakest level of 2026.
Larissa Nocko, a CNI policy and industry specialist, blamed high interest rates, rising production costs and a surge of imported goods. Overall, factory owners are choosing to wait.
Another CNI gauge softened the picture slightly. Industrial confidence rose 1.9 points in August, although the sector has now spent 20 months in pessimistic territory.
Readings above 50 still signal expansion, so industry is not retreating outright. Even so, three straight monthly declines point to firms postponing decisions until money gets cheaper.
What to Watch Next
Third-quarter results, due from late October, will show whether the buffer has peaked. Bank of America notes provisions are growing faster than the loan books behind them.
Itau’s recurring profit of R$12.4 billion (about US$2.4 billion) was its eleventh consecutive quarterly increase. In short, the banks are still earning well while bracing for worse.
That gap usually signals more defaults ahead. Until arrears turn down, Brazil’s lenders will keep paying for caution.
Frequently Asked Questions
Why did Brazil bad-loan provisions rise in the second quarter of 2026?
Defaults climbed. Since 4.7% of all bank credit was more than 90 days overdue in June.
Which bank is most exposed?
Banco do Brasil. It set aside R$18.5 billion (US$3.6 billion) in the quarter.
Does this mean Brazilian banks are in trouble?
No. All four giants stayed profitable, and Itau earned R$12.4 billion (US$2.4 billion) in the quarter. Provisions are a cushion built in advance, not a hole in capital.
What is the CNI investment-intention index?
It is a monthly gauge of whether Brazilian manufacturers plan to invest. Readings above 50 signal expansion, and August’s 52.6 was the weakest of 2026.
Connected Coverage
Sources: Valor Econômico; Money Times; Reuters; Banco Central do Brasil; CNI.
This article was produced by The Rio Times’ automated AI newsroom. Editorial responsibility: Matthias Camenzind, Publisher and Editor-in-Chief. The Rio Times also runs Ask Rio Times, which answers from 100,000+ of our own articles, the daily Latin America Power Map, and prediction-market odds on elections and markets.. How we use AI · Report an error
Brazil runoff, Sunday, October 25: Brazil runoff date. Latest: Brazil runoff polls, Flávio 51%, Lula 49%.