Dow Drops 1.2% as Fed Meets Wednesday | Global Economy, Oct 26
Key Facts
- A critical week for central banks begins with the US Federal Reserve expected to keep its benchmark interest-rate range at 3.75–4.00% on Wednesday after a quarter-point increase in September.
- Oil pulled back from multi-month highs on Monday, with Brent crude lower.
- Strong US growth is complicating the rate path with preliminary third-quarter expansion forecast at a 3.2% annualised pace, up from 2.2% in the second quarter, keeping a December hike in play.
- Asia opened defensively on Monday with Japan’s Nikkei down about 0.8% after losing 4% last week, while South Korea’s Kospi stock index also slipped.
- The dollar held firm against major peers with the euro near US$1.12 and the yen at 157 per dollar, supported by expectations that resilient US growth may require additional tightening.
- Prediction markets on Polymarket, an online exchange where users bet real money on outcomes, price a 76.5% chance of another US Federal Reserve rate hike before the end of 2026 (US$1.07 million traded; 26 October, 00:01 ET).
Today’s Focus
The Federal Reserve is all but certain to leave its benchmark rate at 3.75–4.00% on Wednesday, but the real debate has shifted to December. Preliminary US GDP for the third quarter is forecast at 3.2% annualised, a sharp acceleration from 2.2% in the prior quarter.
The Fed’s preferred inflation gauge—core personal-consumption expenditure—is expected at 3.1% year-on-year, still well above the central bank’s 2% target. That combination of hot growth and sticky inflation keeps the door open for another quarter-point increase before year-end.
Oil’s retreat from multi-month highs offers some relief to importers. Brent dropped on Monday but stays well above US$100 a barrel, with traders watching for any resumption of strikes involving Iran.
European and Japanese policymakers meet later this week. The European Central Bank is expected to hold its deposit rate at 2.50% on Thursday, while the Bank of Japan decides on Friday, giving global markets three successive days of central-bank signalling.
What matters today. Whether strong US growth and persistent inflation force the Fed to signal another hike in December, rather than staying on hold.
| Instrument | Level | Session |
|---|---|---|
| S&P 500 (US) | 7,624 | -0.52% |
| Ibovespa (Brazil) | 205,083 | +0.47% |
| USD/BRL | 4.9776 | -1.32% |
Source: market close, 23 October 2026.
01 The world in one read
Global markets enter a week dominated by three major central-bank decisions, with the US Federal Reserve up first on Wednesday. The Fed is widely expected to hold its policy rate at 3.75–4.00%, pausing after September’s quarter-point increase.
The pause masks a live December debate. Preliminary US third-quarter GDP is forecast at 3.2% annualised, nearly a full point above the second quarter, and core inflation remains stuck above 3%.
Oil offered a rare pocket of relief. Brent fell on Monday, retreating from multi-month highs, but stays well above US$100 a barrel.
Asian equities were defensive rather than panicked, with Japan’s Nikkei down about 0.8% and South Korea’s Kospi also lower. Investors are still weighing energy costs against wobbles in technology and artificial-intelligence spending.
The evidence leans toward a patient Fed this week but a nervous December. A 3.2% growth print and 3.1% core inflation leave policymakers with little room to declare victory, yet they are unlikely to surprise markets with a move absent fresh shocks. The variable to watch is how strongly Chair Jerome Powell pushes back against market pricing for another hike—or lets it survive.
02 The global board
| Instrument | Level | Change | Read |
|---|---|---|---|
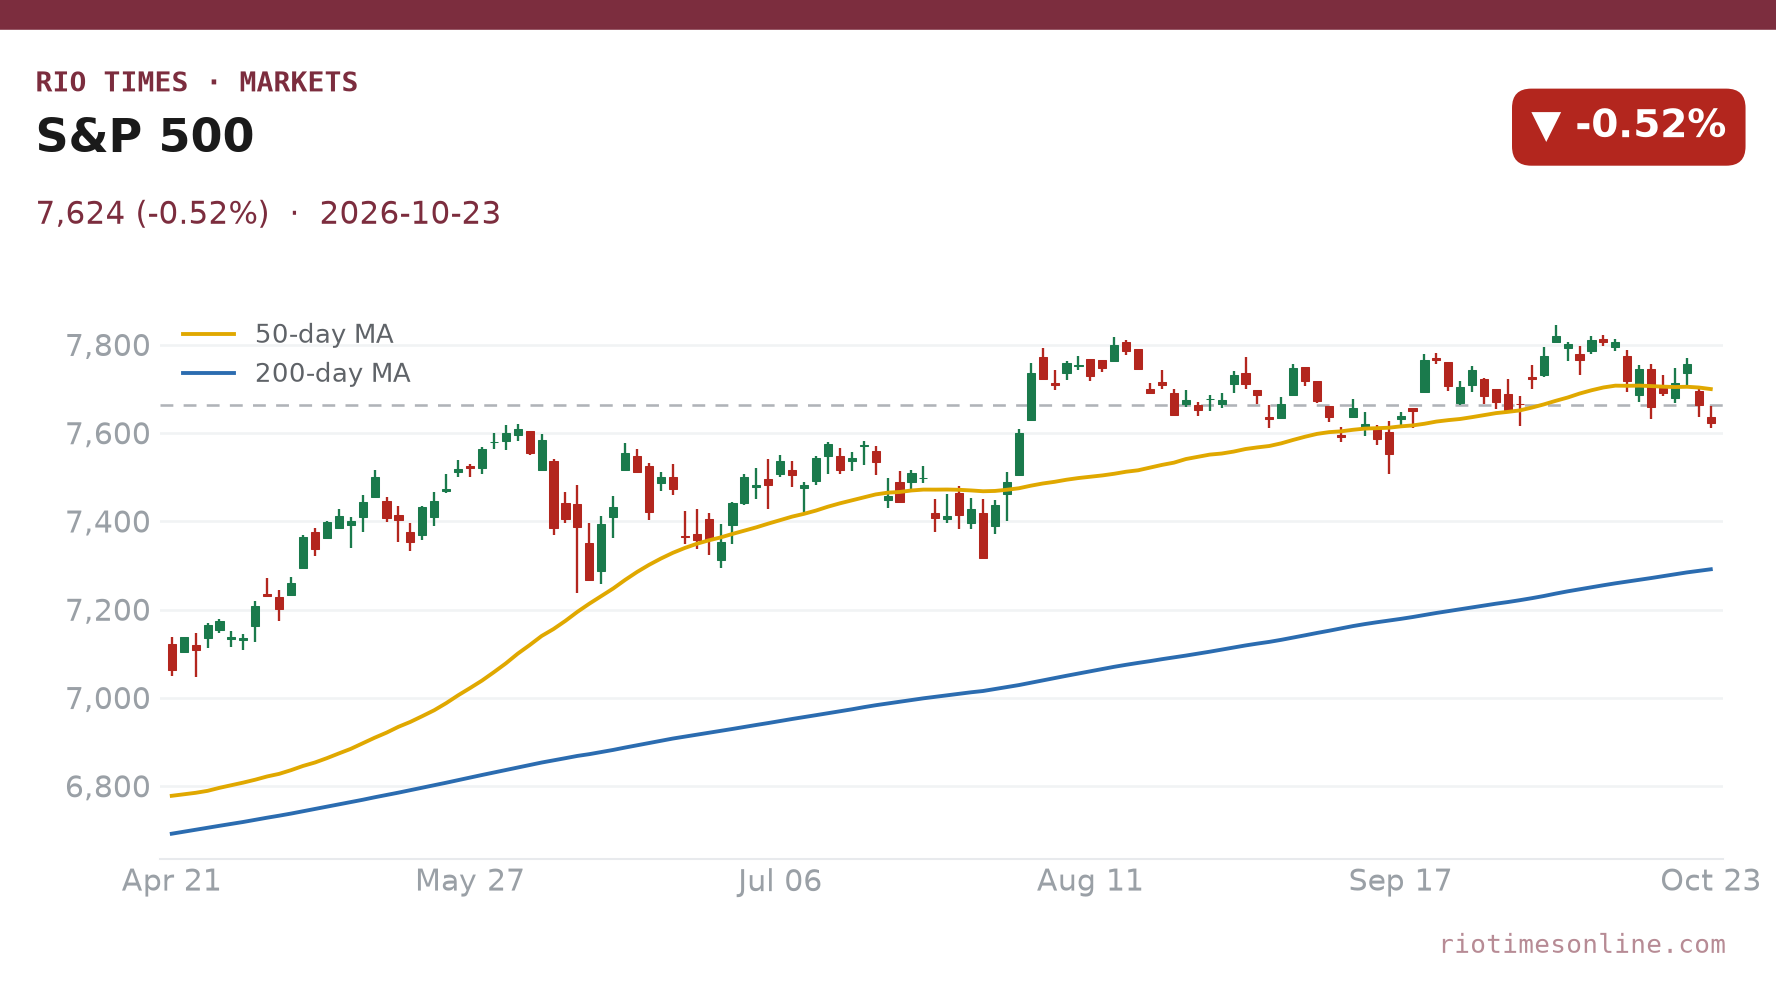
| S&P 500 | 7,624 | −0.52% | US equities slipped before a heavy data week |
| Nasdaq | 25,955 | −0.21% | Tech held firmer than industrials |
| Dow Jones | 52,215 | −1.23% | Blue chips led the decline |
| VIX | 19.45 | +2.21% | Volatility crept up but stays subdued |
| US 10Y yield | 5.001% | +0.89% | The psychological 5% level holds firm |
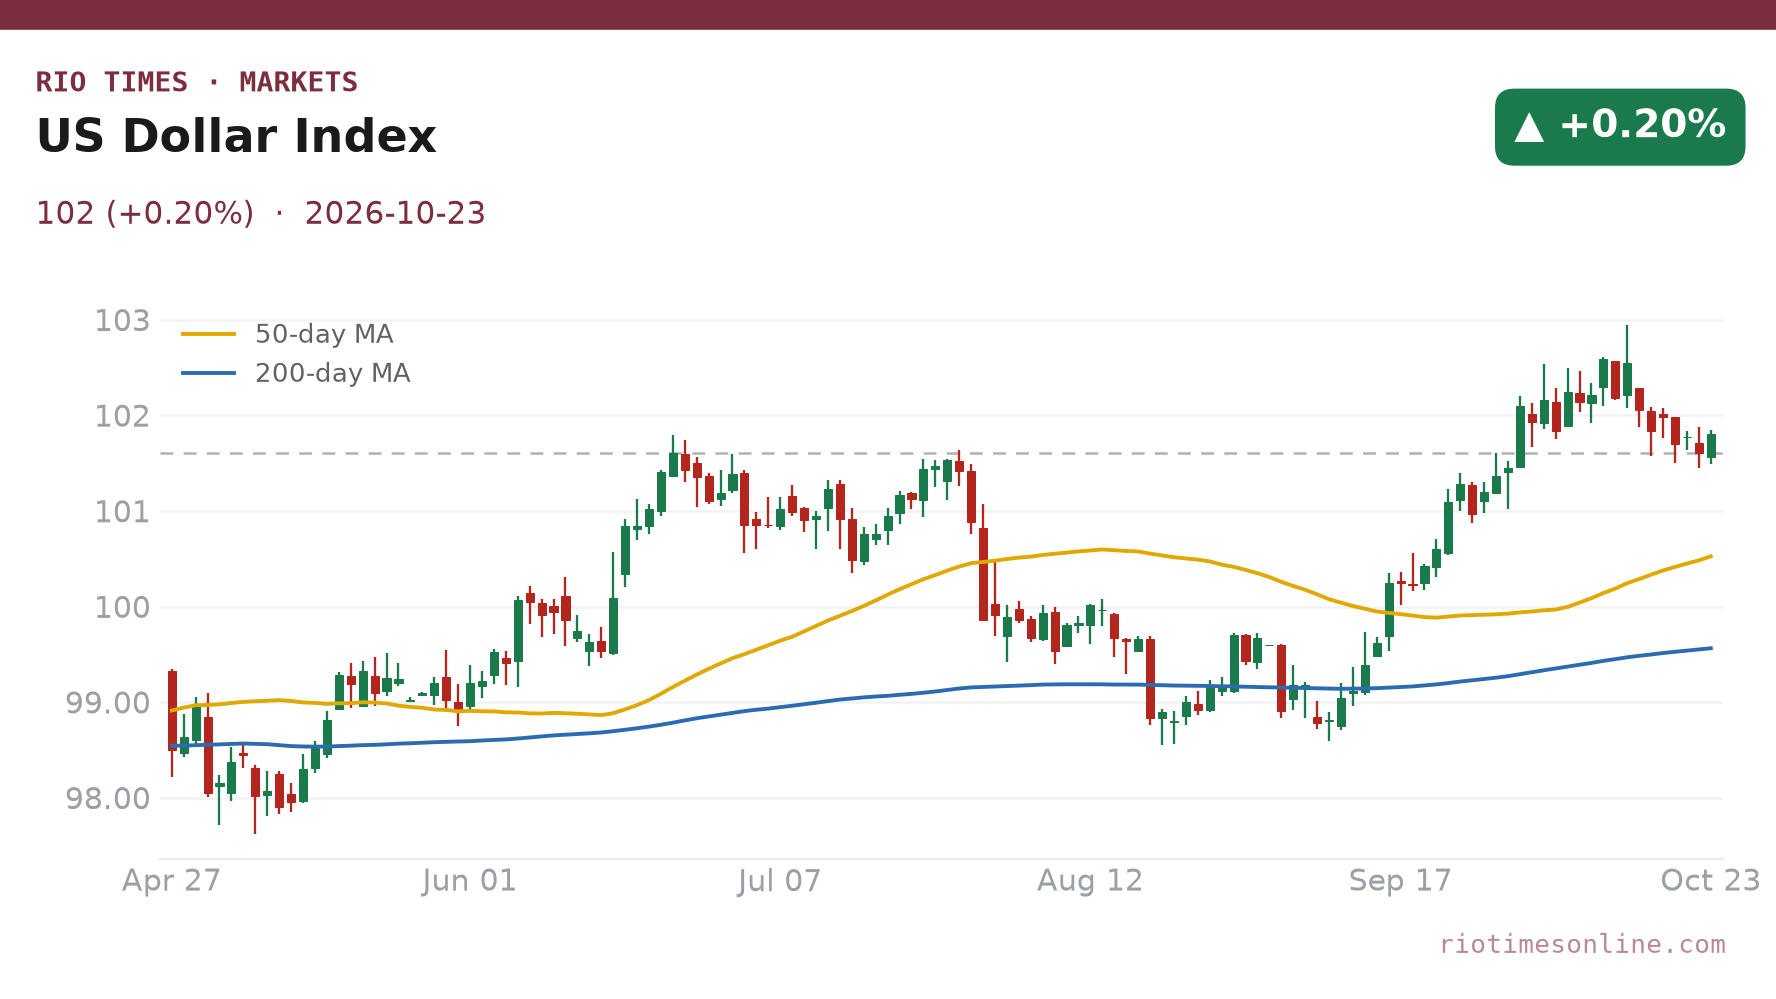
| DXY | 101.81 | +0.20% | Dollar index edged higher |
| Gold | US$3,994/oz | −0.75% | Haven buying faded near the $4,000 mark |
| Brent crude | above US$100/barrel | lower | Pulled back from multi-month highs on Monday |
The board shows a modest risk-off tilt as investors position for central-bank decisions. The Dow Jones took the heaviest hit at −1.23%, while the tech-heavy Nasdaq lost only 0.21%, suggesting the sell-off was concentrated in more traditional industrial and rate-sensitive names.
The US 10-year Treasury yield settled right at the symbolic 5% threshold, reflecting the market’s acceptance that high borrowing costs are not leaving quickly. Gold faded near the $4,000 mark, a sign that haven demand moderated as oil cooled. Rio Times · Live Market Intelligence
Live Market IntelligenceGlobal Markets — Live Board
Global Markets — Live Board
Instrument Last Change YoY Prev. High Low Volume
SPX
7,751
+0.29%
—
—
—
—
—
NDX
29,799
+0.93%
—
—
—
—
—
DJI
53,810
+0.03%
—
—
—
—
—
RUT
3,041
+0.46%
—
—
—
—
—
US10Y
4.6760
-0.17%
—
—
—
—
—
VIX
14.60
-4.45%
—
—
—
—
—
DAX
26,331
-0.23%
—
—
—
—
—
FTSE
10,833
-0.10%
—
—
—
—
—
CAC
8,675
-0.46%
—
—
—
—
—
STOXX
659.48
-0.16%
—
—
—
—
—
NIKKEI
67,524
+0.83%
—
—
—
—
—
HSI
25,440
-0.83%
—
—
—
—
—
KOSPI
6,579
+3.68%
—
—
—
—
—
CSI300
4,691
+0.58%
—
—
—
—
—
NIFTY
24,436
-0.15%
—
—
—
—
—
TSX
36,619
+0.39%
—
—
—
—
—
GOLD
4,461
+1.78%
+33.20%
4,383
4,503
4,421
139,824
SILVER
65.59
+1.26%
+73.05%
64.77
66.98
64.81
46,406
03 The main event — a week of central-bank decisions
The Federal Reserve leads off on Wednesday with a hold widely priced in at 3.75–4.00%, but the decision is not the main uncertainty. The market’s real question is whether policymakers signal that September’s hike was the last or merely a pause before another move.
The European Central Bank follows on Thursday, expected to keep its deposit rate at 2.50%. The Bank of Japan rounds out the week on Friday, with investors watching for any drift toward policy normalisation.
The backdrop for all three is an economy that refuses to buckle under high rates. US growth is forecast to hit 3.2% annualised in the third quarter, and the labour market remains resilient enough to sustain wage pressure.
Oil is the wildcard. If supply fears return and energy costs climb back toward their highs, central banks will face a renewed inflation headache that could tilt the December calculus.
What Prediction Markets Say
On Polymarket, an online exchange where users trade real money on outcomes, traders price another Fed rate hike before the end of 2026 at 76.5% (US$1.07 million traded) and a Fed rate cut by the December meeting at 2.5%, as of 00:01 ET on 26 October. These prices are bets, not polls.
Why we show this: prediction markets turn real-money bets into a live probability that moves within minutes of the news, which is why investors, campaigns and newsrooms in the United States now follow them closely. We show them next to polls and official results, never instead of them.
04 Policy and data
The week’s data calendar is packed with signals that will shape the December decision. Durable goods orders for September are due on Tuesday, with the headline number forecast at 0.6% and the core measure excluding transport at 0.6%.
US consumer confidence is expected at 80.5, down from 81.9, while new home sales are seen slipping to 0.66 million. House price data will also land, with the S&P/Case-Shiller index forecast to rise 2.6% year-on-year.
Friday’s surveys set the tone. US business activity stayed strong: the S&P Global manufacturing PMI, a monthly survey of purchasing managers in which 50 separates growth from contraction, was 56.0 (forecast 55.5, previous 55.9), services 57.9 (forecast 58.0, previous 58.8) and the composite 57.6 (forecast 57.6, previous 58.4). University of Michigan consumers expect 4.7% inflation over one year (forecast 4.7%, previous 4.6%) and 3.5% over five years (forecast 3.5%, previous 3.4%).
Europe and Japan were more mixed. The euro-zone composite PMI fell to 51.9 (forecast 52.7, previous 53.1), with services at 51.7 (forecast 52.5, previous 53.0) and manufacturing at 52.4 (forecast 52.7, previous 52.9). Japan’s composite PMI held at 52.3 (forecast 51.9, previous 52.3) while manufacturing slipped to 53.3 (forecast 54.5, previous 54.1). Britain’s composite PMI rose to 53.1 (forecast 51.8, previous 52.0), services to 53.1 (forecast 51.8, previous 52.1) and manufacturing to 52.8 (forecast 51.7, previous 51.9), yet retail sales fell 0.4% (forecast −0.1%, previous +0.7%) and 0.7% excluding fuel (forecast −0.1%, previous +0.9%). Source: RT economic calendar (RT).
Core personal-consumption expenditure inflation, the Fed’s preferred gauge, prints on Thursday at an expected 3.1% year on year. That is far enough above 2% to keep policymakers from declaring the inflation battle won.
In Europe, the ECB’s hold at 2.50% on Thursday will be scrutinised for any hint that policymakers are debating a cut in 2027. For now, sticky services inflation argues for patience.
05 Commodities and currencies
Oil’s retreat from multi-month highs was the main mover in commodities. Brent slipped on Monday but stays well above US$100 a barrel.
The dollar index edged higher, supported by the view that US rates may need to stay elevated into December. The euro held near US$1.12, while the Japanese yen traded near 157 per dollar after edging higher last week.
Gold eased from the US$4,000-an-ounce threshold as the immediate haven bid faded alongside oil. Silver also dropped more than 1%, reflecting the broader pullback in precious metals.
The message from currency markets is one of patience: the dollar is not surging, but it is not weakening either, as traders wait for the Fed’s assessment of growth, inflation and December risk.
06 The Latin American read-through
The external backdrop remains challenging for Latin American economies, even as oil retreats from its highs. Brent well above US$100 a barrel keeps energy import bills elevated for countries such as Chile and Peru, while producers like Brazil and Colombia see a partial offset from export revenues.
The prospect of US rates staying higher for longer is a headwind for regional currencies and sovereign borrowers. A December hike would draw capital toward dollar assets and raise the cost of refinancing dollar-denominated debt.
Domestic policy remains the main driver for Latin American markets this week. Brazil, Mexico and Chile each have local data on the calendar that will shape investor expectations for growth and inflation.
Local data on Friday was mixed. Brazil’s mid-month inflation gauge, the IPCA-15, rose 0.32% in October against a 0.43% forecast (previous 0.70%), taking the annual rate to 4.62% (forecast 4.73%, previous 4.47%). Mexico’s economic activity indicator for August rose 0.6% on the month (forecast 0.3%) and 3.3% on the year (forecast 3.1%). Source: RT economic calendar (RT).
The takeaway for regional investors is caution, not panic. The global tone is defensive, but the absence of a sharp dollar spike or sustained oil shock leaves room for local stories to dominate individual markets.
07 What to watch
- Fed’s Wednesday statement: Any shift in language about further hikes would move global rate expectations quickly
- US third-quarter GDP: A print near 3.2% would keep December tightening firmly on the table
- Core PCE inflation: The Fed’s preferred gauge at 3.1% is the clearest signal on the December decision
- Brent crude’s next move: A rebound above US$120 would renew energy-driven inflation fears for importers
Background: Dow Falls 1.2% as AI Spending Fears Hit Tech.
Background: Nasdaq Drops 0.2% as Gold Falls and Fed Hike Looms.
Frequently Asked Questions
Will the Fed cut rates this week?
No. Markets expect the Fed to hold its benchmark range at 3.75–4.00% on Wednesday.
Why is December still uncertain?
Strong US growth and inflation above 3% keep the door open for another hike despite the pause this week.
What moved oil prices?
Brent fell on Monday, retreating from multi-month highs, but stays well above US$100 a barrel.
How does this affect Latin America?
Higher-for-longer US rates and expensive oil raise borrowing and import costs, though producers get some revenue relief.
Market data: RT
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.