Brazil Stocks Fall 1.06%; Jobs and Budget Data Due | Morning Call, Oct 30
Key Facts
- The Selic wager is the spine of today’s trade, with Brazil’s policy rate at 13.75% after a September cut and the next decision due 4 November.
- September unemployment lands at 9:00 am BRT, with the consensus at 5.2% against 5.3% before; a firm labour market would complicate rate cuts.
- Fiscal data is the swing factor, as traders watch the gross debt-to-GDP ratio and a budget deficit expected to narrow to R$100bn (about US$18.6bn).
- Vale holds its earnings webcast today, with funds listening for copper, nickel and dividend signals.
- The real is pinned near its weaker end, with CFTC positioning data later showing how crowded the BRL short trade has become.
Today’s Focus
Friday’s open is a rates story wearing a corporate costume. The Selic — Brazil’s benchmark interest rate — sits at 13.75% after a quarter-point cut in September, and local funds are gauging how fast the central bank will keep easing. Mid-month inflation, measured by the IPCA-15 index, cooled to 0.32% in October from 0.70% in September; today’s jobs and fiscal numbers either confirm that view or spoil it.
Vale, the iron-ore giant, dominates the corporate radar after publishing its third-quarter results on Thursday, with its earnings webcast due today. Management’s tone on copper, nickel and dividends matters more than yesterday’s numbers, because it shapes how funds read the miner’s shift away from pure iron-ore exposure.
The calendar is front-loaded: fiscal data at 8:30 am BRT, unemployment at 9:00 am BRT. The dollar-real pair will take its cue from those releases, with the board showing the currency still near the weak end of its 52-week range.
Foreign positioning is the wildcard. CFTC data released later today reveals how crowded the Brazilian real short trade has become — a crowded short can unwind violently if today’s domestic figures beat expectations.
What matters today. Whether Brazil’s labour and fiscal data keep the Selic-easing narrative alive through the open.
Today’s Economic Events
| Instrument | Level | Session |
|---|---|---|
| Ibovespa (Brazil) | 169,186 | -1.06% |
| S&P 500 (US) | 7,720 | -0.30% |
| USD/BRL | 5.3806 | +0.58% |
Source: market close, 29 October 2026.
01 The setup in one read
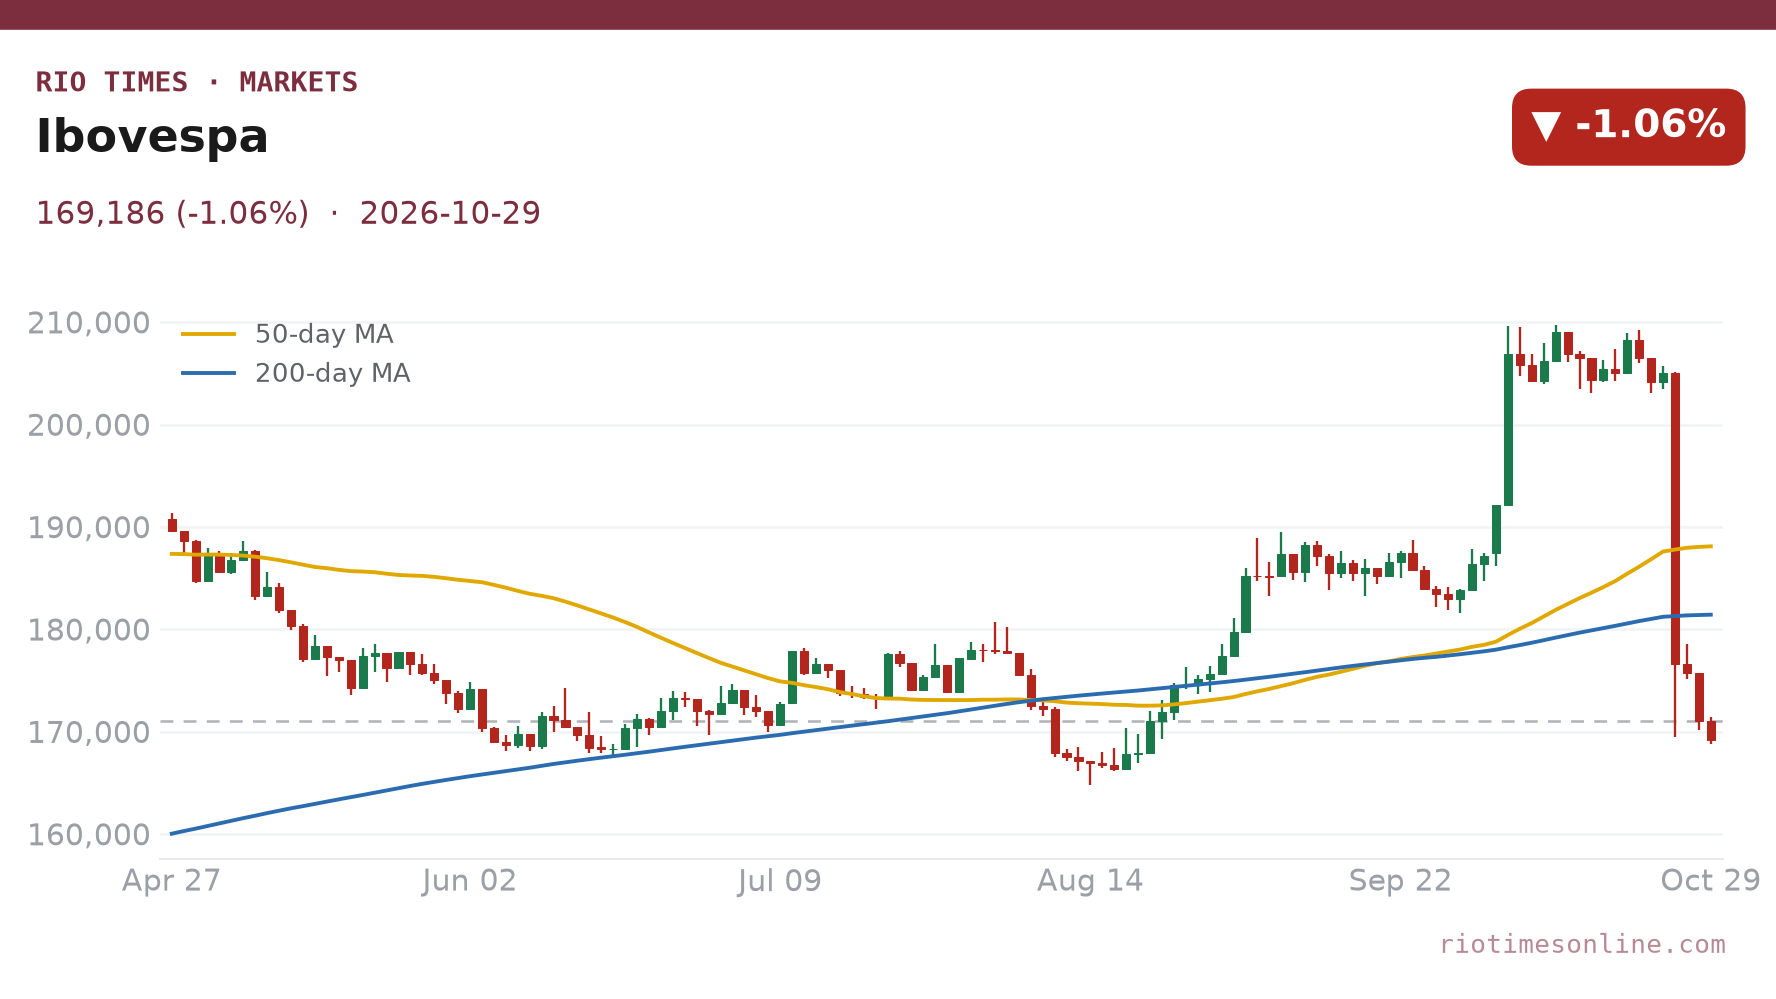
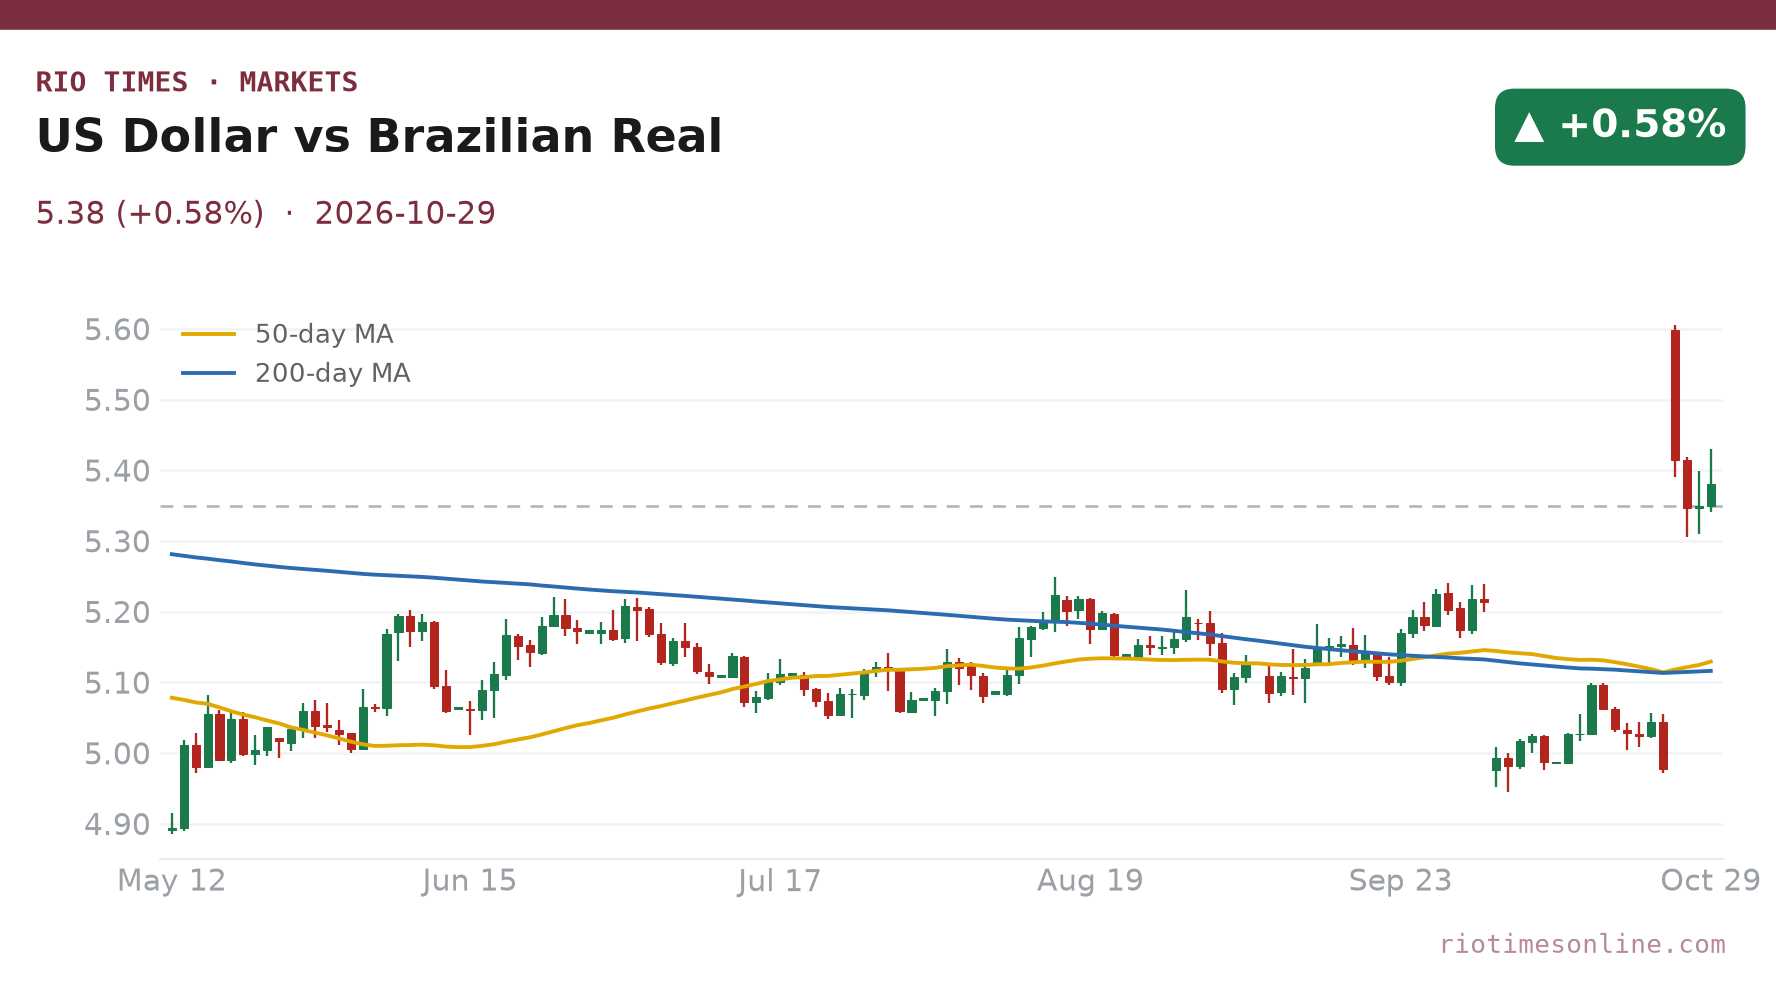
The Ibovespa — Brazil’s benchmark stock index — opens Friday nursing a four-session losing streak, with the board showing the index deep below its 52-week high. The real, Brazil’s currency, is also near its weakest levels of the year against the US dollar. Neither move is about today’s headlines: both reflect the long shadow of Brazil’s recent election and the market’s struggle to price the next policy chapter.
That makes today a rates-and-fiscal session. The Selic — the central bank’s policy rate — is at 13.75% after a September cut, and the IPCA-15 inflation reading cooled to 0.32% in October from 0.70% in September, which supports expectations of further easing. Today’s labour and budget data are the first major tests of that thesis.
Vale, Brazil’s mining heavyweight, adds a corporate pulse after publishing third-quarter results on Thursday. Traders will watch whether the payout story, a key reason foreign funds hold the stock, survives today’s earnings webcast.
Wall Street closed lower on Thursday, with the S&P 500 down 0.30%, and the US dollar index eased 0.43%. For B3, the domestic calendar matters more: traders will position ahead of the 9:00 am BRT unemployment release rather than chase Wall Street’s overnight drift.
The evidence points to a cautious open: a cool inflation print has given the easing story credibility, but the fiscal picture remains fragile and the real is still near its weakest levels of the year. Vale’s payout focus and today’s jobs data offer concrete catalysts, yet nothing in the local calendar is strong enough to reverse the broader risk-off drift. The variable to watch is the September budget balance at 8:30 am BRT — a wider-than-expected deficit would test the entire rates narrative before the bell.
02 Where Brazil is set to open
| Instrument | Last close | Indicated | Watch today |
|---|---|---|---|
| Ibovespa (Brazil stock index) | 169,186 | — | Unemployment and fiscal data set the opening tone |
| USD/BRL (real per dollar) | 5.3806 | — | Jobs data and Selic positioning drive the currency |
| Vale (VALE3) | — | — | Copper strength and dividend commentary |
| Petrobras (PETR4) | — | — | Oil price drift and payout expectations |
The table shows the Ibovespa and the real both trading near their weakest levels of the year, with no clear pre-market indication available from the overnight sources. That absence of a firm lead is itself a signal: funds are waiting for Brazil’s domestic data before committing.
The US dollar index eased 0.43% on Thursday and the S&P 500 fell 0.30%, but B3’s fate today will be decided in Brasília, not New York. The 9:00 am BRT unemployment print and the 8:30 am BRT budget balance are the events that will move the real and the index. Rio Times · Live Market Intelligence
Live Market IntelligenceBrazil Morning Call — Live Board
Brazil Morning Call — Live Board
Instrument Last Change YoY Prev. High Low Volume
IBOV
169,186.42
-1.06%
+19.56%
171,006.10
178,526
175,157
—
USD/BRL
5.34
-1.32%
-0.84%
5.42
5.42
5.30
—
EUR/BRL
5.95
+7.53%
-4.87%
5.54
6.04
5.92
—
SELIC
13.75%
—
—
—
—
—
BRENT
109.58
-5.38%
+66.99%
115.81
111.92
109.00
34,268
WTI
100.12
-1.61%
+63.30%
101.76
102.82
99.77
201,568
IRON ORE
161.91
—
+53.37%
161.91
161.91
1
GOLD
4,073
+0.85%
+1.32%
4,038
4,079
4,002
117,083
SILVER
54.49
+0.70%
+17.02%
54.11
54.64
52.71
34,428
LITHIUM
62.43
+1.89%
+5.14%
61.27
62.62
61.56
130,024
SOY
1,250
+0.70%
+17.12%
1,241
1,262
1,249
156,494
CORN
450.25
-1.04%
+5.01%
455.00
455.00
449.75
143,350
WHEAT
614.75
-0.20%
+16.87%
616.00
618.50
610.00
51,884
COFFEE
294.35
-2.19%
-24.54%
300.95
304.90
289.05
16,022
SUGAR
19.26
+0.84%
+33.20%
19.10
19.42
19.03
74,161
ORANGE JUICE
143.20
+5.45%
-26.07%
135.80
148.80
142.50
1,394
COTTON
77.90
-1.47%
+20.66%
79.06
81.07
80.01
20,308
BEEF
230.73
+0.33%
+0.83%
229.98
231.58
229.75
13,888
CATTLE
346.40
-1.00%
+0.26%
349.90
349.70
346.33
5,755
COCOA
5,581
+1.66%
-9.72%
5,490
5,622
5,444
13,619
PETR4
53.31
-1.06%
+77.70%
53.88
53.70
52.83
43,239,500
VALE3
62.88
-2.33%
+1.98%
64.38
64.43
62.80
24,652,300
SUZB3
47.14
-0.55%
-3.79%
47.40
47.84
46.10
7,151,800
KLABIN
18.73
-0.43%
+6.46%
18.81
19.04
18.45
6,051,800
SLCE3
16.97
-2.75%
+19.37%
17.45
17.77
16.94
3,109,500
ABEV3
15.40
+0.20%
+26.75%
15.37
15.68
15.31
27,307,400
ITUB4
41.42
-0.67%
+11.30%
41.70
42.60
41.15
28,160,700
BBDC4
15.69
-1.63%
-13.88%
15.95
16.30
15.67
65,766,400
BBAS3
17.59
+0.69%
-15.59%
17.47
18.31
17.51
67,844,600
B3SA3
15.27
+1.33%
+21.71%
15.07
15.78
15.20
75,282,000
WEGE3
45.78
+2.81%
+10.06%
44.53
47.08
45.06
9,823,200
PRIO3
69.21
-2.71%
+87.14%
71.14
70.98
69.15
6,663,200
RENT3
31.14
-1.67%
-20.73%
31.67
32.68
31.02
19,092,400
AZZA3
16.72
+1.15%
-42.24%
16.53
17.42
16.72
4,875,400
CSNA3
4.76
-4.99%
-47.09%
5.01
5.14
4.76
14,327,900
GGBR4
24.87
-2.28%
+36.28%
25.45
26.20
24.79
7,507,900
ENEV3
26.79
+0.45%
+49.78%
26.67
27.35
26.30
12,263,000
LREN3
9.75
+0.72%
-33.67%
9.68
10.33
9.75
29,053,800
03 On the B3 radar today — jobs, fiscal and Vale’s payout
| Item | When | Why it matters |
|---|---|---|
| September unemployment rate | 9:00 am BRT | Consensus 5.2%; a softer labour market supports the Selic-easing case |
| Gross debt-to-GDP ratio | 8:30 am BRT | Fiscal credibility test; consensus 83.5% vs 82.9% prior |
| Budget balance | 8:30 am BRT | Deficit seen narrowing to R$100bn (about US$18.6bn) from R$116bn (about US$21.6bn); wider gap hurts the real |
| CFTC speculative BRL positions | 4:30 pm BRT | Shows how crowded the short-real trade is among global funds |
| Vale Q3 earnings call | — | Copper and nickel growth vs falling iron-ore prices |
| SAUD3 ex-dividend | All day | Shares trade without their latest dividend entitlement |
The morning double — fiscal data and unemployment — is the session’s pivot. The consensus sees unemployment at 5.2%, a slight improvement from 5.3%, while the gross debt-to-GDP ratio is expected to rise to 83.5% from 82.9%. A worse fiscal number would put immediate pressure on the real and B3, because it would narrow the central bank’s room to cut rates.
Vale’s earnings webcast is the corporate event to follow. After Thursday’s third-quarter report, investors want to hear how management sees copper and nickel growth against iron-ore prices, and what that means for the dividend.
The CFTC positioning data landing later today is a slow-burn catalyst. It tells traders how one-sided the bearish real bet has become; a crowded short can produce sharp bounces on any positive domestic surprise.
04 Copom and the macro backdrop
The Copom — Brazil’s rate-setting committee — holds the market’s imagination. The Selic is at 13.75% after a quarter-point cut in September, and October’s IPCA-15 reading of 0.32% (0.70% in September) points to cooling prices. The next decision comes at the 3–4 November meeting.
Thursday’s United States data set the backdrop. The US economy grew at an annualised 3.4% in the third quarter against a 3.2% consensus and 2.2% in the second, the Bureau of Economic Analysis (BEA, the US statistics agency) reported. Quarterly PCE prices, the Fed’s preferred inflation gauge, rose 2.1% annualised against 3.4% expected, while the September core PCE price index, which strips out food and energy, held at 3.1% year on year as forecast; headline PCE rose 3.6%. Initial jobless claims fell to 194,000 against 199,000 expected, continuing jobless claims to 1.701 million against 1.72 million expected, and the four-week average eased to 196,750 (US Department of Labor). The Fed held rates at 3.75%–4% on Wednesday, with two members preferring a quarter-point rise, so high US rates limit how far Brazil’s central bank can cut without pressuring the real. Quarterly core PCE prices were not yet in our calendar feed.
In Brazil, September net payrolls (the formal-jobs count, consensus 180,000 against 165,827 in August), the primary budget surplus and bank lending were also due on Thursday. Their actual figures were not available in our data at publication. Sources: BEA, US Department of Labor, Federal Reserve, RT economic calendar (RT).
Today’s data refines that wager. If unemployment comes in near 5.2% and the budget deficit narrows as forecast, the easing narrative gains momentum and rate-sensitive names — retailers, homebuilders, banks — should trade firmer. If fiscal data disappoints, the central bank’s cautious tone will be reinforced.
The global current is mixed. A softer US dollar helps the real, but strong US growth and a Fed on hold keep the US rate gap wide, which still caps how fast Brazil’s central bank can ease.
But Brazil’s risk premium is local. The Ibovespa has lost about 17.5% since its 23 October close, two days before the presidential runoff, and the real is weak. Until fiscal credibility is restored, the path of the Selic will carry a Brazilian-specific fear premium that no amount of global calm can erase.
05 Corporate stories to watch today
Vale is the day’s headline corporate name. The mining giant published its third-quarter report on Thursday and hosts its webcast today. The crucial detail for funds is how management frames copper and nickel growth against iron ore, because that underpins the dividend story.
Petrobras, Brazil’s state-controlled oil producer, remains in focus. Oil prices have been drifting, and any signal from Brasília about fuel pricing or dividend policy will move the stock faster than global crude markets can.
A cluster of ex-dividend and payment dates adds mechanical noise. Saudita (SAUD3) trades without its latest dividend entitlement, and other listed companies have distributions due.
The banking complex — Itaú, Bradesco, BTG — will trade off the fiscal and unemployment data. A credible budget and a softening labour market would be a double tailwind: lower default risk and a clearer path to lower rates.
06 The levels to watch at the open
For the Ibovespa, the board shows a level deep below its 52-week high, and any recovery must first hold above Thursday’s settle. A break below that level on weak fiscal data would extend the losing streak to five sessions and draw in new selling from momentum funds.
The real is the more important level. The board shows USD/BRL near its weakest end of the 52-week range, and 5.40 is the psychological line traders are watching. A jobs miss or a wider deficit pushes the pair toward the year’s high; a beats pulls it back toward 5.30.
Vale shares will react to the earnings call tone, not the reported numbers alone. If management signals that copper growth can offset weaker iron-ore prices, the stock could stabilise and support the index. If not, the miner’s weight in the Ibovespa makes it a drag.
The session’s risk is concentrated in the 8:30–9:00 am BRT window. Traders should expect thin liquidity before the data, a sharp move immediately after, and then a drift as New York absorbs the numbers.
07 What to watch
- Fiscal data: September budget balance and debt-to-GDP at 8:30 am BRT; a wider deficit would hit the real and delay rate-cut bets
- Unemployment rate: The 9:00 am BRT release; a soft reading strengthens the Selic-easing case, a tight one complicates it
- Vale’s dividend tone: How management frames the payout in a weaker iron-ore price environment
- CFTC real positioning: Today’s data shows how crowded the short-BRL trade is; a heavy short can snap back on any positive surprise
Background: Wheat Fund Edges Up 0.23% as Bunge Falls 4.74%.
Background: Oil Rises About 0.7% as YPF Falls 3.1%.
Frequently Asked Questions
What is the Selic and why does it drive B3 today?
The Selic is Brazil’s benchmark interest rate, set by the central bank’s Copom committee. It is currently 13.75%, and today’s jobs and fiscal data will shape how soon and how fast the bank can cut it — which moves the whole equity market.
Why does Vale matter to the whole index?
Vale is one of the largest companies on the Ibovespa, Brazil’s main stock index. Its earnings and dividend policy steer sentiment across the materials sector and influence how foreign funds view Brazilian risk.
What time are the key releases?
Fiscal data lands at 8:30 am BRT, unemployment at 9:00 am BRT. The CFTC currency positioning report arrives at 4:30 pm BRT.
What would be a good surprise for Brazil today?
A budget deficit narrower than R$100bn (about US$18.6bn) and a softer labour market, with unemployment above the 5.3% prior, would support the view that the central bank can start cutting rates soon — typically bullish for Brazilian assets and the real.
Market data: RT
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Brazil runoff, Sunday, October 25: Brazil runoff start time and results schedule. Latest: Brazil runoff polls, Flávio 51%, Lula 49%.