
INDIA · ANALYSIS
Key Facts
- —What is happening The Reserve Bank of India raised its policy repo rate by 25 basis points to 5.50% on 7 October 2026 and shifted its stance to calibrated tightening.
- —Why it matters India is signalling that inflation control now takes priority over growth support, which changes the risk calculation for foreign investors in Indian bonds and equities.
- —The numbers The RBI projects fiscal year 2026-27 CPI inflation at 5.2%, with October-December 2026 inflation at 6.0%, above the upper tolerance limit.
- —Who is who Sanjay Malhotra, Governor of the Reserve Bank of India, chairs the six-member Monetary Policy Committee that made the unanimous rate decision.
- —What to watch Monthly CPI releases and the next scheduled RBI monetary policy review will determine whether another hike follows in the coming months.
- —What it means for you A US investor holding Indian bonds or equities now faces higher local yields but also the risk that further tightening reduces bond prices and pressures equity valuations.
India’s central bank raised the RBI repo rate 5.5% in October 2026, its first increase since February 2023, and shifted to a calibrated tightening stance. The move matters to US investors because it changes the return and risk profile of Indian bonds, equities and the rupee at a time when global capital is already sensitive to Federal Reserve policy.
India is the world’s most populous country and one of the largest destinations for emerging-market capital, yet its monetary policy is shaped by food prices, imported energy and a currency that remains vulnerable to the dollar. This analysis explains the October decision, its implications for investors and how it compares with Brazil and Latin America, drawing on the Asia Intelligence Brief.
Why India Hiked Now
The Reserve Bank of India (RBI), the country’s central bank, raised the policy repo rate by 25 basis points from 5.25% to 5.50% on 7 October 2026. The six-member Monetary Policy Committee (MPC) voted unanimously for the increase and unanimously decided to change the stance from neutral to calibrated tightening.
The immediate trigger was a deteriorating inflation outlook. Consumer price inflation rose to 5.54% in September 2026, and the Ministry of Statistics and Programme Implementation reported provisional September CPI inflation of 5.54%.
Food inflation reached 7.74% in September, a level that is politically sensitive in India and difficult for monetary policy to control directly. The RBI’s concern is that temporary food and energy shocks could become embedded in wages, services and inflation expectations.
The central bank projects fiscal year 2026-27 CPI inflation at 5.2%, but the October-December 2026 quarter is forecast at 6.0%. That figure matters because 6% is above the upper tolerance limit of India’s statutory inflation-targeting band.
Growth gave the RBI room to act. The central bank raised its real GDP growth forecast for fiscal year 2026-27 to 7.1%. Policymakers could prioritise price stability without responding to an immediate growth crisis.
The Numbers That Matter
The October decision changed several key policy rates. The Standing Deposit Facility rate now stands at 5.25%, while the Marginal Standing Facility rate and the Bank Rate both sit at 5.75%.
Investors must subtract expected inflation, currency depreciation and taxation to assess real returns.
The RBI’s official projections for the coming quarters are as follows:
- October-December 2026 CPI inflation: 6.0%
- January-March 2027 CPI inflation: 5.7%
- April-June 2027 CPI inflation: 5.6%
- Core inflation was projected at 4.4% for FY2026-27; the RBI’s headline CPI inflation projection was 5.2%.
Core inflation around 4.4% suggests that price pressure is not limited to volatile food categories. Higher energy and commodity prices are raising transport, manufacturing and import costs across the economy.
The RBI said near-term rate cuts were no longer appropriate. Future action would be limited to either a pause or another increase, depending on inflation and financial conditions.
The Actors and What They Want
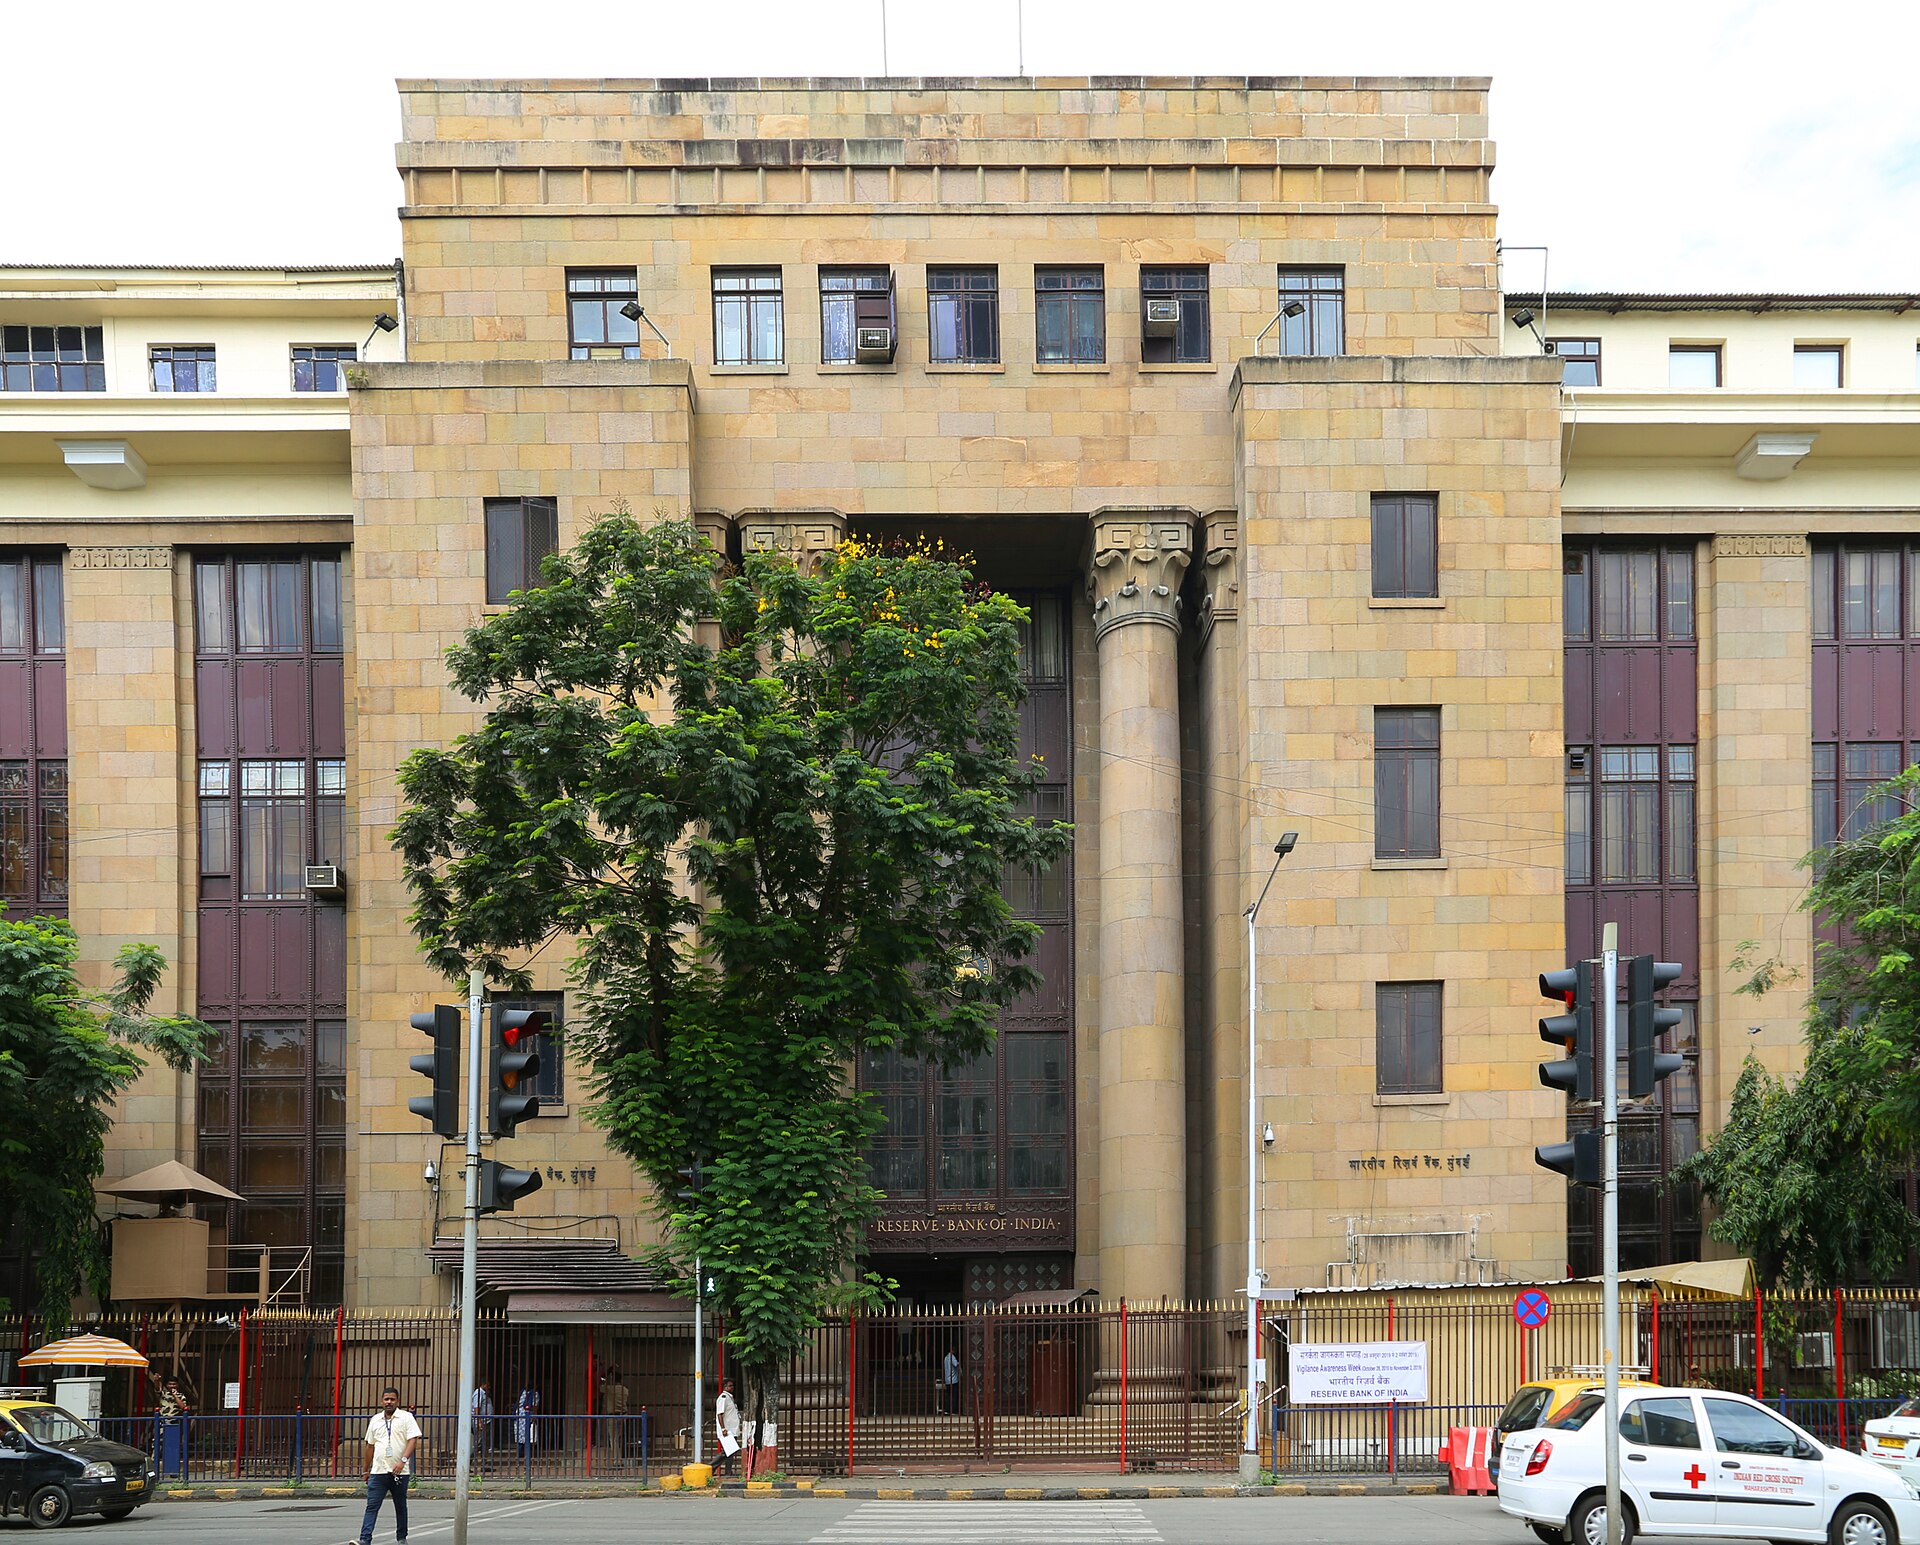
Sanjay Malhotra, Governor of the Reserve Bank of India, chairs the Monetary Policy Committee and is the public face of the decision. The RBI is India’s monetary authority, established in 1935 and nationalised in 1949, and it is responsible for price stability while supporting growth.
The MPC includes three external members, Dr. Nagesh Kumar, Saugata Bhattacharya and Professor Ram Singh, plus three RBI officials: Governor Sanjay Malhotra, Deputy Governor Dr. Poonam Gupta and Executive Director Dr. Indranil Bhattacharyya. The MPC unanimously approved a 25-basis-point repo-rate increase to 5.50%, but voted four to two to change the stance to calibrated tightening, with Dr. Nagesh Kumar and Professor Ram Singh preferring to keep it neutral.
The Ministry of Statistics and Programme Implementation publishes India’s official inflation data. Its September report showing CPI at 5.54% and food inflation at 7.74% provided the evidence base for the RBI’s shift.
For the RBI, the priority is preventing inflation expectations from drifting above the tolerance band. For the government, higher borrowing costs raise the expense of financing public debt, but the central bank’s independence means the decision was made on monetary-policy grounds.
For foreign investors, the key actor is the Federal Reserve. The interest-rate differential between the United States and India influences whether capital flows toward or away from Indian assets, regardless of the RBI’s domestic logic.
What It Means for Bonds, the Rupee and Equities
A higher repo rate raises short-term borrowing costs for Indian banks and typically transmits into higher lending rates for businesses and households. Floating-rate loans become more expensive, while banks may raise deposit rates to attract funding.
For bond investors, the effects are mixed. Short-term yields are likely to rise or remain elevated as markets price out near-term rate cuts. Long-duration bonds are vulnerable to losses if investors expect additional hikes or persistent inflation.
A US investor buying rupee-denominated debt faces currency risk. A fall in the rupee against the dollar can overwhelm the local-currency yield, and hedging that risk carries its own cost.
A higher policy rate is generally supportive of the rupee because it improves the relative return on rupee assets and signals that the RBI is willing to defend inflation credibility. However, the currency remains exposed to US dollar strength, crude-oil prices, foreign portfolio selling and India’s current-account balance.
For Indian equities, higher rates are usually a near-term headwind. They increase companies’ interest expenses, reduce the present value assigned to future earnings and make bonds relatively more competitive. Banks may initially benefit from higher lending rates, but credit demand could weaken if tightening continues.
The US and Latin America Angle
The RBI’s move should not be interpreted as an Indian version of a Fed hiking cycle. The Federal Reserve sets policy primarily for US inflation and employment, while the RBI must additionally manage a large emerging-market currency, imported energy costs, capital flows and food-price shocks.
For US investors, the practical comparison is the interest-rate differential. If US yields remain high while India raises rates only modestly, the rupee may continue to face pressure. If the Fed eases while the RBI stays restrictive, the differential becomes more favourable for Indian bonds and the currency.
India and Brazil share several emerging-market vulnerabilities: exposure to global dollar liquidity, commodity prices, foreign portfolio flows and US interest rates. However, their domestic inflation structures differ significantly.
Brazil is a major commodity exporter, while India is a major energy importer. Higher oil prices can improve Brazil’s trade position but worsen India’s import bill and inflation outlook. For Latin American investors, India offers stronger medium-term growth potential but greater sensitivity to imported energy prices.
A credible Indian tightening cycle can support the broader emerging-market asset class by demonstrating that a large central bank is willing to contain inflation. But higher global and Indian yields can also redirect capital away from riskier emerging markets, especially countries with weaker fiscal positions.
Scenarios and Risks
The most favourable scenario is a short period of restrictive policy followed by declining inflation without a major growth slowdown. In that case, Indian bonds would deliver attractive real returns and the rupee would stabilise or appreciate.
The adverse scenario is a longer tightening cycle in which bond prices fall before inflation eventually improves. If the Federal Reserve remains restrictive or global investors move toward US assets, India’s rate increase may only narrow the pressure on the rupee rather than reverse it.
A second-round food shock is a key risk. The September food-inflation rate of 7.74% means that an unfavourable harvest or further weather disruption could push headline inflation above the RBI’s projections and force additional hikes.
Over-tightening is another risk. The economy is growing rapidly, but higher borrowing costs could eventually affect housing, autos, capital expenditure and smaller businesses. The RBI must balance inflation control against the growth advantage that has made India a major destination for international capital.
The unanimous stance change indicates that future hikes will depend heavily on incoming inflation data. The committee is not locked into a predetermined path, which creates uncertainty for investors trying to position for the next move.
What It Means for You
If you hold Indian bonds, the October decision means higher local yields but also the risk of mark-to-market losses if the RBI hikes again.
If you hold Indian equities directly or through exchange-traded funds, you face a higher discount rate and potential pressure on leveraged and rate-sensitive sectors. Exporters and companies with strong pricing power are relatively better positioned.
If you hold Indian ADRs listed in the United States, your returns reflect the underlying Indian company, the rupee-dollar exchange rate, US trading conditions and ADR liquidity. The RBI decision is relevant even when you never trade on an Indian exchange.
For US investors comparing emerging markets, India now offers a clearer inflation-fighting signal than some peers. But the rupee remains exposed to the dollar and oil, and the Fed’s path will matter as much as the RBI’s.
The practical takeaway is to treat the October decision as an insurance hike. India is acting before inflation reaches the top of its tolerance band, while growth remains strong enough to absorb tighter financial conditions.
What Is Not Known
The RBI has scheduled the next MPC meeting for 2 to 4 December 2026.
The future path of the rupee cannot be predicted from the rate decision alone. It depends on Federal Reserve policy, crude-oil prices, foreign portfolio flows and India’s current-account balance, none of which are controlled by the RBI.
Whether the October hike is a one-off or the start of a tightening cycle remains unknown. The unanimous stance change suggests that the committee is aligned on how much further to go.
What to Watch
Monthly CPI inflation releases from India’s National Statistical Office will be the most important data points. If inflation stays above 5.5% or approaches 6%, another hike becomes more likely.
The next scheduled RBI monetary policy review is set for 2 to 4 December 2026. The October statement said future action would be limited to either a pause or another increase.
Food-price developments through the winter harvest season will determine whether the September food-inflation rate of 7.74% was a temporary spike or the start of a sustained pressure.
Federal Reserve policy decisions and US Treasury yields will influence the rupee and foreign portfolio flows into Indian assets. A stronger dollar would offset some of the RBI’s tightening effect.
Crude-oil prices remain a critical variable. India imports much of its energy, and a sustained rise in oil prices would worsen both inflation and the current-account balance.
Related reading: Asia Chip Selloff Tests Latin America Metals; Asia Intelligence Brief, 22 October 2026; more from Asia.
Frequently Asked Questions
Why did the RBI raise the repo rate to 5.5%?
The Reserve Bank of India raised the repo rate by 25 basis points to 5.50% on 7 October 2026 because inflation was rising toward the top of its tolerance band. September CPI inflation reached 5.54% and the RBI projected October-December inflation at 6.0%, above the upper tolerance limit.
What does calibrated tightening mean?
Calibrated tightening is the RBI’s new policy stance, adopted in October 2026. It signals that near-term rate cuts are no longer appropriate and that future action will be limited to either a pause or another increase, depending on inflation and financial conditions.
How does the RBI repo rate 5.5 affect the rupee?
A higher repo rate is generally supportive of the rupee because it improves the relative return on rupee assets and signals inflation credibility. However, the rupee remains exposed to US dollar strength, crude-oil prices and foreign portfolio flows, so the effect is not guaranteed.
What is the 10-year Indian bond yield after the hike?
Investors must subtract expected inflation, currency depreciation and taxation to assess real returns on Indian government bonds.
How does India’s rate hike compare with Brazil?
India and Brazil share emerging-market vulnerabilities to global dollar liquidity and US interest rates, but their inflation structures differ. Brazil is a major commodity exporter, while India is a major energy importer, so higher oil prices can improve Brazil’s trade position but worsen India’s inflation outlook.
Will the RBI hike rates again?
The RBI said future action would be limited to either a pause or another increase, depending on inflation and financial conditions. The unanimous stance change indicates that the committee is aligned on how much further to go, and future decisions will depend heavily on incoming inflation data.
Sources: riotimesonline.com, mospi.gov.in, mospi.gov.in, mospi.gov.in, rbidocs.rbi.org.in, moneycontrol.com. Retrieved 22 October 2026.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.