Brazil’s Financial Morning Call for Thursday, July 30, 2026
Today’s Focus
The dominant engine for Brazilian assets this morning is the rapidly improving inflation arithmetic, which all but locks in a further 25-basis-point Selic reduction at the Copom’s decision next week. The mid-July IPCA-15 inflation print, released earlier this week, landed at a whisper-thin 0.06% month-on-month, dragging the twelve-month rate down to 4.52%—comfortably inside the central bank’s tolerance band and well below every estimate in the analyst consensus.
This dovish shock has reset expectations for the speed of monetary easing, directly revaluing every stock on the B3 that is tethered to the domestic credit cycle and consumer spending. With the Selic still towering at 14.5%, the sheer height of the real rate offers a powerful protective yield for the Brazilian real, giving foreign investors a reason to look through global turbulence, provided the local fiscal story holds firm.
That fiscal test arrives at 11:30 BRT today, with the release of the June primary budget surplus and the closely watched gross debt-to-GDP ratio. The market consensus has pencilled in a deep nominal deficit of R$133.2 billion, and any widening of the 81.5% debt ratio would be a trigger for an immediate risk-premium spike, sending the real weaker and momentarily overpowering the benign inflation narrative.
While the macro maw digests these data points, the pre-market equity conversation is squarely in the banking and consumer-discretionary space, where every tick lower in the DI futures curve translates directly into lower default provisions and higher equity multiples. A clean set of fiscal numbers would be the green light for this rotation to accelerate right at the opening bell.
What matters today. Today’s market direction hinges entirely on the fiscal data: a tame debt print lets the dovish Copom trade rip through rate-sensitive stocks, while a miss triggers a swift, temporary sell-off across the board.
Today’s Economic Events
| Instrument | Level | Session |
|---|---|---|
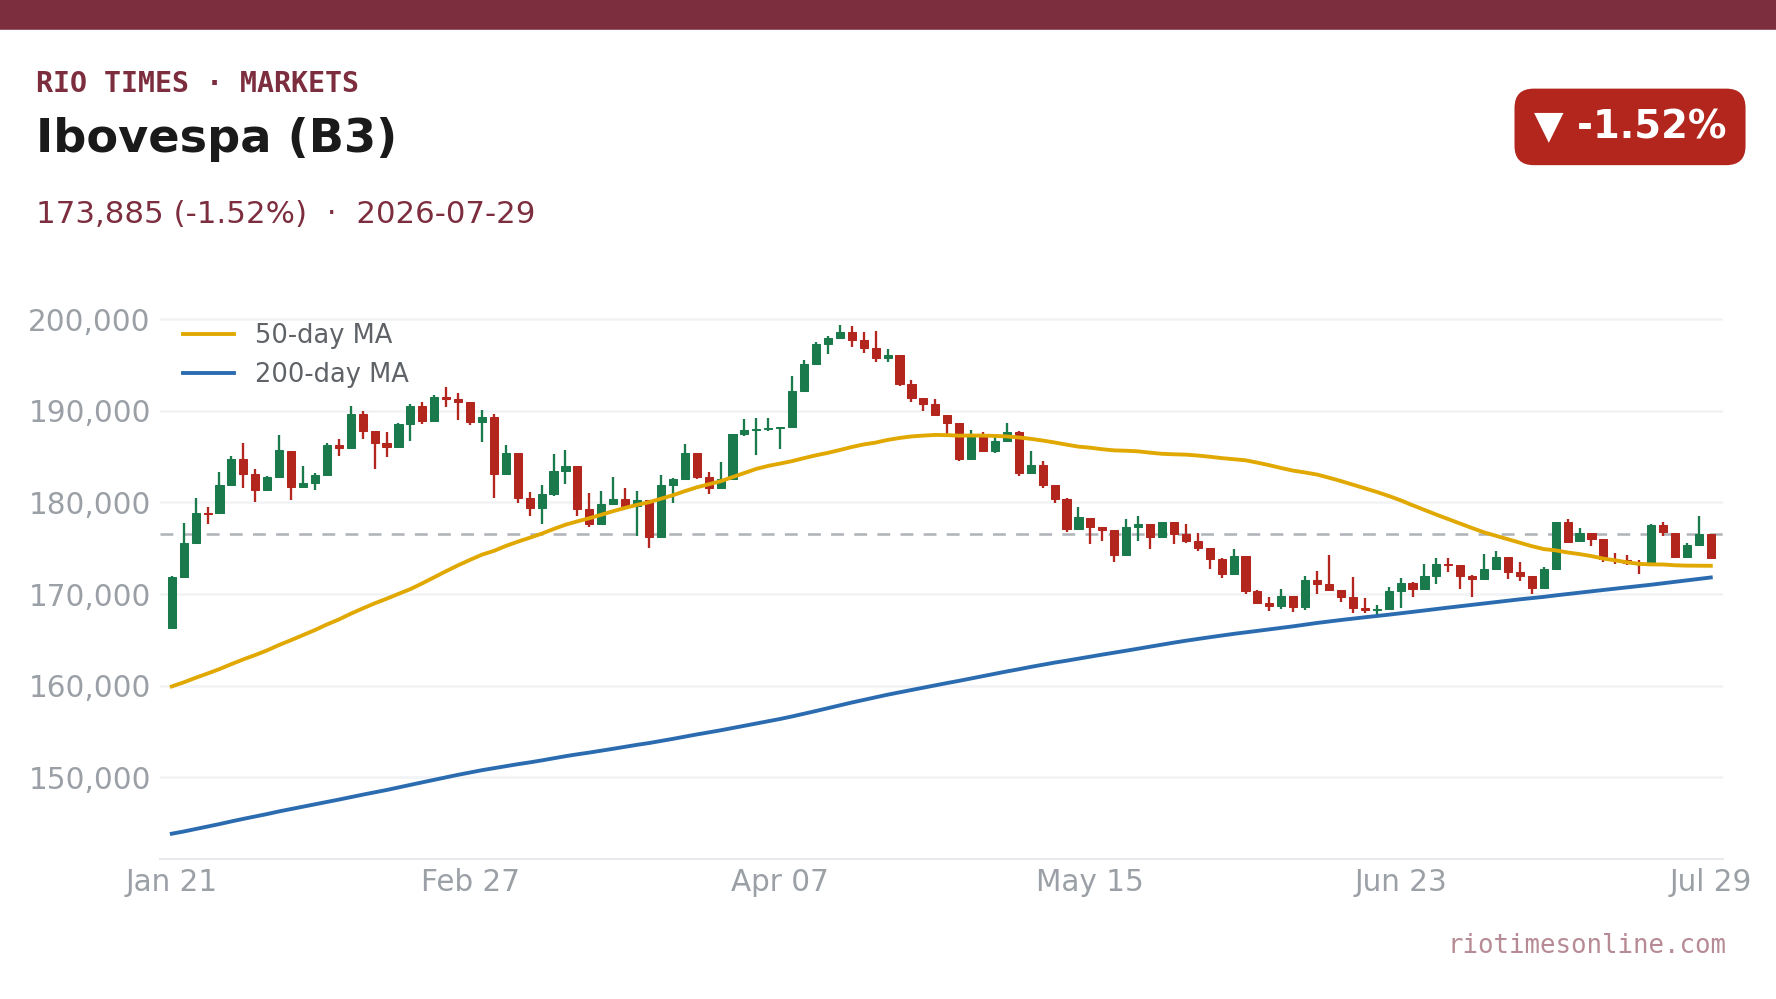
| Ibovespa (Brazil) | 173,885 | -1.52% |
| S&P 500 (US) | 7,316 | -1.52% |
| USD/BRL | 5.1174 | -0.07% |
Source: market close, 29 July 2026.
01 The setup in one read
Brazil’s B3 opens this Thursday with a distinctive tilt: the central bank’s path to lower rates is clearer than it has been for months, but a critical fiscal report card could instantly validate or vaporise the bullish mood. The mid-July IPCA-15 inflation print, landing at just 0.06% on the month, has provided a near-perfect backdrop for the rate-sensitive corner of the market, implying that the official twelve-month inflation rate is now tracking neatly back toward the 3% target. The immediate market translation is a firming of the bet that the Copom will cut the Selic, the benchmark interest rate, by another 25 basis points at its meeting that concludes next Wednesday, a move that would continue to relieve pressure on corporate Brazil’s debt-laden balance sheets.
The counterweight, as always, sits in Brasília. At 11:30 BRT, the National Treasury releases its consolidated budget figures for June, including the primary surplus and the gross debt-to-GDP ratio—the yardstick by which international investors judge Brazil’s sovereign risk. The consensus points to a chunky nominal deficit of R$133.2 billion and a debt burden ticking up to 81.5% of GDP, meaning today’s numbers are a live-wire that can either validate the carry trade or send the Brazilian real skidding, punishing importers and tightening financial conditions in a single heartbeat.
The pre-market evidence heavily favours a constructive open for domestic-oriented B3 shares, buoyed by the unambiguous disinflation surprise and its implications for a steep fall in the Selic over the next twelve months. The policy rate is simply too high relative to where inflation is heading, and the bank’s rate-cutting committee now has all the cover it needs to stay on an easing path. The real risk is a negative fiscal shock that reawakens the perennial fear that a pre-election government will lose control of the public purse, instantly repricing the long end of the yield curve and punishing both the real and leveraged equity plays. The variable to watch is the June gross debt-to-GDP ratio, which must not breach the 81.5% consensus to sustain the morning’s constructive tone.
02 Where Brazil is set to open
| Instrument | Last close | Indicated | Watch today |
|---|---|---|---|
| Ibovespa | 173,885 | Firmer bias (indicative) | Fiscal numbers & rotation into rate-sensitives |
| USD/BRL | 5.1174 | Softer bias (indicative) | Debt-to-GDP release & real-rate appeal |
The verified board shows the Ibovespa—Brazil’s main stock index—closed the last session at 173,885, while the US dollar ended at R$5.1174. This morning, B3 futures and ADR indications suggest the physical market will open a few tenths of a percentage point higher, a move animated by the irresistible pull of falling forward interest rates on equity valuations. The disinflation story is giving traders a licence to add risk, a stark contrast to the previous session when the local market was dragged lower in lockstep with a sharp sell-off on Wall Street.
The real’s indicated firmness at the open is a direct function of the towering Selic at 14.5%, a yield that remains a powerful magnet for carry-seeking capital so long as the fiscal roof doesn’t cave in. If the June debt-to-GDP ratio holds at or below the 81.5% consensus, the currency is likely to strengthen towards the R$5.10 handle, bolstered by the sheer weight of the interest-rate differential. Rio Times · Live Market Intelligence
Live Market IntelligenceBrazil Morning Call — Live Board
Brazil Morning Call — Live Board
Instrument Last Change YoY Prev. High Low Volume
IBOV
170,592.26
-2.91%
+19.56%
175,710.05
178,526
175,157
—
USD/BRL
5.34
-1.32%
-0.84%
5.42
5.42
5.30
—
EUR/BRL
5.95
+7.53%
-4.87%
5.54
6.04
5.92
—
SELIC
13.75%
—
—
—
—
—
BRENT
109.58
-5.38%
+66.99%
115.81
111.92
109.00
34,268
WTI
100.12
-1.61%
+63.30%
101.76
102.82
99.77
201,568
IRON ORE
161.91
—
+53.37%
161.91
161.91
1
GOLD
4,073
+0.85%
+1.32%
4,038
4,079
4,002
117,083
SILVER
54.49
+0.70%
+17.02%
54.11
54.64
52.71
34,428
LITHIUM
62.43
+1.89%
+5.14%
61.27
62.62
61.56
130,024
SOY
1,250
+0.70%
+17.12%
1,241
1,262
1,249
156,494
CORN
450.25
-1.04%
+5.01%
455.00
455.00
449.75
143,350
WHEAT
614.75
-0.20%
+16.87%
616.00
618.50
610.00
51,884
COFFEE
294.35
-2.19%
-24.54%
300.95
304.90
289.05
16,022
SUGAR
19.26
+0.84%
+33.20%
19.10
19.42
19.03
74,161
ORANGE JUICE
143.20
+5.45%
-26.07%
135.80
148.80
142.50
1,394
COTTON
77.90
-1.47%
+20.66%
79.06
81.07
80.01
20,308
BEEF
230.73
+0.33%
+0.83%
229.98
231.58
229.75
13,888
CATTLE
346.40
-1.00%
+0.26%
349.90
349.70
346.33
5,755
COCOA
5,581
+1.66%
-9.72%
5,490
5,622
5,444
13,619
PETR4
53.31
-1.06%
+77.70%
53.88
53.70
52.83
43,239,500
VALE3
62.88
-2.33%
+1.98%
64.38
64.43
62.80
24,652,300
SUZB3
47.14
-0.55%
-3.79%
47.40
47.84
46.10
7,151,800
KLABIN
18.73
-0.43%
+6.46%
18.81
19.04
18.45
6,051,800
SLCE3
16.97
-2.75%
+19.37%
17.45
17.77
16.94
3,109,500
ABEV3
15.40
+0.20%
+26.75%
15.37
15.68
15.31
27,307,400
ITUB4
41.42
-0.67%
+11.30%
41.70
42.60
41.15
28,160,700
BBDC4
15.69
-1.63%
-13.88%
15.95
16.30
15.67
65,766,400
BBAS3
17.59
+0.69%
-15.59%
17.47
18.31
17.51
67,844,600
B3SA3
15.27
+1.33%
+21.71%
15.07
15.78
15.20
75,282,000
WEGE3
45.78
+2.81%
+10.06%
44.53
47.08
45.06
9,823,200
PRIO3
69.21
-2.71%
+87.14%
71.14
70.98
69.15
6,663,200
RENT3
31.14
-1.67%
-20.73%
31.67
32.68
31.02
19,092,400
AZZA3
16.72
+1.15%
-42.24%
16.53
17.42
16.72
4,875,400
CSNA3
4.76
-4.99%
-47.09%
5.01
5.14
4.76
14,327,900
GGBR4
24.87
-2.28%
+36.28%
25.45
26.20
24.79
7,507,900
ENEV3
26.79
+0.45%
+49.78%
26.67
27.35
26.30
12,263,000
LREN3
9.75
+0.72%
-33.67%
9.68
10.33
9.75
29,053,800
03 On the B3 radar today — a fiscal health check and a dovish anchor
| Item | When | Why it matters |
|---|---|---|
| Gross Debt-to-GDP (June) | 11:30 BRT | Key solvency metric; a rise above 81.5% consensus triggers risk-off |
| Primary Budget Surplus (June) | 11:30 BRT | Measures the core fiscal effort before interest payments |
| Nominal Budget Balance (June) | 11:30 BRT | The all-in deficit number; seen widening to R$133.2bn |
| Unemployment Rate (June) | 12:00 BRT | A still-tight labour market could slow the pace of Copom cuts |
| BCB National Monetary Council | 12:00 BRT | Regular meeting on financial system stability regulations |
The economic calendar this Thursday is headlined by the 11:30 BRT trio of fiscal reports, which will essentially function as a stress test for the morning’s optimistic start. The primary balance will show just how wide the hole in the public accounts is before the burden of debt interest is layered on, while the nominal deficit—forecast at a deeply negative R$133.2 billion—and the gross debt ratio are the numbers that set the tone for Brazil’s credit default swaps and the real.
At noon, the unemployment rate for June provides a crucial input into the central bank’s assessment of spare capacity in the economy. The consensus expects a slight drop to 5.4%, a level still consistent with a tight services sector and sticky wage pressures, which is one reason Copom watchers are almost certain to see another quarter-point cut rather than a more aggressive 50-basis-point sprint.
04 Copom and the macro backdrop
The wager driving B3’s pre-market is remarkably clean: the Copom will trim the Selic by 25 basis points at its August meeting, and the path beyond looks dovish because the raw inflation data is crumbling faster than expected. The mid-July IPCA-15, which serves as a preview of the full month’s inflation, rose just 0.06% on the month, dragging the twelve-month rate down to 4.52% and leaving the government’s own more pessimistic forecast of 5.1% looking increasingly stale.
With the Selic at a stratospheric 14.5%, the real rate of interest—the gap between the policy rate and inflation—remains one of the highest in any major economy, offering Brazil a concrete buffer against capital flight even as global markets fret over war-induced energy costs. The balance of risks from global oil prices is particularly nuanced for Brazil: the Iran conflict pushes up fuel costs and keeps the Copom cautious, but it also represents a direct terms-of-trade gain for a net crude exporter.
The central bank’s caution is rationalised by a still-resilient economy, with first-quarter GDP expanding by 1.1% thanks to solid household consumption and a pickup in investment. This strength gives cowards to doves, suggesting that the Copom can ease steadily without fearing an imminent collapse in demand, and the consensus now points to the Selic ending the year around 12%.
05 Corporate stories to watch today
There are no large-cap earnings reports officially listed for this Thursday, but the rotation trade is powerfully active beneath the surface, directly benefiting the high-turnover names that led the previous session’s turnover dashboard. Look for continued momentum in oil champion Petrobras, which was a standout gainer in the last session with a R$1.3 billion flood of volume into its preferred shares, as the global crude shock that frightens the United States and Europe remains a direct, unvarnished cash-flow boon for Brazil’s pre-salt production machine.
In the domestic rate-sensitive lane, the deep-value case in consumer discretionary and retail is compelling after the rout detrailed in yesterday’s sell-off. Financially-levered names that feature heavily in the volume mix, such as the big Brazilian banks, are today’s primary vehicles for expressing the view that a falling Selic will shrink loan-loss provisions and steepen the net interest margin curve, making their equity deeply attractive as an opening bell play.
06 The levels to watch at the open
For the Ibovespa, the 174,500 level is the first immediate hurdle—a clean push above there on the fiscal data would turn the intraday momentum decisively bullish, with the next target at the 176,000 mark that capped previous bear-market rallies. On the downside, a breach of the 173,000 support floor, triggered by an ugly debt-to-GDP print, would signal that the macro trade has soured and that yesterday’s risk-off seepage from Wall Street has a local accelerant.
In the currency market, the USD/BRL’s dance is around a hard floor at R$5.08 and a panic ceiling at R$5.18. The day’s real rate is to follow the bond market’s lead: a rapid drop in the January 2028 DI futures contract would flood through to a stronger real, pushing the dollar towards the R$5.09 level as the yield curve bull-steepens, while any whiff of a primary deficit shock will ricochet the exchange rate straight to the R$5.15 handle.
07 What to watch
- Gross debt-to-GDP ratio: The absolute fulcrum; an uptick above 81.5% consensus will puncture the optimistic pre-market tone and flip the real weaker within seconds.
- DI futures curve: Watch the January 2028 contract for a steep flattening, which would signal the market is pricing a deeper and faster Selic cutting cycle.
- Petrobras liquidity flow: Continued heavy turnover in PETR4 will confirm whether international investors are using the oil-export theme as a safe harbour within the B3.
- Retail momentum: A rebound in heavily-shorted domestic consumer names, such as those that bled yesterday, would confirm that the rate-cut trade has genuine intraday traction.
Background: Bitcoin Steady at US$63,908 as LatAm Crypto Adoption Deepens.
Background: Gold & Silver Rise on Softer Dollar; LatAm Miners Gain.
More: Brazil news in English, every day from The Rio Times.
Frequently Asked Questions
Why are traders so sure the Copom will cut rates next week?
Because the mid-July IPCA-15 inflation print came in at just 0.06%, far below all forecasts, dragging the twelve-month inflation down to 4.52% and giving the central bank full cover to continue easing from 14.5%.
What makes today’s fiscal data so dangerous?
A gross debt-to-GDP ratio above the 81.5% consensus would reawaken fears that the government is spending recklessly in a pre-election year, pushing up long-term bond yields and crushing equity valuations.
How does the war in Iran affect Brazilian stocks?
It is a double-edged sword: higher global oil prices push up inflation and keep the Copom cautious, but they are a direct earnings windfall for big exporters like Petrobras.
Which B3 sectors are in play this morning?
Banks and domestic consumer cyclicals are the focal point for the rate-cut trade, while oil and iron-ore exporters benefit from the commodity-price backdrop triggered by geopolitical tensions.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Brazil runoff, Sunday, October 25: Brazil runoff date. Latest: Brazil runoff polls, Flávio 51%, Lula 49%.