Opening a Bank Account in Barbados as a Foreigner 2026: Banks, Documents and FX Rules
GUIDES · BARBADOS
Key Facts
- —The country Barbados is a small Caribbean island republic of 269,090 people at the 2021 census, living mainly from tourism and international business.
- —What it is A practical guide to opening a personal bank account in Barbados as a foreigner, from choosing a bank to exchange control.
- —The banks Six retail banks hold licences as of June 2026: CIBC Caribbean, First Citizens, RBC, Republic, Scotiabank and Sagicor.
- —The currency The Barbados dollar has been fixed at two to one US dollar since 1975, so conversion is simple arithmetic.
- —The catch Exchange control still applies. How you bring money in decides how easily you can take it out again.
A bank account in Barbados is within reach for most foreigners. The paperwork is heavier than at home, and the currency rules are stricter than newcomers expect.
Opening a bank account in Barbados usually takes a passport, a second ID, proof of address and a bank reference. The harder part is exchange control, a set of currency rules that still governs how money enters and leaves the island.
This guide explains which banks operate, what they ask for, what accounts cost and how the rules on foreign money work. All figures are as of September 2026 unless a different date is given.
Which banks can a foreigner use?
The Central Bank of Barbados, the island’s banking regulator, lists six licensed retail banks as of June 2026. All six are also “authorised dealers”, the only institutions allowed to buy and sell foreign currency.
- CIBC Caribbean, formerly FirstCaribbean, headquartered at Warrens in St Michael.
- First Citizens Bank (Barbados), part of a Trinidad and Tobago group.
- RBC Royal Bank (Barbados), owned by Royal Bank of Canada.
- Republic Bank (Barbados), part of Trinidad-based Republic Financial Holdings.
- Scotiabank (Barbados), owned by Canada’s Bank of Nova Scotia.
- Sagicor Bank (Barbados), part of the Sagicor financial group.
One ownership change is under way. Bermuda’s Butterfield agreed on 28 May 2026 to buy CIBC’s 91.7% stake in CIBC Caribbean for about US$1.8 billion in cash and shares. It will then bid for the remaining 8.3% held by other shareholders. Closing is expected in the first half of 2027.
Butterfield says CIBC Caribbean’s regional headquarters will stay in Barbados. For a new customer, this does not change account opening today, but the brand and some terms may change later.
Credit unions are the other option. They are member-owned savings co-operatives, supervised by the Financial Services Commission (FSC), the regulator for non-bank finance. They are covered further below.
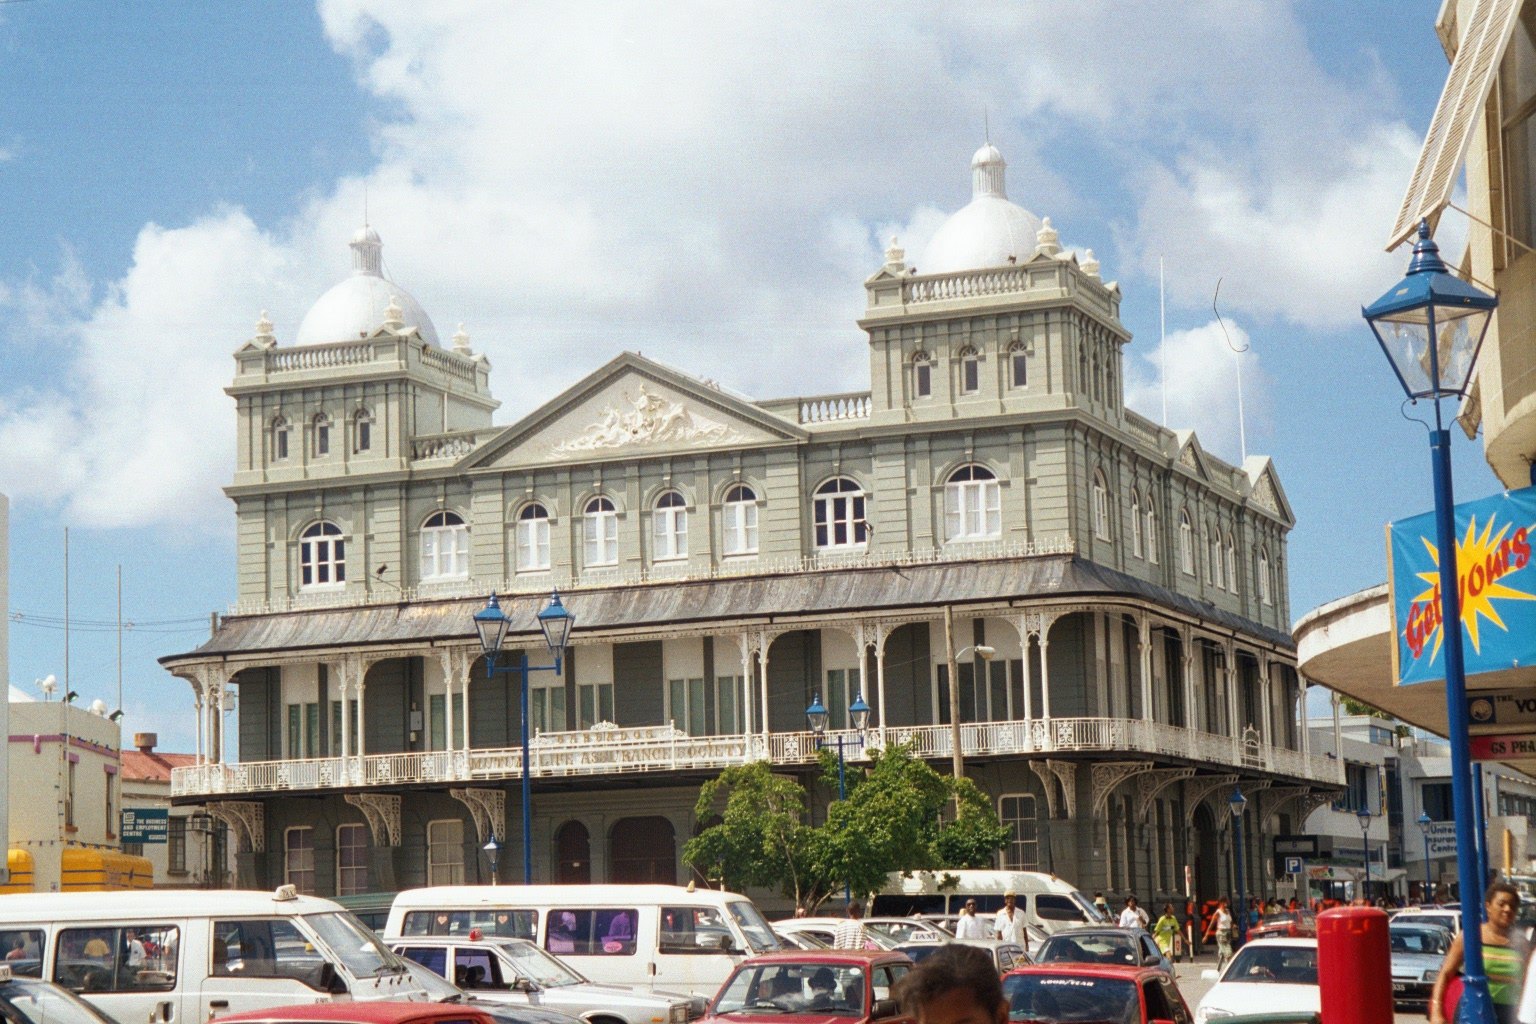
The documents banks ask for
Every bank runs “know your customer” checks, known as KYC. These are anti-money-laundering rules that require proof of who you are, where you live and where your money comes from.
Expect to bring a valid passport and usually a second photo ID. Add a utility bill or bank statement no older than three months, and a job letter or recent payslip.
Non-residents face extra steps. The table below summarises what each bank publishes on its own website.
| Bank | Extra items for non-residents |
|---|---|
| CIBC Caribbean | Banker’s reference or recent statement, two character references where applicable, proof of source of funds |
| First Citizens | Two IDs, one of them a passport, and a reference letter from your foreign bank |
| RBC | Reference letter or current statement from a reputable bank, work permit if applicable |
| Republic | Foreign banker’s reference or statement, utility bill for your permanent foreign address, work permit or CSME certificate |
| Sagicor Bank | Two IDs, banker’s reference or statement, proof of income; expats add a Welcome Stamp or work permit |
A CSME certificate is a skills certificate under the CARICOM Single Market and Economy, the Caribbean free-movement scheme. The Welcome Stamp is Barbados’s remote-work visa.
If you apply from abroad, copies must usually be certified. CIBC Caribbean accepts certification by a notary, lawyer, senior banker, certified accountant or embassy consular officer.
Every bank reserves the right to ask for more. Request the current list from the branch before you travel, including from Scotiabank, which is not in the table.
Resident or non-resident: the test that shapes your account
Barbados still runs exchange control under the Exchange Control Act, Cap. 71. The finance minister holds the power and delegates daily work to the central bank and the licensed banks.
Under these rules, a foreign national counts as resident only after three continuous years on the island. Work-permit holders never qualify. Almost every newcomer is therefore a non-resident at first.
That status is not about tax. It only decides which account type you get and how freely money can move. Tax residence follows separate rules, explained in our guide to taxes in Barbados.
A non-resident’s Barbados-dollar account is called an “external account”. The central bank treats money in it on the same basis as foreign currency. Foreign workers here under three years may have their net salary paid into it.
A foreign currency account, usually in US dollars, is the other option. Anyone can keep the full amount they bring in, and payments out of it need no central bank approval.
Bringing money in and getting it out
The central bank’s rule is simple in principle. Money you bring in through a bank can usually leave again, as long as you can prove it came from abroad.
For investments, non-residents register the incoming funds with the central bank on a form called FI, through its Forex Online portal. Keep that approval, because you must show it when you apply to send the money back.
Property is a special case. The central bank must approve a foreign purchase, and usually does when the full price is paid with money sent from abroad. Non-residents are not normally allowed to borrow locally for it, as our property guide explains.
Non-residents may use a locally issued credit card only if the balance is covered from an external or foreign currency account. Residents face annual travel allowances, such as BBD 20,000 (US$10,000) per person for holidays.
The two-to-one peg and the 2% fee
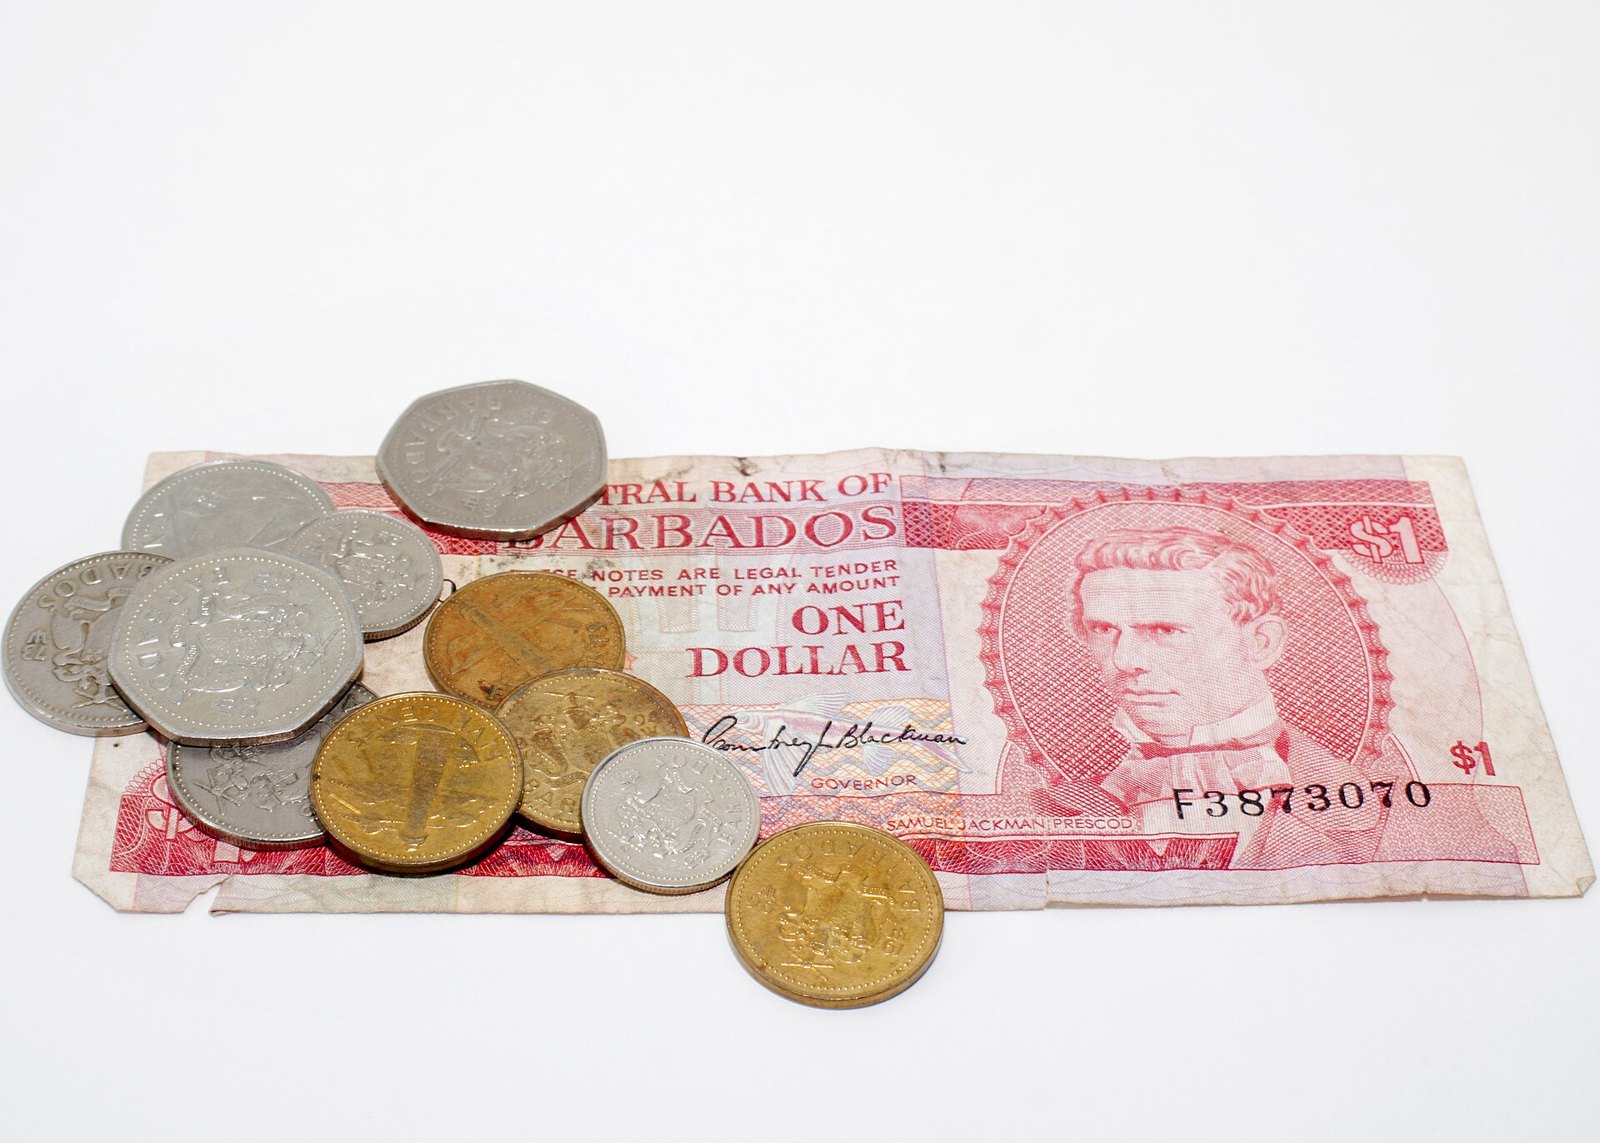
Barbados fixed its dollar at BBD 2.00 to US$1 on 5 July 1975, according to the central bank. The rate has not been changed since and still held in September 2026.
All US$ figures in this guide use that rate. A price of BBD 100 is therefore US$50, and the fixed rate removes currency risk between the two dollars.
The peg does not mean conversion is free. Since 2017, a 2% government Foreign Exchange Fee (FXF) applies when you buy foreign currency or pay abroad from a Barbados-dollar account.
The fee covers foreign cash, wires, bank drafts and card payments in foreign currency. It does not apply when you receive a wire, convert foreign money into Barbados dollars, or pay from a foreign currency account.
That is the strongest practical reason to hold a US-dollar account. Sending US$1,000 abroad from a Barbados-dollar account costs an extra US$20 in fee alone, before bank charges.
Fees and minimum balances
The central bank publishes a comparison of basic bank fees. Its latest edition, dated 31 December 2024, shows that every bank has offered a “no fee account” since September 2024.
That account carries no monthly or transaction charge. It is the cheapest starting point for a newcomer who only needs local payments.
| Bank | No-fee account: opening deposit | Cheapest chequing account: monthly fee |
|---|---|---|
| CIBC Caribbean | BBD 25 (US$12.50) | BBD 10 (US$5) |
| First Citizens | BBD 20 (US$10) | BBD 5 (US$2.50) |
| RBC | None | BBD 15 (US$7.50) |
| Republic | BBD 100 (US$50) | BBD 7.50 (US$3.75) |
| Scotiabank | None | Free |
| Sagicor Bank | None | No chequing account listed |
Using another bank’s cash machine costs BBD 3 (US$1.50) at every bank, while online banking is free. Central bank guidance caps local transfers through the RTGS interbank system at BBD 15 (US$7.50).
International wires cost more. Republic Bank’s January 2025 schedule lists BBD 70 (US$35) plus a BBD 20 (US$10) commission per international transfer, before the 2% fee.
Foreign currency accounts carry their own charges. At Republic, a US-dollar account costs US$2.50 a month, plus US$5 when the balance falls below US$100.
FATCA, CRS and the tax questions on the form
Every applicant fills in a tax self-certification form. It serves two international reporting systems that share account data between tax authorities.
FATCA, the US Foreign Account Tax Compliance Act, covers US citizens and US tax residents. Barbados signed a reciprocal agreement with the United States on 17 November 2014. Banks report US accounts through the Barbados Revenue Authority.
CRS, the Common Reporting Standard, is the OECD equivalent for most other countries. Barbados’s first CRS reporting year was 2017. Banks record your tax residence and the tax number from that country.
This does not create a new tax. It means your home tax office sees your balance and income each year, so declare them there.
Barbados residents need not give a local tax number for CRS, the revenue authority says. False statements on the form can bring fines of up to BBD 50,000 (US$25,000) or prison.
Credit unions and deposit insurance
Credit unions are member-owned. Membership depends on a “common bond”, such as an employer, profession or association, so check eligibility first.
Bank deposits are insured by the Barbados Deposit Insurance Corporation (BDIC). Cover is BBD 25,000 (US$12,500) per depositor, per bank. That is a twentieth of the US$250,000 limit in the United States.
Credit union savings have never been insured. A Protection of Depositors Bill, passed by the House of Assembly on 23 June 2026 and debated in the Senate on 8 July, would extend BDIC cover to them at the same BBD 25,000 limit.
Our report on the depositors bill has the detail. If you hold large sums, spreading them across banks keeps more of your money under the cap.
Step by step: opening the account
1. Choose the account type. Pick a Barbados-dollar account for local bills and salary, and a US-dollar account for savings and transfers abroad.
2. Ask for the checklist. Email the branch for its current non-resident list, minimum deposit and fee schedule. Ask whether it is accepting non-resident applications at all.
3. Prepare documents. Gather ID, address proof, bank reference and income proof, all dated within three months. Certify copies if you are not attending in person.
4. Fund it by wire. Send the first deposit by bank transfer from an account in your own name. Keep every credit advice, because it proves where the money came from.
5. Register investments. If the money is for property or a business, register it with the central bank. That record is your ticket to repatriation later.
What this means for you
A bank account in Barbados is realistic for foreigners with clean paperwork and a clear reason to bank there. A work permit, Welcome Stamp or local address makes approval much easier.
The peg removes currency risk against the US dollar, but not cost. Hold a US-dollar account for money that will leave the island, and keep proof of every inward transfer.
Treat fee figures here as a starting point. Check each bank’s schedule on the day you open, because tariffs change and the latest official comparison dates from December 2024.
If the bank says no: the fallback routes
Compliance departments in the Caribbean decline applications more often than applicants expect — usually for documentation gaps, occasionally for nationality or business-model risk appetite. If one bank declines you, the playbook is: ask (politely, in writing) what was missing; fix the document set; and approach the next institution with the complete stack rather than shopping the same weak file around a small market where compliance officers talk to each other. Parallel fallbacks exist: the credit unions for everyday savings once you are resident, fintech rails like Wise for inbound transfers while the account is pending, and — for corporate structures — a licensed corporate-services provider whose existing banking relationships can open doors a cold application cannot. Persistence with better paperwork succeeds far more often than escalation.
Connected Coverage
Is Barbados Safe for Expats in 2026? Crime by Area, Scams and Daily Reality
Barbados Explained: The Island, the Economy, the Republic and What to Watch
Moving to Barbados: Visas, Costs, Work Permits and Daily Life
Cost of Living in Barbados: What Expats Pay from Bridgetown to the West Coast
Taxes in Barbados for Foreign Residents
Buying Property in Barbados as a Foreigner
Retire in Barbados: Three Permit Routes
Healthcare in Barbados for Expats
Sources: Bank lists, exchange-control rules, the peg, the Foreign Exchange Fee and fee comparisons come from the Central Bank of Barbados. Account requirements come from each bank’s own website, and tax and deposit-insurance facts from the Barbados Revenue Authority, the BDIC and Butterfield.
- centralbank.org.bb – licensed commercial banks, June 2026
- centralbank.org.bb – authorised dealers
- centralbank.org.bb – exchange control FAQs
- centralbank.org.bb – Foreign Exchange Fee
- centralbank.org.bb – the 1975 peg
- centralbank.org.bb – select bank fees, December 2024
- centralbank.org.bb – bank charges guidance
- cibccaribbean.com – account opening requirements
- firstcitizensgroup.com – Barbados account opening requirements
- rbcroyalbank.com – Barbados banking accounts
- republicbarbados.com – compliance information
- republicbarbados.com – schedule of charges, January 2025
- sagicor.bank – account opening requirements
- bra.gov.bb – FATCA
- bra.gov.bb – CRS FAQs, November 2025
- bdic.org.bb – what is covered
- barbadostoday.bb – credit union deposit insurance bill
- butterfieldgroup.com – CIBC Caribbean acquisition
What Is Not Known
Whether the Protection of Depositors Bill is already law is not confirmed. It passed the House of Assembly on 23 June 2026 and was debated in the Senate on 8 July. No start date for credit union cover has been found.
How many non-resident applications banks accept or refuse is not published. Banks decide case by case, and none states an approval rate or typical waiting time.
The central bank’s fee comparison has not been updated since December 2024 on its website. Some charges may have changed since then, so each bank’s current schedule is the only reliable guide.
What will change for CIBC Caribbean customers after the Butterfield purchase is not yet known. The deal still needs approval from Butterfield shareholders and regulators.
More: Caribbean news in English, every day from The Rio Times.
Frequently Asked Questions
Can a non-resident open a bank account in Barbados?
Yes, most of the six licensed retail banks publish requirements for non-residents. Expect to show two IDs including a passport, proof of address, a reference or statement from your current bank and proof of income or source of funds. Each bank decides case by case.
Which documents do I need to open a bank account in Barbados?
You need a valid passport, usually a second photo ID, a utility bill or bank statement no older than three months, and a job letter or payslip. Non-residents add a banker’s reference, and copies sent from abroad must usually be certified by a notary, lawyer or senior banker.
Is the Barbados dollar pegged to the US dollar?
Yes. The Barbados dollar has been fixed at BBD 2.00 to US$1 since 5 July 1975, and the rate still held in September 2026. A 2% government Foreign Exchange Fee still applies when you buy foreign currency or pay abroad from a Barbados-dollar account.
Can I send money out of Barbados freely?
Money you brought in through a bank can usually leave again if you can prove where it came from. Payments from a foreign currency account need no central bank approval. Investment funds should be registered with the Central Bank of Barbados on arrival so they can be repatriated later.
How much of my deposit is insured in Barbados?
The Barbados Deposit Insurance Corporation covers up to BBD 25,000, or US$12,500, per depositor at each bank. Credit union savings are not yet covered, although a bill to extend protection to them was debated in Parliament in mid-2026.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
Read More from The Rio Times