Today’s Focus
A far softer-than-expected inflation print in Brazil is reshaping positioning as traders return to their desks this Monday. The IPCA-15 — a mid-month preview of the official inflation index — rose just 0.06% in the period to mid-July, well below every estimate in a Reuters poll and sharply down from 0.41% a month earlier, sending the 12-month rate down to 4.52% from 4.80%.
That number lands right as Copom, the Brazilian central bank’s rate-setting committee, gathers for a two-day meeting starting Tuesday. With the Selic at 14.25% after three consecutive quarter-point cuts, the tamer price data strengthens the case for another reduction, even as the bank’s own projections flag a possible re-acceleration later in the year tied to higher global oil prices.
Across the region the mood is watchful but not panicked. Colombia’s peso was the fireworks act late last week, soaring 2.46% against the dollar, while the Mexican peso and Brazilian real barely budged. The IPC in Mexico slipped 0.58%, lagging a broadly positive session on Wall Street, but the S&P 500’s 0.7% gain and the Nasdaq’s 1% jump are giving futures across Santiago, Bogotá and São Paulo a gentle lift this morning.
Today’s data calendar is thick. Chile publishes IMACEC economic activity figures, where the consensus sees a swing back to growth after a prior month’s contraction. Manufacturing PMI readings from Mexico, Colombia and Brazil will provide the first real check on factory-floor health for August. In the background, the US ISM manufacturing report — with new orders and prices paid at the heart of the current tariff and input-cost debate — will set the tone for the dollar and Treasury yields into the afternoon.
What matters today. Whether this week’s Copom decision and the accompanying statement signal a faster easing path is now the single biggest variable for the real, Brazilian equities and foreign portfolio flows.
| Instrument | Level | Session |
|---|---|---|
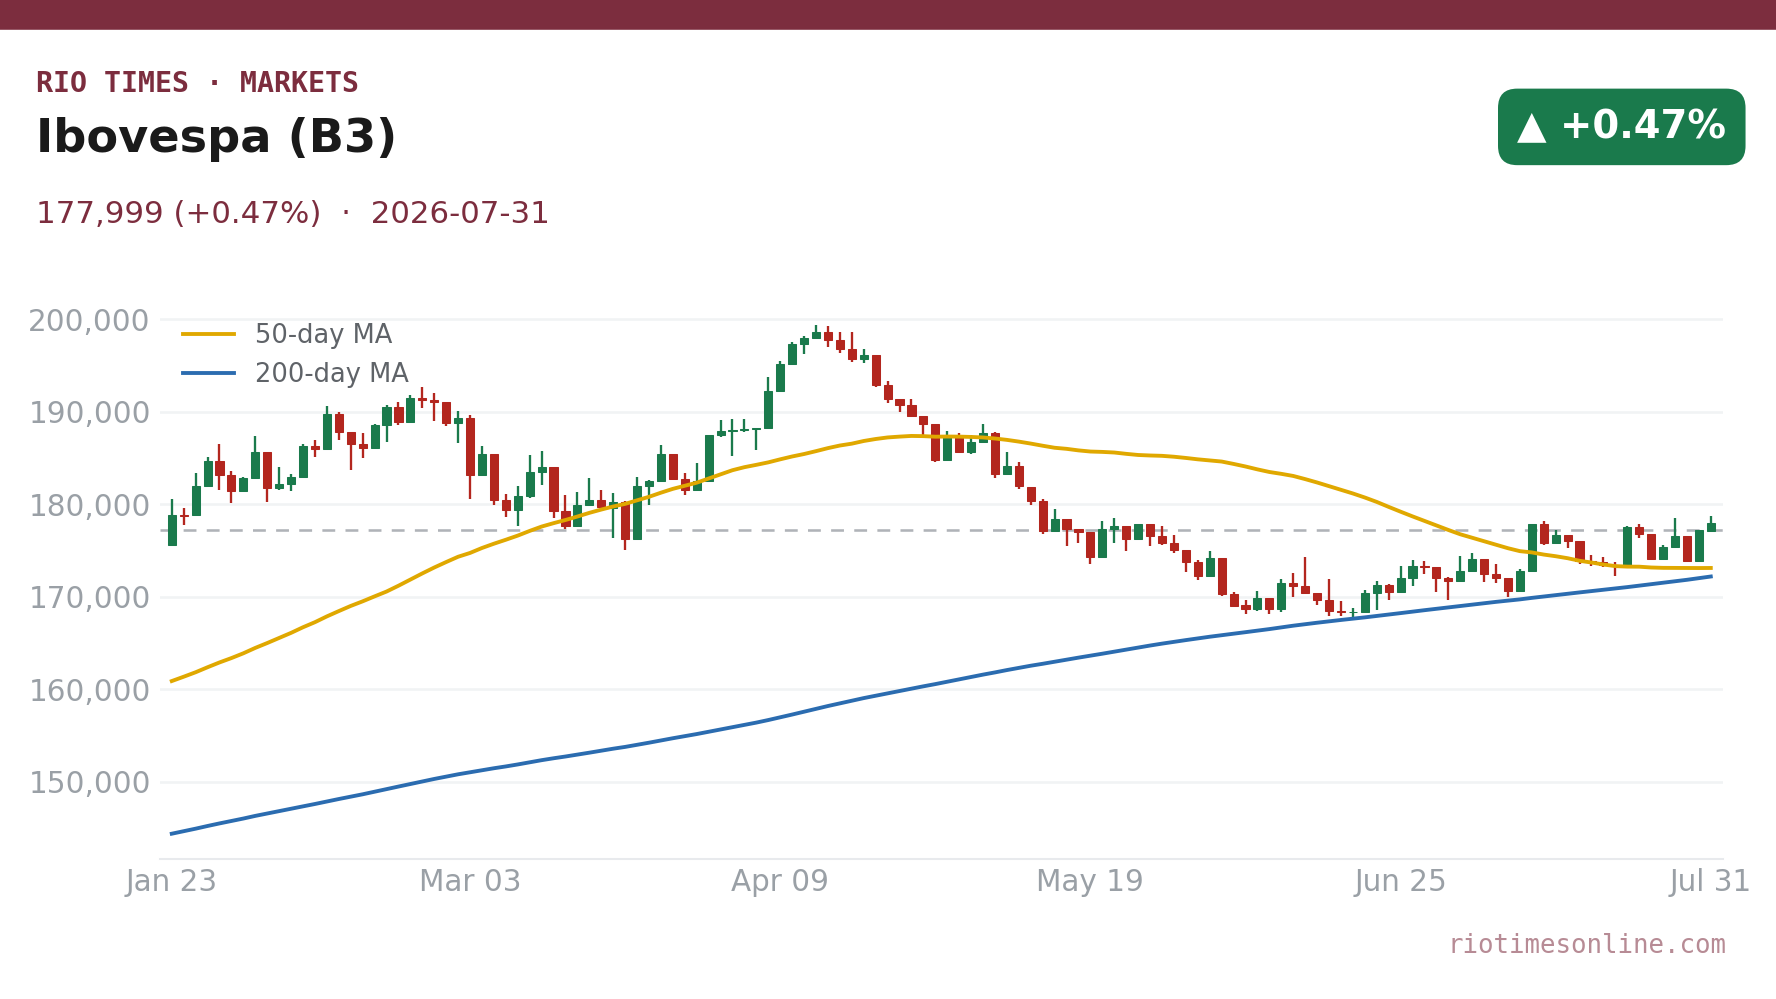
| Ibovespa (Brazil) | 177,999 | +0.47% |
| S&P 500 (US) | 7,490 | +0.70% |
| USD/BRL | 5.0754 | +0.32% |
| USD/MXN | 17.349 | +0.03% |
| USD/CLP | 931.1 | +0.54% |
| USD/COP | 3,122 | -2.46% |
| USD/ARS | 1,486 | -0.24% |
Latin American markets — Source: RT close, 2026-07-31. Figures rendered directly from the feed.
01 The overnight tape in one read
Asian equities drifted in a quiet session, with Japanese cash earnings data coming in slightly above expectations and the Bank of Japan’s policy meeting minutes offering no surprises. Chinese bourses were flat to slightly lower, offering little directional push for emerging-market traders positioned in Latin America.
European indices edged higher in early dealing, supported by German retail sales that though still negative month-on-month came in better than some feared. The Schatz auction later this morning and the broader risk-on tone after Friday’s solid Wall Street session are keeping a floor under European equities.
US futures point to a flat open, with traders in a holding pattern ahead of the ISM manufacturing PMI — the day’s marquee number. The VIX, a gauge of expected S&P 500 swings often called the fear index, fell 6.44% in the last session to 15.99, signalling a market that is comfortable, not complacent.
Gold took a genuine knock, retreating 1.33% to $4,051 an ounce, while silver dropped 2.18%. That precious-metal weakness is one of the cleaner signals that a pure haven bid is not driving the tape this morning, which tends to be supportive for higher-yielding Latin American currencies.
The evidence is tilted positively for regional risk assets this morning: Wall Street futures are steady, Brazil’s inflation surprise opens the door to a friendlier rate outlook, and the Colombian peso’s rally hints at genuine domestic conviction rather than a simple dollar-beta trade. Against that, the US 10-year Treasury yield is perched at 4.74% — higher yields in the core market still compete hard for global capital — and Mexico’s IPC is struggling for momentum well below its 52-week high. The variable to watch through the session is the US ISM manufacturing report: a print above 54, especially if the prices-paid sub-index stays hot, could reverse the dollar softness that LatAm currencies have been riding.
02 The board before the open
| Instrument | Level | Change | Read |
|---|---|---|---|
| S&P 500 | 7,490 | +0.70% | Broad risk-on close; good for EM sentiment |
| US 10Y | 4.74% | +1.35% | Yield higher; keeps pressure on rate-sensitive EM carry |
| DXY | 99.914 | +0.05% | Dollar flat; little FX direction overnight |
| Gold | $4,051 | −1.33% | Haven bid fading; supportive for LatAm currencies |
| VIX | 15.99 | −6.44% | Complacency or calm — either way, volatility is retreating |
| Ibovespa | 177,999 | +0.47% | Two straight up days; still 10.4% below its 52-week high |
| Merval | 3,291,323 | −0.41% | Argentina’s index dips despite a slightly firmer peso |
| COLCAP | 2,392 | +2.12% | Colombia’s best day in weeks, tracking the peso rally |
The table tells a story of mild but lopsided risk appetite. US equities ended the week firmly in the green, with the tech-heavy Nasdaq leading, while fixed income and havens gave back ground — the US 10-year yield pushed higher and gold fell, both moves that normally point to money rotating out of safety and into growth-sensitive assets.
For Latin America the split is instructive: the Colombian market surged across both the currency and equity board, while Brazil and Argentina posted modest moves that suggest local investors are waiting for the Copom decision and today’s activity data before committing fresh capital. Rio Times · Live Market Intelligence
Live Market IntelligenceLatin America — Cross-Market Board
Latin America — Cross-Market Board
Instrument Last Change YoY Prev. High Low Volume
IBOV
183,476.86
-0.27%
+21.85%
183,965.91
168,310
167,142
—
IPSA
11,255.90
-0.39%
—
11,299.82
11,210
10,984
1,513,213,483
IPC MEX
64,651.92
+0.60%
+12.17%
64,264.16
66,121
65,405
108,886,187
MERVAL
2,893,751
-1.57%
+30.51%
3,022,485
3,042,365
2,991,150
—
COLCAP
2,584.72
-0.95%
—
9.04
9.05
9.02
4,133
BVL PERÚ
59,934.37
+1.27%
—
—
—
—
—
USD/BRL
5.16
+0.01%
-5.13%
5.16
5.18
5.14
—
EUR/BRL
5.95
+1.01%
-5.83%
5.89
5.98
5.94
—
USD/MXN
17.06
-0.24%
-8.58%
17.10
17.08
17.01
—
USD/CLP
913.98
+0.04%
-5.67%
913.65
915.11
906.68
—
USD/COP
3,140
+0.03%
-22.04%
3,139
3,141
3,105
—
USD/PEN
3.36
-0.66%
-4.82%
3.38
3.38
3.35
—
USD/ARS
1,493
+0.10%
+12.96%
1,491
1,494
1,480
—
USD/UYU
40.27
+1.24%
+1.80%
39.77
40.27
40.23
—
USD/PYG
5,939
+1.68%
-19.54%
5,841
5,939
5,925
—
USD/BOB
11.64
-0.76%
+72.04%
11.73
11.72
11.64
—
USD/DOP
58.34
+1.25%
-3.44%
57.62
58.34
58.04
—
USD/CRC
445.92
+0.89%
-9.71%
441.97
448.50
445.92
—
03 What the data shows — B3 movers were driven by a bank rally
| Stock | Move | Turnover | Note |
|---|---|---|---|
| SANB3 | +15.2% | R$32m | Santander Brasil common; largest single-stock gain |
| SANB11 | +13.3% | R$714m | Santander Brasil units; second-highest turnover on the day |
| ALPA4 | +4.6% | R$16m | Alpargatas preferred; smaller name with sharp move |
| EZTC3 | −3.7% | R$18m | EZTec real estate; lead decliner on low turnover |
| BRAV3 | −2.9% | R$176m | Brava Energia; heavy selling on solid volume |
| PETR4 | — | R$1,085m | Petrobras preferred; the session’s most-traded name by far |
The B3 board was dominated by a single story: Santander Brasil’s shares, both the common SANB3 and the units SANB11, rocketed by double digits on heavy turnover. SANB11 alone moved R$714 million, second only to Petrobras preferred shares among the day’s most-traded instruments, indicating institutional-sized conviction behind the move rather than a speculative pop.
On the losing side, builders and energy names bore the brunt of selling. Brava Energia dropped 2.9% with R$176 million in turnover, and steelmaker Usiminas fell 2.5% as those shares changed hands to the tune of R$111 million. The overall Ibovespa rise of 0.47% masked a market where winners were concentrated in financials and a few consumer names, while the broad industrial complex stayed heavy.
04 Brazil and the currencies
The Brazilian real weakened a touch, with USD/BRL edging up 0.32% to 5.0754, but the bigger story is the inflation backdrop. The IPCA-15 mid-July print of just 0.06% — a number that blindsided forecasters — recasts the debate as Copom members gather. The Selic at 14.25% still offers one of the juiciest real yields in emerging markets, and a quicker easing path could, paradoxically, support local equities even as it narrows the carry-trade appeal that has helped the real.
The Colombian peso was the region’s standout, surging 2.46% against the dollar to 3,122. That is a muscular move by any standard and likely reflects a cocktail of month-end portfolio rebalancing, exporter dollar sales and genuine foreign demand for Colombian local-currency bonds, where yields remain elevated compared with peers.
The Mexican peso was effectively flat at 17.349 to the dollar, while the Chilean peso slipped 0.54% to 931.1 ahead of today’s IMACEC activity report. The Argentine peso firmed slightly against the official rate, but the parallel market continues to tell a different story entirely, and the Merval’s 0.41% decline suggests equity investors are not yet buying the official narrative.
Foreign flow data for Brazil remains patchy heading into the new month, but the combination of a falling VIX, a steady S&P 500 and a mid-July inflation surprise that tilts dovish for Copom ought to be a constructive backdrop for attracting fresh equity and fixed-income inflows into São Paulo this week.
05 The regional setup
| Index | Country | Change |
|---|---|---|
| Ibovespa | Brazil | +0.47% |
| COLCAP | Colombia | +2.12% |
| IPC | Mexico | −0.58% |
| IPSA | Chile | −0.13% |
| Merval | Argentina | −0.41% |
The regional board is a mixed canvas. Colombia’s COLCAP was the undisputed leader, rising 2.12% and pulling decisively away from the pack, a move that dovetails neatly with the peso’s surge and suggests domestic conviction rather than a simple risk-on beta from a sleepy summer session.
Brazil’s Ibovespa managed a second straight positive day, though the 0.47% gain felt more like treading water ahead of a big week. Mexico’s IPC, by contrast, shed 0.58% and remains the regional laggard over recent weeks, now sitting 6.5% below its 52-week high. Chile’s IPSA was barely moved, dipping 0.13%, while Argentina’s Merval gave back 0.41% — no panic, but no bid either.
06 The technical picture
Two data points stand out on the technical side. The VIX fell 6.44% to 15.99, a level that has historically been consistent with emerging-market carry trades working smoothly. When the US fear gauge is below 16, money tends to flow toward yield, and Latin America — Brazil in particular — is still a sizable beneficiary of that pattern.
The US 10-year Treasury yield ticked higher to 4.74%, not yet at a level that chokes off EM demand but one that bears watching. A break above 4.85% would start to change the calculus for the real and the Mexican peso, especially if it coincides with a dollar index pushing back above 101.
On the equity side, the Ibovespa remains 10.4% below its 52-week high of 198,657 — a deep gash that tells you the Brazilian market has already priced a fair amount of fiscal and rate uncertainty. If Copom’s statement on Wednesday signals that the easing cycle can continue without interruption, the technical gap to the recent highs gives the index plenty of room to run before hitting chart resistance.
In Colombia, the COLCAP’s 2.12% surge pushes it well off recent lows, and when a currency and an equity index move this forcefully in the same direction on the same day it usually signals genuine foreign demand rather than a passive dollar-beta bounce — a technical signal worth respecting if today’s manufacturing PMI supports the growth narrative.
07 What to watch
- Brazil IPCA-15 fallout and Copom positioning: The 0.06% mid-July print was far below consensus and changes the rate-cut calculus. Watch for any sell-side revisions to Selic forecasts and for BCB Focus survey shifts that could move the real.
- US ISM manufacturing PMI: A print above 54 with a hot prices-paid sub-index could lift the dollar and Treasury yields, instantly tightening conditions for the Mexican peso and Colombian peso which rallied late last week.
- Chile IMACEC and regional PMIs: Manufacturing PMIs from Mexico, Colombia and Brazil, plus Chile’s economic activity gauge, will test whether the real economy is keeping pace with the financial-market optimism that has lifted COLCAP and the peso.
- Colombian peso follow-through: The 2.46% surge was the region’s standout move. If USD/COP holds below 3,150 through the session it confirms genuine demand for Colombian assets and could pull the COLCAP higher still.
Frequently Asked Questions
What is the IPCA-15 and why does it matter for Copom?
The IPCA-15 is Brazil’s mid-month inflation preview, measuring consumer prices over a roughly four-week period. It serves as an early signal for the official IPCA reading that the central bank targets, and the surprisingly soft 0.06% July print makes a further Selic rate cut at this week’s Copom meeting more likely.
Why did the Colombian peso rally so much on Friday?
While no single catalyst was confirmed, a 2.46% move against the dollar points to heavy exporter selling, month-end portfolio rebalancing and strong foreign demand for Colombian local-currency bonds, where real yields remain attractive relative to regional peers.
What is the Selic and why does it matter for foreign investors?
The Selic is Brazil’s benchmark overnight interest rate, set by the central bank’s Copom committee. At 14.25% it offers one of the highest real yields in emerging markets, making the real attractive for carry trades and heavily influencing foreign flows into Brazilian equities and bonds.
How does the US ISM manufacturing number affect Latin America?
The ISM manufacturing PMI, especially its prices-paid and new-orders components, moves the dollar and US Treasury yields. A strong reading tends to lift the dollar, making it more expensive for Latin American countries to service dollar debt and often pulling capital out of emerging-market currencies.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Read More from The Rio Times