33 Companies Have Left Brazil’s B3 Exchange Since 2024
Key Facts
-
—
What happened. At least 33 companies have filed to leave Brazil’s B3 stock exchange since the start of 2024. -
—
How big. B3’s spot market now lists about 358 companies, down from 416 two years ago and the fewest since 2021. -
—
What it means. Most exits are take-private buyouts, with controlling shareholders repurchasing shares while stock prices sit depressed. -
—
Who it affects. Named departures include Santos Brasil, Wilson Sons, Carrefour Brasil, ClearSale and BRF, which merged into Marfrig. -
—
The catch. Brazil’s Ibovespa keeps hitting record highs even as the roster of listed companies keeps shrinking. -
—
What comes next. Analysts expect more buyouts while Brazil’s Selic rate, near 15%, keeps public listings unattractive.
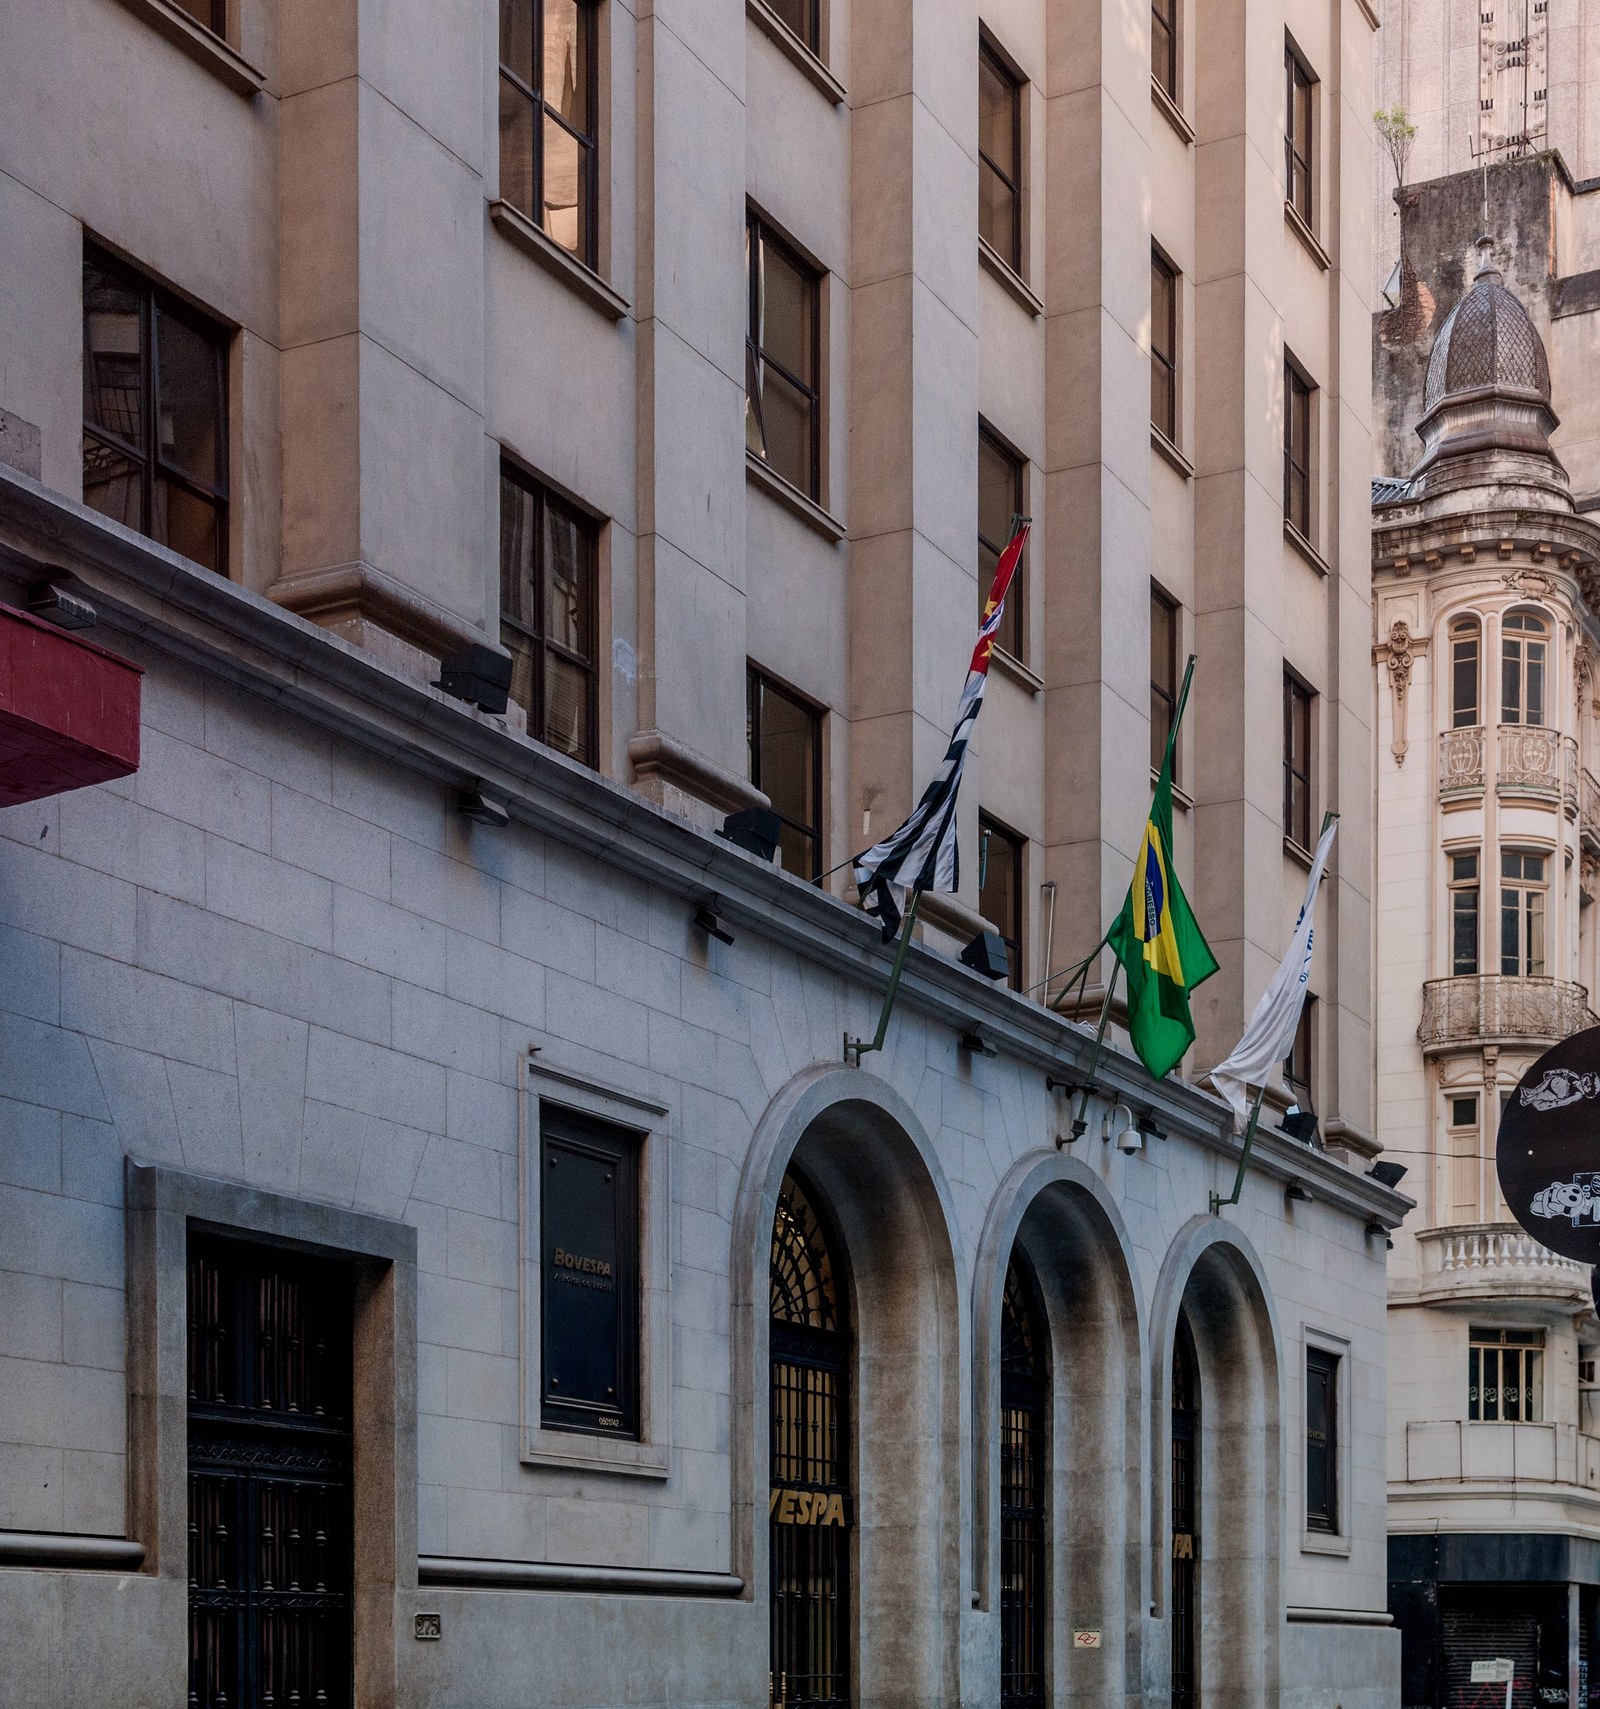
Brazil’s stock exchange is shrinking even as its main index sets records. At least 33 companies have filed to leave B3 since the start of 2024, part of a broad delisting wave.
The exodus has pulled the bourse’s roster down to its smallest size in four years. It shows no clear sign of reversing soon.
B3’s spot market now counts roughly 358 listed companies, according to data cited in Brazilian financial media. That is down from 416 just two years earlier and matches levels last seen in 2021.
Who Has Left
The 2025 exit list reads like a roll call of household Brazilian brands. Port operator Santos Brasil left after French shipping giant CMA CGM pushed its stake above 93%.
Wilson Sons followed a similar path, taken private after Switzerland’s MSC lifted its ownership to nearly 98%. Carrefour Brasil exited once its French parent moved to unify governance under full ownership.
Fraud-prevention firm ClearSale was absorbed by Serasa Experian in a merger valued at R$10.56 (US$2.05) per share. Meatpacker BRF combined with rival Marfrig, continuing to trade under a new ticker instead of its old one.
JBS, Brazil’s biggest meat processor, relocated its primary listing to United States markets entirely. It still trades in São Paulo, but now through depositary receipts rather than ordinary shares.
More departures are already lined up. Airline holding company Gol has flagged plans for a U.S. listing paired with a B3 exit.
BTG Pactual has separately moved to fully absorb Banco Pan, the consumer lender in which it already holds a 77% stake. That deal would remove one more familiar ticker from the exchange.
Iberdrola’s offer to buy out Neoenergia at R$32.50 (US$6.31) per share remains pending as well. If completed, it would remove another major utility from the local exchange.
Why Companies Are Leaving
Analysts point first to Brazil’s benchmark interest rate, the Selic, sitting near 15% annually. High rates depress equity valuations and make debt financing relatively more attractive than issuing new shares.
“When a company trades at discounted prices with minimal investor interest, controlling shareholders choose to buy back equity and delist.”
That is how Felipe Corleta, an analyst at Brazil Wealth, describes the pattern now dominating B3’s exit list. Cheap valuations, he notes, make buyouts unusually affordable for controlling families.
A controlling family or foreign parent can often regain full ownership for a fraction of what the business might otherwise be worth. Minority shareholders, meanwhile, are left to accept a buyout price or hold illiquid stock.
Guilherme Almeida, of advisory firm A&M Performance, points to a second driver: compliance costs. Governance, auditing and disclosure requirements fall disproportionately hard on mid-sized listed companies compared with giants like Petrobras or Vale.
John Murillo, of financial technology firm B2BROKER, frames it more bluntly. He calls opening capital in Brazil today “expensive, complex and risky” relative to the perceived payoff of staying public.
The IPO pipeline that might replace departing companies has also gone quiet. Brazil’s last real listing boom came in 2020 and 2021, and that window has stayed largely shut since.
Live Market IntelligenceBrazil — Live Market Board
Rio Times · Live Market Intelligence
Brazil — Live Market Board
+0.54%
186,502.64
+0.54%
63,570.30
-1.01%
11,322.60
-0.17%
3,079,779
-0.16%
2,567.27
-0.81%
58,641.32
-0.25%
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IBOV | 186,502.64 | +0.54% | +21.85% | 185,500.88 | 168,310 | 167,142 | — |
| USD/BRL | 5.16 | +0.01% | -5.13% | 5.16 | 5.18 | 5.14 | — |
| SELIC | 14.00% | — | — | — | — | — | |
| PETR4 | 41.64 | -0.05% | +35.19% | 41.66 | 41.97 | 41.15 | 41,499,400 |
| VALE3 | 72.97 | +0.83% | +30.75% | 72.37 | 73.54 | 72.66 | 17,658,000 |
| ITUB4 | 38.60 | -1.03% | +4.57% | 39.00 | 39.34 | 38.39 | 29,487,800 |
| BBDC4 | 16.85 | +0.36% | +3.50% | 16.79 | 16.90 | 16.67 | 19,416,900 |
| BBAS3 | 19.37 | +0.47% | +0.73% | 19.28 | 19.44 | 19.16 | 11,069,200 |
| B3SA3 | 14.26 | -0.21% | +12.73% | 14.29 | 14.47 | 14.11 | 33,037,800 |
| ABEV3 | 14.89 | -0.80% | +21.91% | 15.01 | 15.07 | 14.81 | 16,453,100 |
| WEGE3 | 47.59 | +0.49% | +29.99% | 47.36 | 48.08 | 47.36 | 3,364,600 |
| PRIO3 | 59.14 | -0.19% | +50.67% | 59.25 | 59.81 | 58.74 | 3,325,600 |
| SUZB3 | 41.33 | +2.35% | -23.55% | 40.38 | 41.48 | 40.35 | 3,914,900 |
| RENT3 | 34.68 | -0.09% | +0.84% | 34.71 | 34.96 | 34.35 | 7,979,100 |
| AZZA3 | 15.89 | -2.63% | -53.76% | 16.32 | 16.42 | 15.82 | 1,330,300 |
| CSNA3 | 4.30 | +0.47% | -42.65% | 4.28 | 4.41 | 4.26 | 10,076,100 |
| GGBR4 | 24.69 | +2.19% | +51.38% | 24.16 | 24.85 | 24.18 | 7,047,600 |
| ENEV3 | 24.21 | -1.38% | +70.49% | 24.55 | 24.64 | 23.99 | 9,297,000 |
A Paradoxical Bull Market
None of this has stopped the Ibovespa index from climbing to record territory. Analysts attribute the rally to concentrated foreign buying in a handful of blue-chip names rather than broad market strength.
Petrobras, Vale and Brazil’s largest banks continue to draw international capital. Smaller and mid-cap companies, by contrast, often trade at valuations their own controlling shareholders consider too cheap to leave listed.
Data from FGV and the Brazilian association of publicly traded companies, Abrasca, has tracked this divergence for several years running. Their research covers roughly 270 major companies and shows financing increasingly shifting toward debt instruments over equity.
Debentures and other credit instruments have grown steadily more popular with Brazilian corporate treasurers. Executives often see them as cheaper and less burdensome than a public listing, even at today’s elevated interest rates.
What It Means for Brazilian Markets
Brazil’s regulator, the CVM, introduced a lighter-touch listing regime called FÁCIL in mid-2025, aimed partly at reversing the trend. It is meant to lower the compliance burden for companies considering an initial public offering.
Whether it succeeds remains an open question. Culturally, Brazilian companies and households alike still favor fixed income and debt over stock ownership, unlike markets such as the United States.
American households hold stocks widely, in part through retirement accounts tied to workplace savings plans. Brazil has no equivalent tradition, leaving equities a smaller part of everyday financial life.
Until that changes, market watchers expect the current pattern to hold. Take-private deals will likely keep outpacing new listings, and B3’s company count may shrink further before it grows again.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
In depth
Read More from The Rio Times