Lithium Slips as Supply Surplus Looms over EV Demand
Key Facts
- Lithium ETF closed lower the Global X Lithium & Battery Tech ETF (LIT) settled at US$73.77, down just 0.03% on Wednesday, September 9, 2026.
- Albemarle led the decline Albemarle shares dropped 2.82% to US$125.91, the sharpest fall among the lithium names tracked by The Rio Times.
- SQM held relatively firm Chile’s SQM finished at US$75.46, a modest 0.26% decline on the day.
- Chinese carbonate weakened battery-grade lithium carbonate in China fell to 145,750 CNY per tonne, down 0.68% from the previous session.
- Spodumene fell harder spodumene concentrate SC6 CIF dropped 2.7% to an average 2,130 USD per tonne versus the prior period.
- Supply narrative dominates expectations of rising Australian output are offsetting concerns about Chinese supply and reinforcing a projected decade-long surplus.
Today’s Focus
The lithium complex drifted lower on Wednesday, September 9, 2026, but the moves were uneven. The LIT ETF tracked by investors as a proxy for lithium miners and battery technology firms dipped only 0.03% to US$73.77, while Albemarle slid 2.82% to US$125.91 and SQM eased 0.26% to US$75.46.
The softness matched physical market signals. Battery-grade lithium carbonate in China fell 0.68% to 145,750 CNY per tonne, while spodumene concentrate SC6 CIF slumped 2.7% to an average 2,130 USD per tonne, a tangible sign that miners are accepting lower prices for hard-rock feedstock.
The driver is a familiar one: supply. Commentary in the Chinese market stressed that major producers are expected to keep ample volumes flowing, and that rising Australian output is offsetting any lingering concern about Chinese restrictions or disruptions.
For Latin America, the lithium triangle remains the strategic heart of the trade. Chile’s SQM held up better than Albemarle, but the broad direction still points to a market that is pricing in too much supply rather than too little demand.
What matters today. The lithium price is being pulled down by expected Australian and Chinese supply growth, not by weak electric-vehicle battery demand.
01 The session in one read
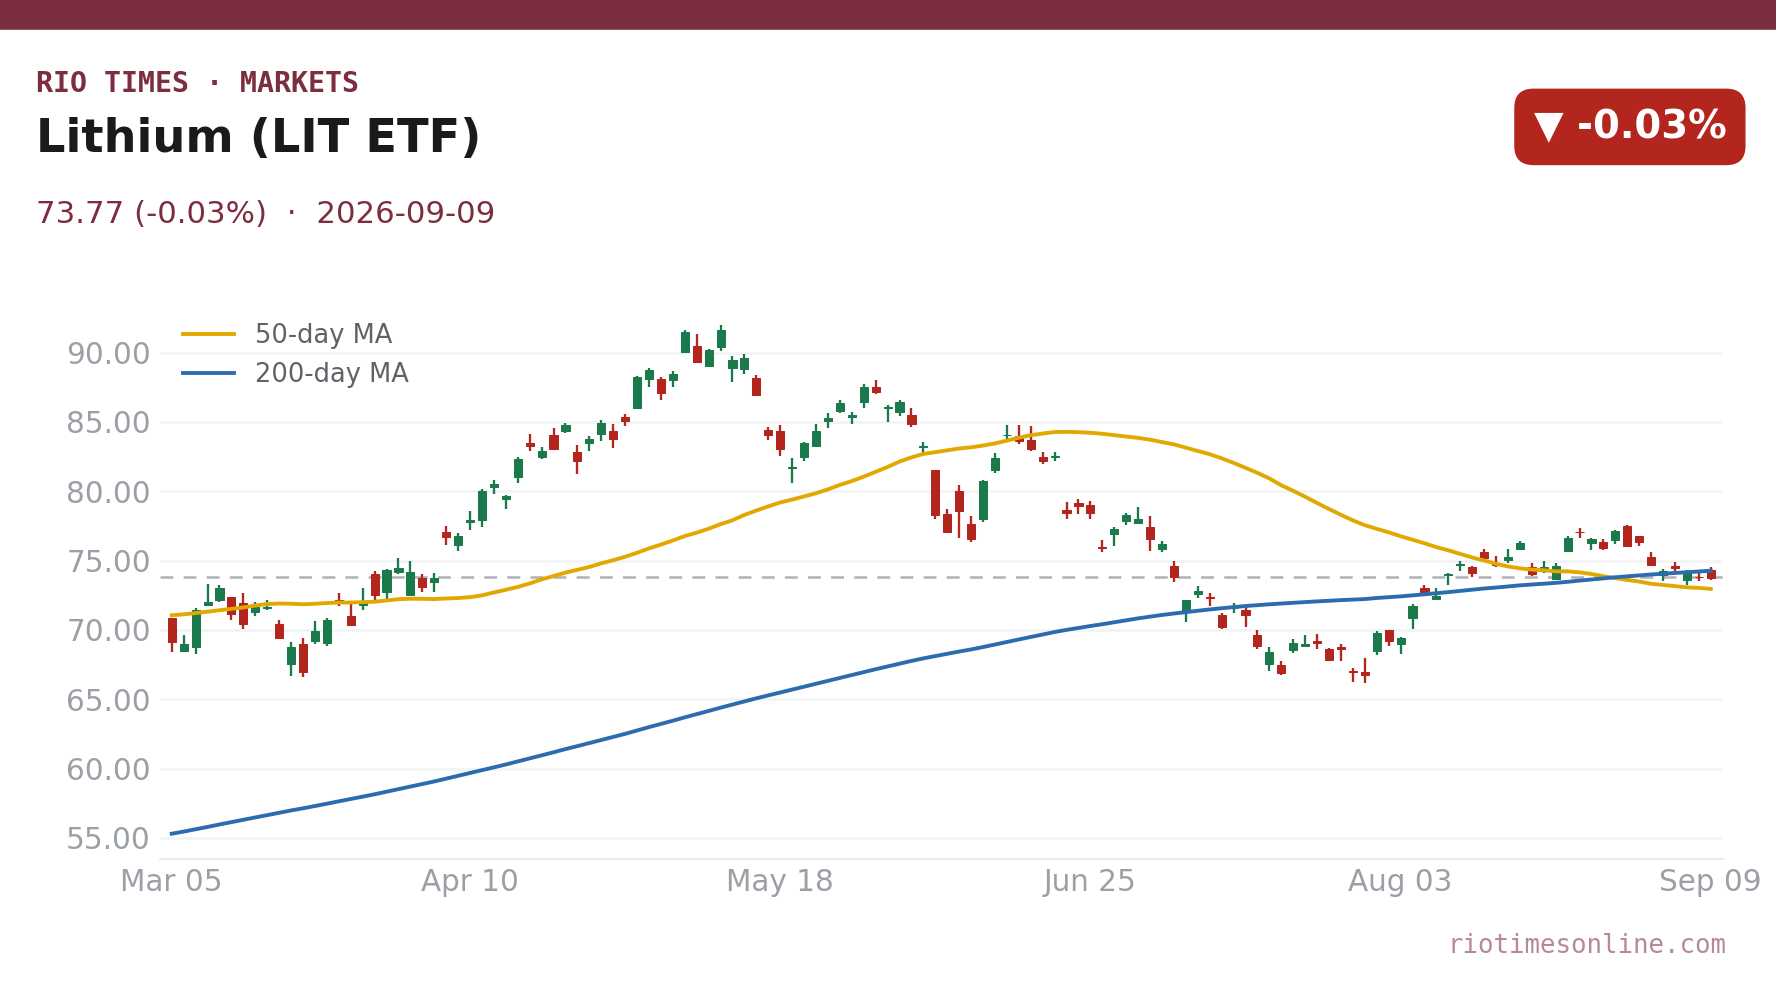
The lithium trade ended Wednesday, September 9, 2026, in a cautious mood. The LIT ETF, a basket of lithium miners and battery technology companies, closed at US$73.77, a fractional 0.03% decline.
Albemarle, the world’s largest lithium producer by market value, fell 2.82% to US$125.91. Chile’s SQM held up far better, slipping only 0.26% to US$75.46.
02 The board
The price board showed a modest but telling divergence. LIT’s nearly flat close disguised sharper weakness in Albemarle, which is more directly levered to spot lithium chemicals than the broader ETF.
Physical benchmarks reinforced the cautious tone. Battery-grade lithium carbonate in China averaged 145,750 CNY per tonne, down 0.68% on the day, while battery-grade lithium hydroxide CIF China, Japan and South Korea slipped 0.1 USD per kg to 17.55 USD.
| Asset | Level | Change |
|---|---|---|
| Lithium (LIT ETF) | US$73.77 | -0.03% |
| Albemarle | US$125.91 | -2.82% |
| SQM | US$75.46 | -0.26% |
Trade date: Wednesday 9 September 2026. Source: RT close, 2026-09-09. Where a commodity has no spot feed, an exchange-traded tracker or leading producer is shown as a labelled proxy.
Live Market IntelligenceThe live market board
Rio Times · Live Market Intelligence
Latin America — Cross-Market Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IBOV | 165,528.92 | -1.42% | +19.56% | 167,921.80 | 178,526 | 175,157 | — |
| IPSA | 10,365.73 | -0.09% | — | 10,375.55 | 10,722 | 10,633 | — |
| IPC MEX | 70,184.33 | +0.58% | +12.74% | 69,779.20 | 70,008 | 69,383 | 49,372,306 |
| MERVAL | 2,848,945 | — | +12.65% | 2,859,051 | — | — | — |
| COLCAP | 2,527.66 | +1.47% | — | — | — | — | — |
| USD/BRL | 5.34 | -1.32% | -0.84% | 5.42 | 5.42 | 5.30 | — |
| EUR/BRL | 5.95 | +7.53% | -4.87% | 5.54 | 6.04 | 5.92 | — |
| USD/MXN | 18.69 | +0.62% | +1.45% | 18.57 | 18.69 | 18.54 | — |
| USD/CLP | 983.47 | -0.57% | +5.64% | 989.13 | 991.87 | 979.07 | — |
| USD/COP | 3,149 | +3.06% | -18.02% | 3,056 | 3,173 | 3,111 | — |
| USD/PEN | 3.45 | +0.17% | +3.85% | 3.44 | 3.45 | 3.44 | — |
| USD/ARS | 1,537 | -0.28% | +3.77% | 1,541 | 1,541 | 1,537 | — |
| USD/UYU | 40.21 | +3.57% | +2.29% | 38.83 | 40.21 | 40.08 | — |
| USD/PYG | 5,803 | +3.78% | -16.54% | 5,592 | 5,803 | 5,735 | — |
| USD/BOB | 11.97 | +4.93% | +77.92% | 11.41 | 11.97 | 11.82 | — |
| USD/DOP | 60.54 | +1.83% | -4.34% | 59.45 | 61.14 | 59.85 | — |
| USD/CRC | 451.24 | +2.13% | -7.80% | 441.83 | 451.40 | 450.04 | — |
| USD/GTQ | 7.64 | +3.23% | +2.18% | 7.40 | 7.64 | 7.64 | — |
03 What moved it
The main pressure came from raw material supply. Spodumene concentrate SC6, the hard-rock lithium ore that feeds Chinese converters, fell 2.7% to an average 2,130 USD per tonne, a larger drop than the refined chemical.
Chinese market commentary pointed squarely at Australia. Investors are becoming more confident that rising Australian output will arrive just as Chinese producers keep their own volumes ample.
That combination is reinforcing expectations of a persistent lithium surplus through the rest of the decade, even with electric-vehicle sales and battery installations still growing.
04 The Latin American read
For the lithium triangle of Chile, Argentina and Bolivia, the supply story cuts both ways. Chile’s SQM held up better than Albemarle on Wednesday, but the direction of travel is not bullish for brine producers either.
Argentina’s emerging lithium projects and Bolivia’s still-nascent ambitions both sit inside a global market that is discounting future oversupply. Lower spodumene prices also reduce the incentive for new hard-rock projects outside the triangle.
05 The names to watch
Albemarle remains the most sensitive listed name to the surplus narrative. Its 2.82% drop to US$125.91 was the clearest signal on the board that equity investors are trimming exposure to lithium producers right now.
SQM showed relative resilience at US$75.46, down just 0.26%, perhaps reflecting its lower-cost brine operations and long-term contracts. LIT, as a diversified basket, sat between the two, down only 0.03% to US$73.77.
06 The outlook
The lithium market is currently trading on supply forecasts rather than demand fears. If Australian shipments disappoint, the surplus narrative could unwind quickly, but for now the physical benchmarks are still pointing lower.
Investors should focus on whether spodumene prices stabilise. That is the clearest early indicator of whether hard-rock supply growth is arriving as scheduled or falling short.
07 What to watch
- Australian spodumene shipments: The most direct test of the oversupply thesis driving lithium prices lower.
- Chinese carbonate premium: A narrowing gap between battery-grade and industrial-grade carbonate would signal weaker downstream buying.
- SQM vs Albemarle spread: Divergence between brine and hard-rock producers reveals which supply source investors fear most.
- LIT after-hours indication: Any meaningful move after the close may preview the next session’s direction for lithium equities.
Frequently Asked Questions
Why did lithium stocks fall on Wednesday?
Physical lithium benchmarks fell, led by a 2.7% drop in spodumene concentrate, on expectations of rising Australian supply.
Is this about weak electric-vehicle demand?
No. The market commentary points to ample supply from Australia and China, not falling battery or EV demand.
Why did Albemarle fall more than SQM?
Albemarle is more directly exposed to spot lithium chemical prices, while SQM benefits from lower-cost brine and long-term contracts.
What is LIT?
LIT is the Global X Lithium & Battery Tech ETF, which tracks a basket of lithium miners and battery technology companies rather than the physical commodity.
Market data: RT
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.