Kenya Startup Funding Slows Sharply as Investors Pivot to Quality Over Quantity
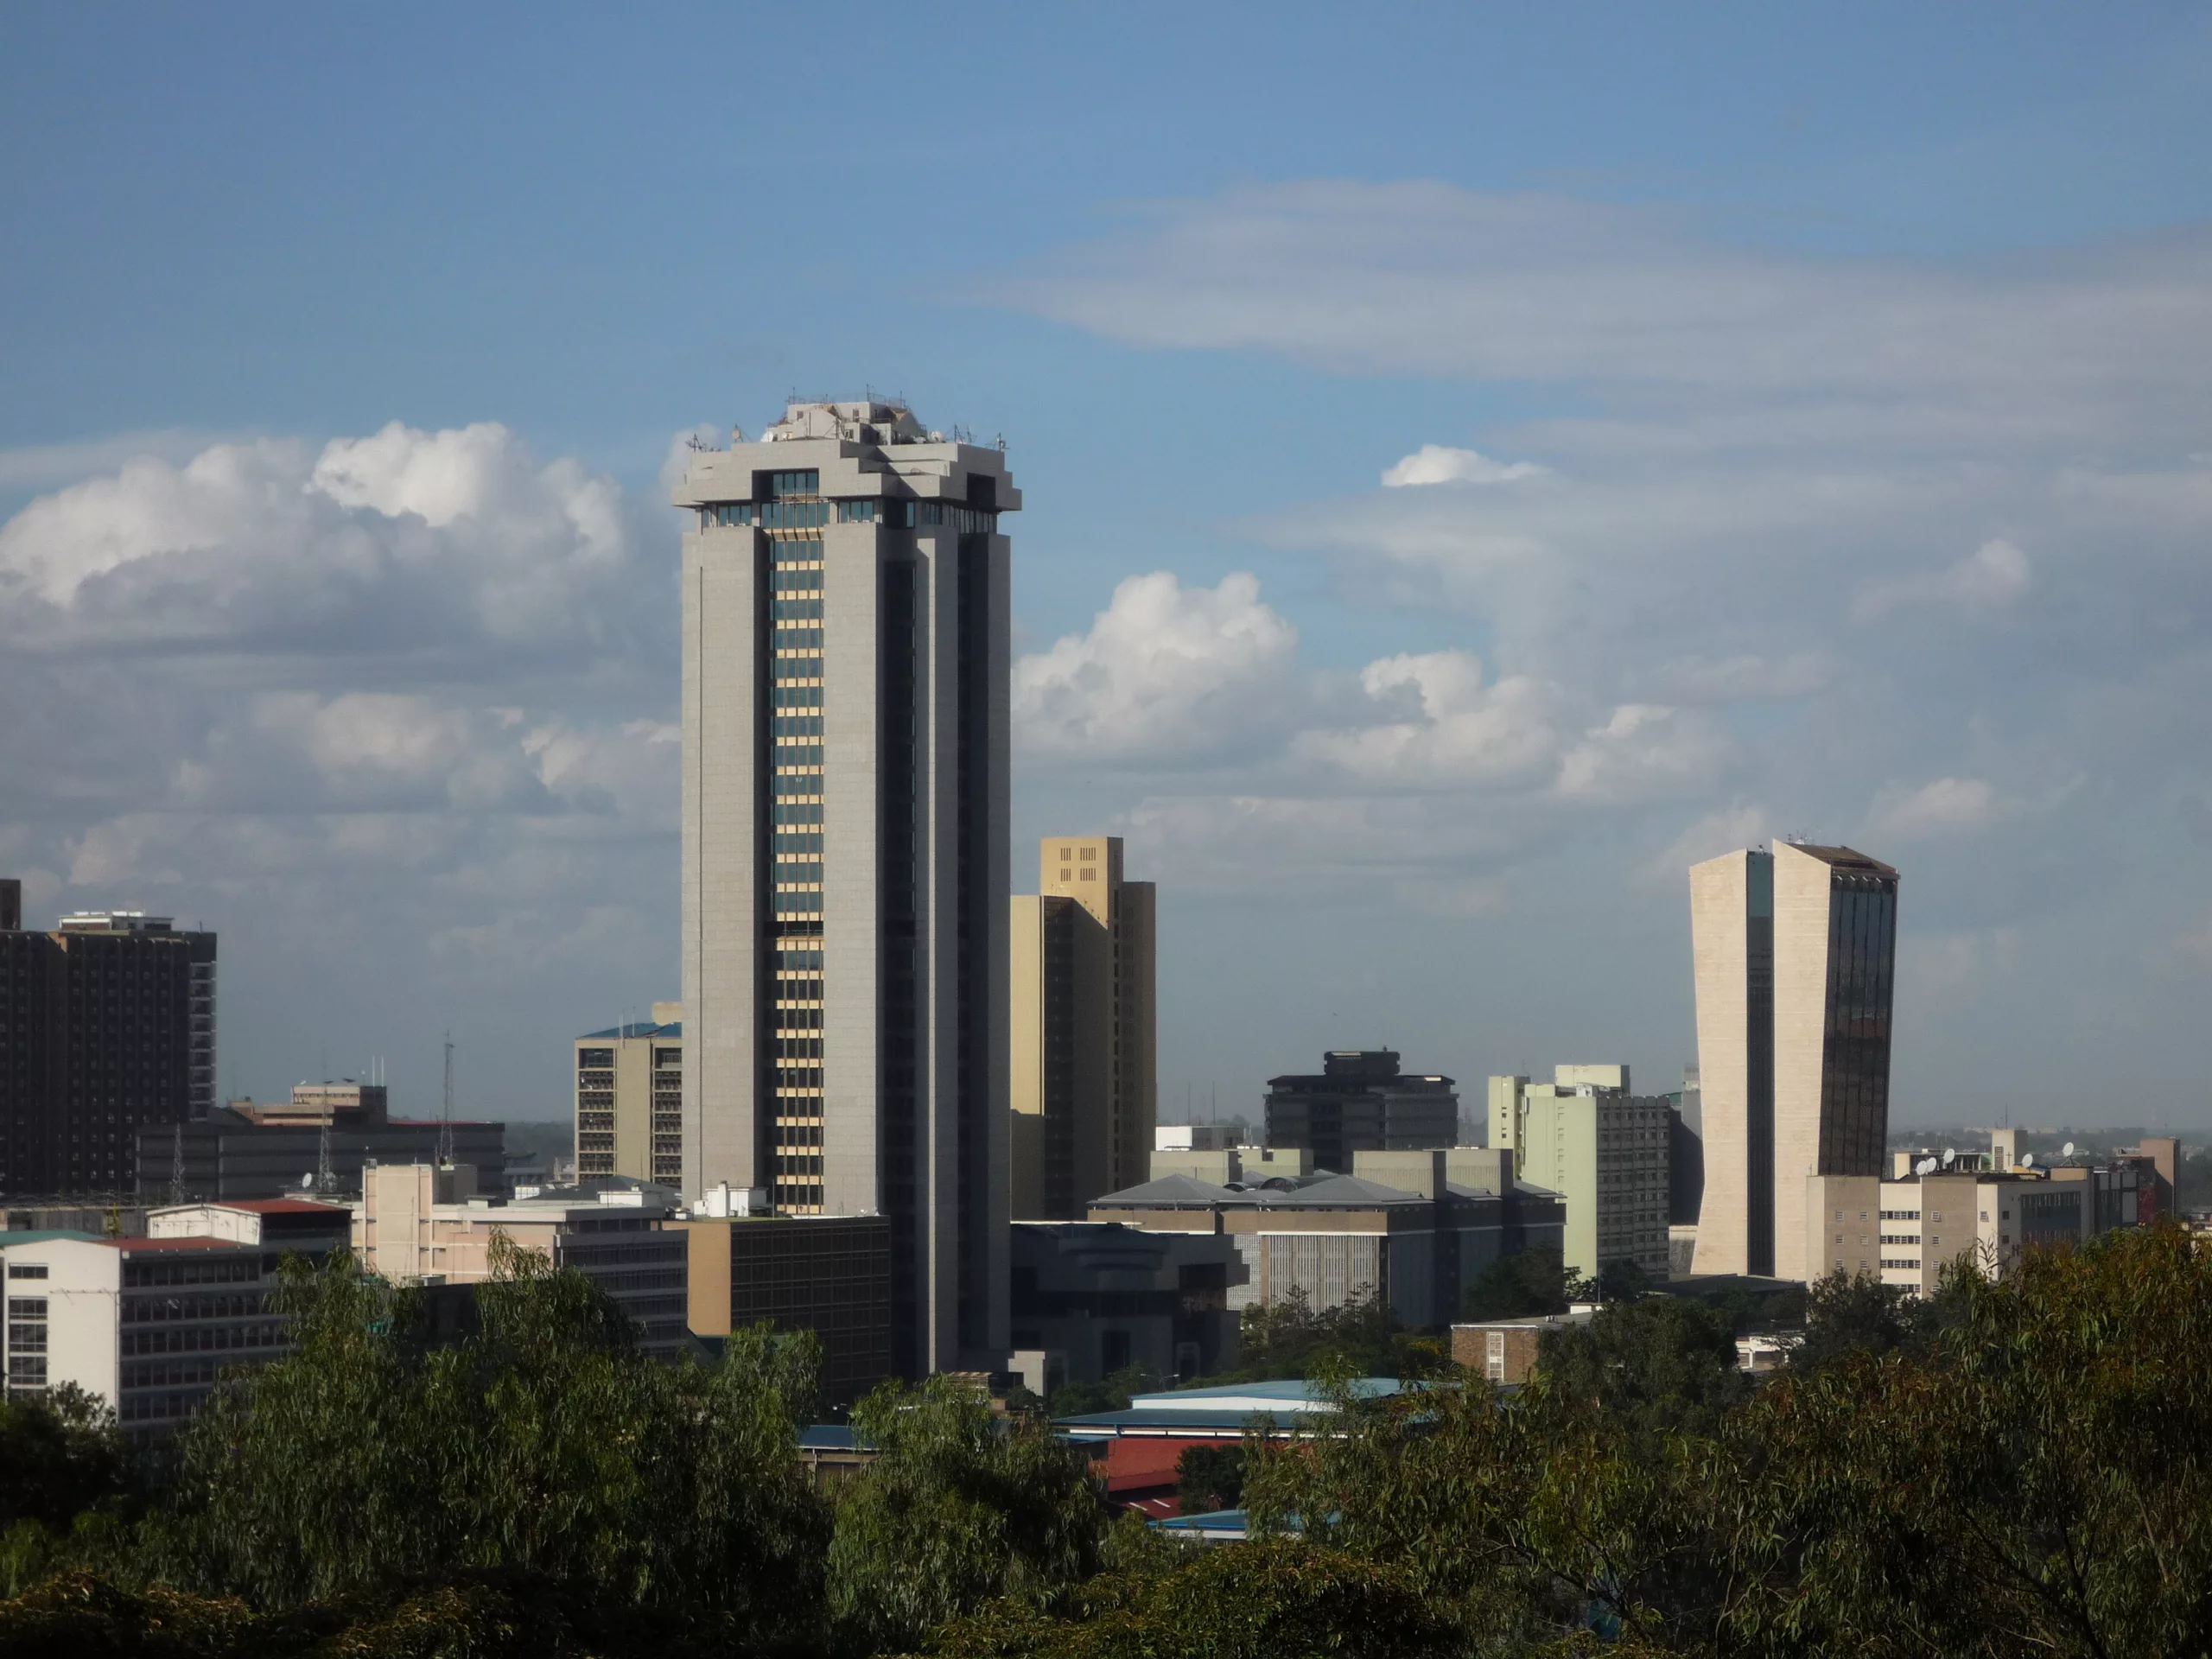
Africa · Eastern
Key Facts
—Funding peak and fall. Kenyan startup funding peaked at roughly $1.1 billion in 2022 before dropping about 40% to $692 million in 2023.
—Concentration in fewer deals. The number of Kenyan startups raising at least $100,000 fell by 23% from a year earlier, even as aggregate capital stayed high.
—Cleantech dominance. Cleantech alone accounted for about 46% of Kenya’s startup funding in 2024, displacing pure-play fintech as the leading sector.
—Foreign capital dependence. Approximately 81% of Kenyan startup funding in 2024 came from foreign investors, exposing the ecosystem to global monetary shifts.
—Early-stage squeeze. Deal counts dropped roughly 31% in Q1 2026 versus Q1 2025, leaving pre-seed and seed-stage founders struggling for capital.
Kenya startup funding has entered a new phase of brutal selectivity, where aggregate capital remains near record highs but flows into fewer, larger, asset-backed companies while early-stage ventures face a punishing drought.
The numbers behind Kenya startup funding’s structural shift
Kenya’s startup ecosystem experienced a vertiginous rise and a sobering correction within three years. Total funding peaked at roughly $1.1 billion in 2022, then fell to $692 million in 2023, a drop of about 40% that local analysts now call the sharpest contraction since Africa’s modern startup ecosystem took shape.
By 2024, the Kenya Innovation Outlook reported that startups attracted approximately KSh 82.5 billion ($638 million), equal to roughly 29% of all African startup capital and enough to keep Kenya ahead of Nigeria, Egypt, and South Africa as the continent’s top funding destination. Yet beneath that headline figure, the number of Kenyan startups raising at least $100,000 fell by 23% from a year earlier, the steepest decline among Africa’s Big Four.
The paradox is stark: Kenya can still attract large sums, but only a smaller cohort of de-risked companies is allowed through the gate. Startup Genome estimates that Kenyan startups raised $984 million in 2025, with a single quarter—Q3 2025—accounting for $536 million, or 54.2% of all African startup funding that quarter, the most concentrated three-month period on record.
Flight to quality reshapes Kenya startup funding
Investors are unmistakably re-rating risk across the Kenyan market. In 2024, cleantech alone absorbed about 46% of all startup funding, with climate-tech and agri-tech displacing pure-play fintech as the dominant themes for the first time in a decade.
Commentators describe a value renaissance in which steady, cash-flow-positive, asset-backed businesses—renewable energy platforms, logistics networks, data centres, and food production—now attract more capital than speculative software or consumer apps. Debt financing has surged to roughly 60% of total capital in certain years, as lenders back collateral and predictable cash flows rather than pure equity bets on growth narratives.
Clean-tech giants such as Sun King, d.light, and e-mobility firm Spiro have absorbed the lion’s share of Kenyan capital, with one analysis suggesting roughly 70% of tech funding went to just four companies. Average Series A deal sizes shrank from about $15 million in 2022 to $8.7 million in 2023, signalling lower valuations and tighter capital deployment across the board.
Who gets left behind in the new Kenya startup funding order
The early-stage segment is bearing the brunt of this recalibration. Across East Africa, venture capital funding in the nine months to September 2024 more than halved to $196 million from $480 million a year earlier, the lowest level since 2020, as investors doubled down on existing portfolio companies and notable founders.
Our reporting has shown this mirrors a broader African trend where a missing middle of growth-stage startups has emerged: many can raise initial cheques but struggle to secure follow-on capital, and now face harsher terms and higher expectations.
A missing middle of growth-stage Kenyan startups has emerged: many can raise initial cheques but struggle to secure follow-on capital, and now face harsher terms and higher expectations. Women-led startups secured only about 12% of Kenyan startup funding in 2024, according to the Innovation Outlook report, compounding the exclusion.
Several ecosystem analyses describe a “Born to Die” pattern where startups shut down even after raising significant capital, amid a wider 61% from a year earlier decline in African startup funding in 2024. A growing debate questions whether Kenya’s funding structures incentivised founders to build for investment rather than impact, over-optimising for grant and VC criteria instead of sustainable local market fit.
Domestic pressures amplify the Kenya startup funding squeeze
Kenya’s domestic environment has amplified global pressures in ways that distinguish it from peer markets. Broadcast coverage of AVCA data reported that Kenyan startup funding fell by KSh 20 billion ($155 million) in 2024, with total capital at KSh 41.4 billion ($318 million), down 33% from KSh 61.5 billion ($473 million) in 2023.
Observers link this directly to investor fears over political instability and an aggressive tax agenda, which they say spooked international investors and slowed local companies’ growth. Kenya’s Startup Bill, intended to formalise the sector, remains stalled, creating a perception of regulatory uncertainty that discourages long-term local investment.
The concentration of innovation services in Nairobi—over 75% of business support providers—and gaps in local capital markets deepen regional and social inequalities in who can access funding. These factors intersect with global risk aversion to produce a steeper pullback in Kenya than the Africa-wide averages, with Partech-based commentary citing an approximate 68% from a year earlier crash in Kenya at one point.
The foreign capital problem and great-power contest over Kenya startup funding
Kenya’s startup boom has been built on foreign capital, with approximately 81% of funding in 2024 coming from international investors, primarily from the United States and Europe. This dependence means that when New York sneezes, Nairobi catches the flu, as one commentator put it, with economic shocks in Washington, Frankfurt, or London directly translating into liquidity crunches in Kenya.
The suspension of USAID funding to African startups in 2025 created operational stress, with some companies struggling to pay suppliers and staff and facing possible liquidation. This episode underscored how Western public-sector decisions—shaped by geopolitics and domestic politics—can abruptly alter the survival prospects of Kenyan startups, particularly those with impact-driven models reliant on blended finance, a dynamic explored in our ongoing coverage of Africa: The New Scramble.
Gulf investors, especially from the UAE, are increasing their presence in African deals, often with longer-term horizons and different risk appetites, particularly in logistics, infrastructure, and energy. This makes large Kenyan deals in payments, cloud infrastructure, e-mobility, and distributed solar strategically significant, as control of payments rails and data infrastructures shapes who controls transaction data and digital identity.
What the Kenya startup funding reset means for investors and founders
The era of cheap, indiscriminate money is over, and the bar is permanently higher. Investors now expect profit visibility, governance, and real assets; story-driven Kenyan startups will find it increasingly hard to raise meaningful capital without demonstrating unit economics and defensible moats.
For Latin American readers familiar with their own region’s venture cycles, the Kenyan pattern is recognisable: a foreign-capital-fuelled boom, a sharp correction triggered by global rate hikes, and a subsequent flight to asset-backed, cash-flow-positive businesses. The difference lies in Kenya’s extreme dependence on external money and the absence of a deep domestic institutional investor base that could provide a backstop when global flows tighten.
Movement on the Startup Bill, tax predictability, and political stability will partly determine whether Kenya remains Africa’s funding hub or whether capital migrates to Lagos, Cairo, or Gulf-linked hubs. For now, Kenya startup funding has become a tale of two ecosystems: a small group of asset-heavy, climate-aligned platforms absorbing record sums, and a much larger population of early-stage founders navigating the harshest fundraising environment in years.
Connected Coverage
More: Kenya news in English, every day from The Rio Times.
Frequently Asked Questions
Why has Kenya startup funding slowed despite high aggregate numbers?
Kenya startup funding has not disappeared but has concentrated heavily in fewer, larger deals, primarily in cleantech and asset-backed sectors. The number of startups raising at least $100,000 fell by 23% from a year earlier, while total capital stayed near record levels because a handful of large platforms absorbed the bulk of investment.
Global interest rate rises, political uncertainty, and investor demands for profitability and governance have driven this flight to quality.
Which sectors are attracting the most Kenya startup funding now?
Cleantech has become the dominant sector, accounting for about 46% of Kenya’s startup funding in 2024, with companies like Sun King, d.light, and Spiro absorbing the largest rounds. Climate-tech, agri-tech, logistics, and data infrastructure have displaced pure-play fintech as the preferred verticals.
Investors are favouring asset-heavy, cash-flow-positive businesses over speculative software or consumer apps.
How does foreign capital dependence affect Kenya’s startup ecosystem?
Approximately 81% of Kenyan startup funding comes from foreign investors, primarily from the US and Europe, making the ecosystem highly vulnerable to global monetary policy shifts and geopolitical decisions. When international venture capital firms slowed or paused new investments during the 2022-2024 funding winter, Kenya lacked a deep domestic investor base to provide a backstop.
This dependence also means that governance standards, sectoral preferences, and even board-level control are often shaped more by foreign limited partners and development finance institutions than by Kenyan those involved.
Sources
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.