
MEXICO · COMPANY RESULTS
Key Facts
- The country Mexico is home to Gruma, a food group near Monterrey that sells tortillas and corn flour worldwide, led by the United States.
- What happened Gruma posted third-quarter profit of US$131.6 million on Wednesday 21 October 2026, down 1% from a year earlier.
- The numbers Net sales rose 1% to US$1,650.6 million, while adjusted EBITDA, a measure of operating cash earnings, fell 4% to US$280.3 million.
- Profit for each share Profit for each share rose 4% to US$0.40, helped by a smaller share count.
- The weak spot Sales in the United States, about half of the group, fell 4% and operating income in that business dropped 22%.
- Power Index Mexico ranks 2nd of 14 in The Rio Times Latin America Power Index, with 71.4 points (October 2026 edition).
- What it means for you US shoppers and bond investors are exposed to the same weak restaurant demand and thinner margins that hit Gruma’s US arm.
Gruma profit slipped 1% to US$131.6 million in the third quarter, the Mexican tortilla maker said on Wednesday 21 October 2026. Weak spending in US restaurants weighed on results, while Mexico, Europe, Asia and Central America held up better.
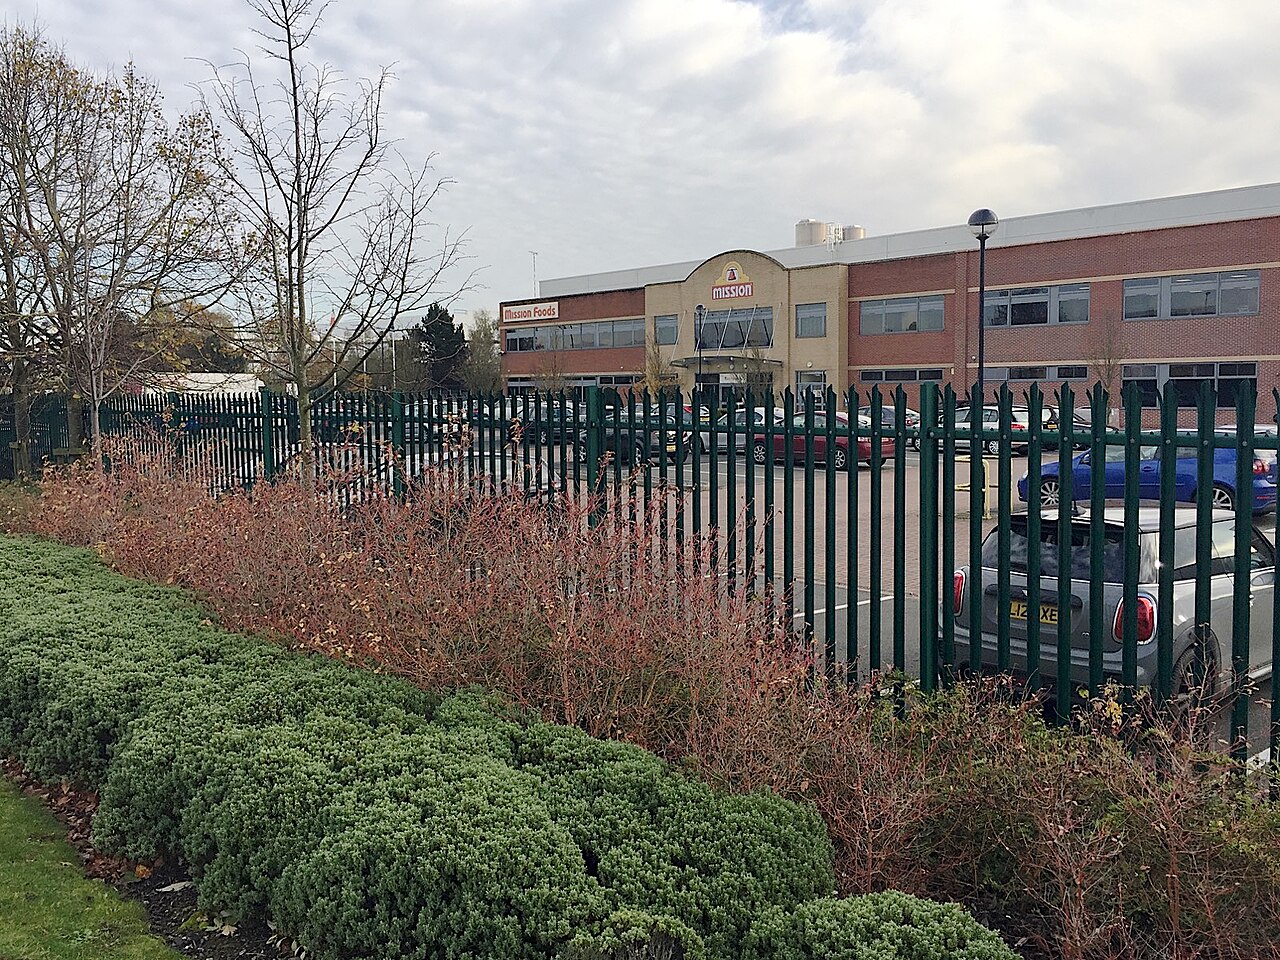
Gruma, based in San Pedro Garza García near Monterrey, sells Mission tortillas and Maseca corn flour and counts the United States as its largest market. Net sales rose 1% to US$1,650.6 million, so the dip in Gruma profit came from costs rather than from a collapse in demand.
Gruma Profit in the Third Quarter
Operating income, the profit before interest and tax, fell 5% to US$218.6 million, and the margin slid to 13.2% from 14.1%. Adjusted EBITDA, which adds back depreciation and one-off items, fell 4% to US$280.3 million.
Sales volume dropped 2% to 1,072 thousand metric tons, and Gruma said the decline came mainly from US food service. Costs for labour, packaging, fuel and distribution rose faster than sales, which squeezed the margin.
Over the first nine months of 2026, net sales rose 3% to US$4,925.3 million while net income fell 11% to US$351.0 million. Adjusted EBITDA for the nine months slipped 5% to US$818.7 million.
Why US Demand Is the Weak Spot
Gruma USA, the biggest unit behind Gruma profit, sold 372 thousand metric tons in the quarter, down 4%. Net sales fell 4% to US$838.1 million, which is roughly half of the group total.
Operating income in the US business dropped 22% to US$111.1 million, and its adjusted EBITDA margin fell to 17.9% from 21.1%. Gruma blamed cautious consumers, higher inflation and lower food service volumes, as it had in the second quarter.
Retail was steadier than restaurants, because shoppers kept buying tortillas for home and Gruma pushed private label products. The company said it is trying to balance volume, profit and product mix as US demand evolves.
Live Company IntelligenceGruma S.A.B. de C.V. — the full investor dossier
Valuation & profitability
Price & risk
$223.7252-wk high
$346.35
Revenue trend · 6y
Ownership
Dividend
Where Gruma Grew Instead
Gimsa, the Mexican corn flour subsidiary, saw net sales dip 1% to US$465.3 million but raised adjusted EBITDA 4% to US$55.5 million. Lower activity in government-linked programmes cut its volume by 2%.
Europe’s adjusted EBITDA rose 2% to US$20.3 million on growth in retail tortillas. Asia and Oceania did better, with sales up 10% to US$79.9 million and adjusted EBITDA up 22% to US$12.1 million.
Central America posted the strongest gain, as adjusted EBITDA jumped 47% to US$30.6 million. That result includes an insurance payment, so it is not a clean measure of the underlying trend.
Debt, Cash and the Share Count
On the balance sheet, total debt fell 3% from June to US$2,052 million, and cash rose to US$573 million. Net debt stood at 1.34 times adjusted EBITDA, down from 1.47 times in June.
Capital spending reached US$68 million in the quarter, up from US$44 million a year earlier. The money went to machinery at Gimsa, equipment upgrades in the United States, tortilla capacity in Mexico and expansion in Europe.
Earnings per share rose 4% to US$0.40 even though net income dipped, because Gruma had 332.0 million shares outstanding against 348.9 million a year ago. Fewer shares spread the profit over a smaller base.
What It Means for US Readers
If you buy tortillas in a US supermarket, the results show a company defending price and volume through private label and value products. The weak spot is restaurants and other food service, where Gruma sold fewer tortillas.
If you hold Gruma shares in Mexico or through a fund, Gruma profit is stable but under pressure in the US. The company’s US$500 million notes due 2034 and US$300 million notes due 2054 matter for bond investors, because net debt eased to 1.34 times EBITDA.
If you run a US food or restaurant business, Gruma’s own words are a useful signal about consumer spending. The company said US consumer demand stayed weak through the third quarter and described the mood as cautious.
What Is Not Known
The release gave no new full-year forecast for Gruma profit. After its second-quarter results, Gruma told analysts to expect lower US sales and an EBITDA margin about 1.6 points thinner, according to El CEO.
It is not clear when US food service demand will recover, or whether private label growth will make up the lost margin. Gruma scheduled a conference call with analysts for Thursday 22 October 2026 at 12:30 p.m. Eastern Time.
More: Mexico news in English, every day from The Rio Times.
Frequently Asked Questions
How much did Gruma earn in the third quarter of 2026?
Gruma profit was US$131.6 million for July to September 2026, down 1% from US$132.6 million a year earlier. Earnings per share were US$0.40, up from US$0.38.
What does Gruma make and sell?
Gruma is a Mexican group founded in 1949 that makes tortillas and corn flour, with about 25,000 employees and 77 plants. It sells in the United States, Mexico, Central America, Europe, Asia and Oceania.
Why did Gruma profit fall when sales rose?
Sales rose 1% to US$1,650.6 million, but costs for labour, packaging, fuel and distribution rose faster. Weak US food service demand also cut Gruma profit margins in its biggest market.
How important is the United States to Gruma?
Gruma USA produced US$838.1 million of net sales in the quarter, about half of the group total. Its adjusted EBITDA of US$149.7 million was also about half of the group figure.
Is Gruma’s debt a concern?
Debt fell 3% from June to US$2,052 million, and net debt was 1.34 times adjusted EBITDA. About 75% of the debt is denominated in US dollars.
Sources: Gruma, third quarter 2026 earnings release, 21 October 2026; Gruma investor relations, 3Q26 results notice, 21 October 2026; El CEO, Gruma adjusts its 2026 expectations, 10 August 2026.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
In depth
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.