Copper Slips with China Data; Chile, Peru Supply in Focus

Key Facts
- The United States Copper Index Fund, the futures-tracking proxy, settled at US$39.56, a rise of 0.56% on the day but well within a session range that signalled hesitation after a run of recent highs.
- Southern Copper, one of the world’s most copper-sensitive listed miners, closed at US$182.71, a drop of 1.24%, reflecting a sharper sell-off in equities than in the underlying futures market.
- Freeport-McMoRan, the giant US-based pure-play copper producer, fell 1.28% to US$62.63, mirroring the modest futures pullback as traders rotated out of high-beta copper names.
- A widely-quoted front-month COMEX copper futures contract pulled back to about US$6.0453 per pound, down from a previous close of 6.1480, as a softer Chinese manufacturing print clouded the demand picture.
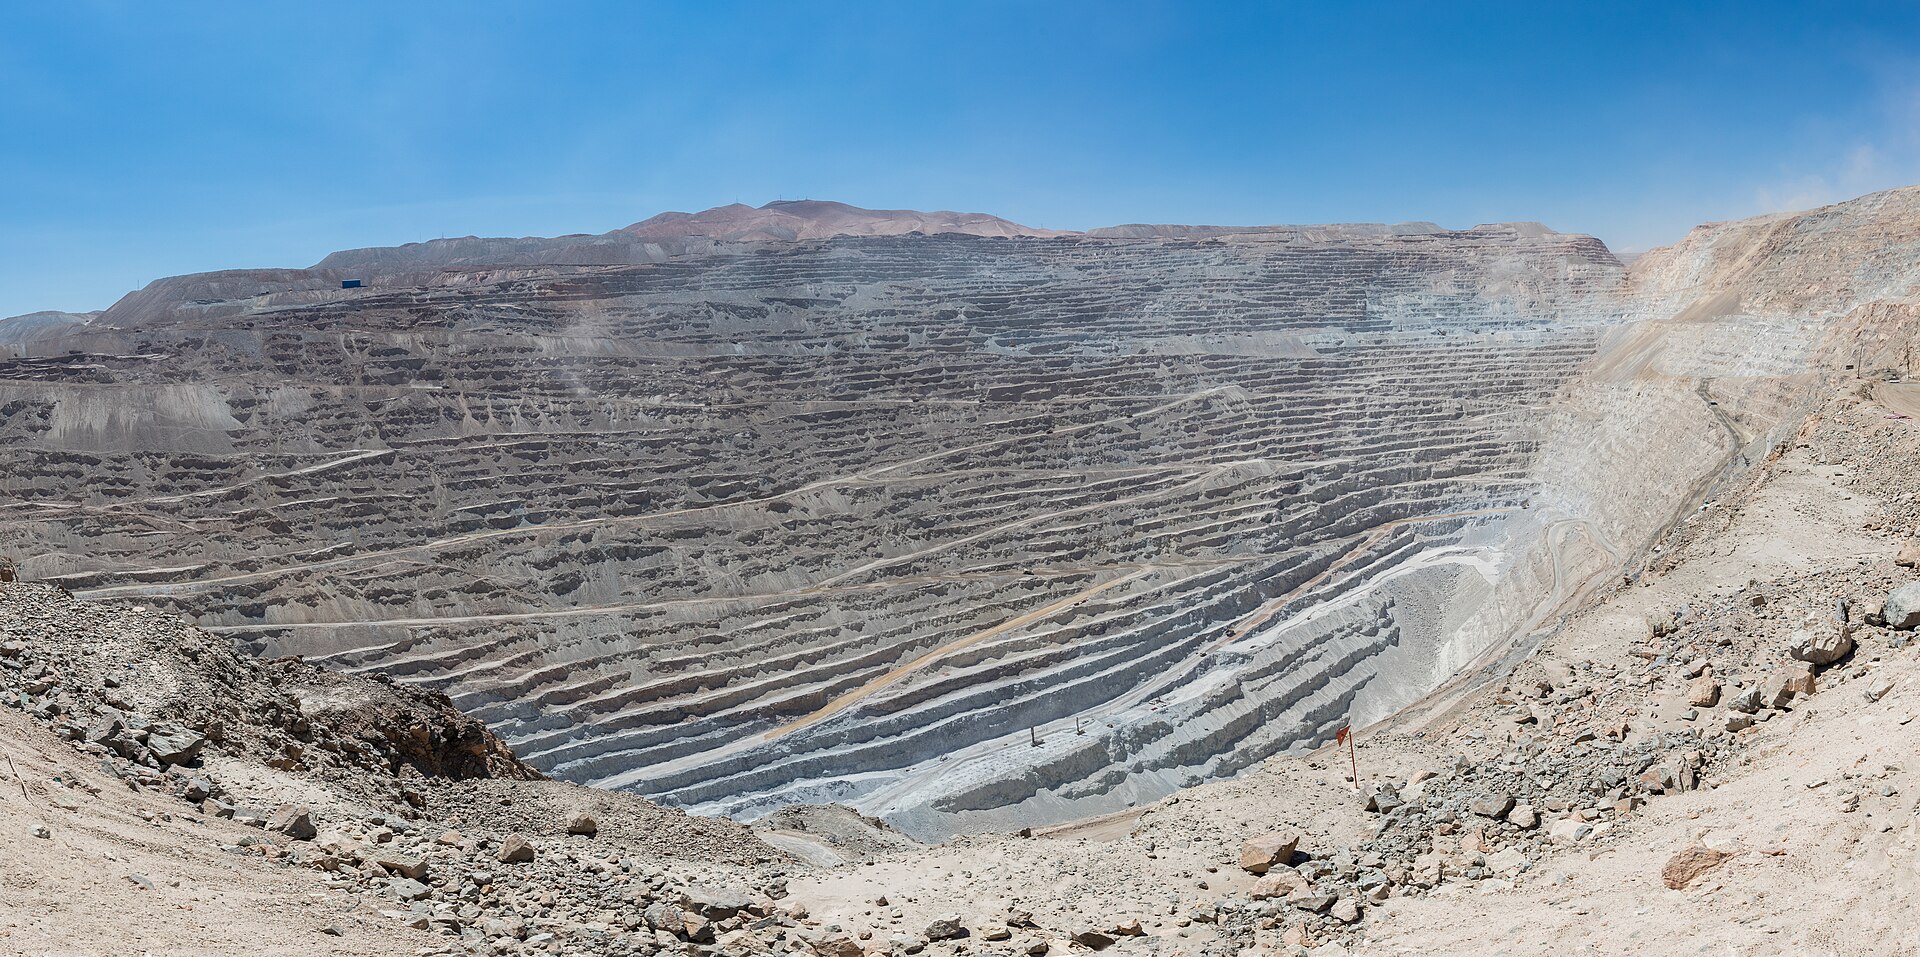
- Chile remains the world’s largest copper producer and Peru the second-largest, making policy signals, labour relations and environmental regulation in the Andes central to every price swing.
- Analyst consensus surveyed by Reuters forecasts a copper average of USD 10,500 per metric ton in 2026, a figure 7.2% higher than the previous poll, pointing to deeply embedded expectations of a structural supply deficit.
Today’s Focus
Copper futures edged lower on Monday in a session that mixed soft Chinese manufacturing data with the unrelenting long-term demand story of the global energy transition. The United States Copper Index Fund, which tracks a portfolio of COMEX copper futures rather than physical metal, settled at US$39.56, a rise of 0.56% but one that masked an intraday drift lower from earlier peaks.
The bigger moves came from the copper miners. Southern Copper, a company whose revenues are almost entirely tied to the red metal, fell 1.24% to US$182.71. Freeport-McMoRan, another pure-play producer and a bellwether for institutional positioning on copper, slid 1.28% to US$62.63. The Global X Copper Miners ETF, the first pure-play equity basket for copper, has a three-year daily return correlation of 0.73 with CPER, a reminder that mining equities often amplify even modest futures moves.
The proximate trigger was a downbeat Chinese manufacturing reading. Academic research has long established that China’s industrial production, fixed-asset investment and manufacturing purchasing managers’ indices are among the strongest statistical drivers of copper price volatility, given the country’s dominant share of global refined copper consumption. A weak print reignites fears that the biggest buyer of copper is losing momentum.
Structurally, however, the market remains framed by a supply-demand equation that analysts think will tighten for years. Chile and Peru together anchor the global mining supply chain, while copper’s role in electric vehicles, renewable power, grid expansion and data-centre electrification has recast the metal as a long-duration bet on decarbonisation. A widely cited Reuters poll of 30 analysts projects copper will average USD 10,500 per ton in 2026, fully 7.2% above the previous survey.
What matters today. Soft Chinese manufacturing data pricked the near-term copper rally, but the long-term structural deficit narrative, anchored by the energy transition and constrained supply from Chile and Peru, remains intact.

01 The session in one read
Copper started the week with a defensive tilt, futures easing from recent highs as a weaker-than-expected Chinese manufacturing gauge punctured the demand narrative just as liquidity thinned for the northern hemisphere summer. The copper-tracking fund CPER settled at US$39.56, a gain of 0.56% on paper that belied an intraday drift lower from a peak of US$37.59.
Equity proxies for copper absorbed the move with even less enthusiasm. Southern Copper gave back 1.24% to close at US$182.71, and Freeport-McMoRan lost 1.28% to US$62.63. The downward moves in miners, whose earnings are geared to the copper price, underscored how even a mild futures pullback can cascade into a more painful session for producer shares.
Copper is caught between two powerful, opposing forces: a faltering Chinese industrial engine that drives day-to-day price action, and a generational energy-transition demand shift that is not yet fully priced in. The futures curve remains in a state of high alert, with front-month COMEX contracts slipping from 6.1480 to around US$6.0453 per pound on the latest China data. The variable to watch this week is whether further Chinese macro indicators, particularly fixed-asset investment and the official manufacturing PMI revisions, confirm or reverse Monday’s growth scare.
02 The board
The price board captures a market split between a modestly positive headline settle for CPER and outright weakness in the blue-chip miners. CPER’s 0.56% rise to US$39.56 reflected its intraday range of US$37.12 to US$37.59, leaving the fund roughly 1% below its session peak. With a market capitalisation of US$710.18 million, CPER remains the primary US-listed pipeline for investors wanting pure futures exposure without a physical metal mandate.
The two most copper-sensitive equities on the board, Southern Copper and Freeport-McMoRan, tell a different story. Their 1.24% and 1.28% declines respectively point to a rapid repricing of risk by equity investors, who tend to shoot first when the macro fog thickens. A quantitative study of rolling three-year daily returns shows Southern Copper correlated at 0.67 with CPER and Freeport-McMoRan at 0.65, confirming that Monday’s selling was a concentrated copper trade, not a broad materials rout.
| Asset | Level | Change |
|---|---|---|
| Copper (CPER tracker) | US$39.56 | +0.56% |
| Southern Copper | US$182.71 | -1.24% |
| Freeport-McMoRan | US$62.63 | -1.28% |
Source: RT close, 2026-07-31. Where a commodity has no spot feed, an exchange-traded tracker or leading producer is shown as a labelled proxy.
Live Market IntelligenceThe live market board
Rio Times · Live Market Intelligence
Latin America — Cross-Market Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IBOV | 167,921.80 | -0.75% | +19.56% | 169,186.42 | 178,526 | 175,157 | — |
| IPSA | 10,254.15 | -2.76% | — | 10,545.26 | 10,722 | 10,633 | — |
| IPC MEX | 69,779.20 | -0.01% | +12.74% | 69,787.41 | 70,008 | 69,383 | 49,372,306 |
| MERVAL | 2,848,945 | — | +12.65% | 2,859,051 | — | — | — |
| COLCAP | 2,490.92 | +0.04% | — | — | — | — | — |
| USD/BRL | 5.34 | -1.32% | -0.84% | 5.42 | 5.42 | 5.30 | — |
| EUR/BRL | 5.95 | +7.53% | -4.87% | 5.54 | 6.04 | 5.92 | — |
| USD/MXN | 18.69 | +0.62% | +1.45% | 18.57 | 18.69 | 18.54 | — |
| USD/CLP | 983.47 | -0.57% | +5.64% | 989.13 | 991.87 | 979.07 | — |
| USD/COP | 3,149 | +3.06% | -18.02% | 3,056 | 3,173 | 3,111 | — |
| USD/PEN | 3.45 | +0.17% | +3.85% | 3.44 | 3.45 | 3.44 | — |
| USD/ARS | 1,537 | -0.28% | +3.77% | 1,541 | 1,541 | 1,537 | — |
| USD/UYU | 40.21 | +3.57% | +2.29% | 38.83 | 40.21 | 40.08 | — |
| USD/PYG | 5,803 | +3.78% | -16.54% | 5,592 | 5,803 | 5,735 | — |
| USD/BOB | 11.97 | +4.93% | +77.92% | 11.41 | 11.97 | 11.82 | — |
| USD/DOP | 60.54 | +1.83% | -4.34% | 59.45 | 61.14 | 59.85 | — |
| USD/CRC | 451.24 | +2.13% | -7.80% | 441.83 | 451.40 | 450.04 | — |
| USD/GTQ | 7.64 | +3.23% | +2.18% | 7.40 | 7.64 | 7.64 | — |
03 What moved it
The main catalyst was a soft Chinese manufacturing indicator. China is by far the world’s largest consumer of refined copper, and a large body of academic research identifies Chinese industrial production, construction activity and manufacturing PMIs as the dominant short-term drivers of copper price volatility. A disappointing print immediately trims demand assumptions for the physical metal and triggers algorithmic selling across futures and proxies.
Beyond the China data point, copper remained anchored by the tension between current physical stockpiles and future structural demand. Market commentary has noted that copper inventories in US warehouses recently swelled to 535,000 tons, the highest since 2003, even as prices ran up earlier in the year. Yet the Global X Copper Miners ETF rose 118% year-over-year in that period with roughly US$2 billion in fresh inflows, illustrating how anticipatory capital is piling in ahead of actual consumption.
04 The Latin American read
For Latin America, copper is not just a commodity; it is a sovereign balance-sheet variable. Chile is the world’s largest producer of mined copper and Peru ranks second, meaning that every swing in the futures market reshapes fiscal revenues, currency expectations and political bandwidth in Santiago and Lima.
Academic work on copper-price volatility repeatedly flags policy decisions, labour negotiations and environmental permitting in Chile and Peru as the supply-side triggers that can tighten the global market without warning. For a foreign investor watching from São Paulo or New York, the Andean copper belt remains the supply chain’s most important and least predictable link.
05 The names to watch
The pure-play copper miner ETFs are the fastest-moving equity instruments tied to the metal’s price. The Sprott Copper Miners ETF, which requires constituents to derive at least 50% of revenue from copper, recently closed down 1.38% at US$37.13. The Canadian-listed Global X Copper Producers Index ETF, tracking the Solactive North American index, bucked the trend with a 1.77% gain to 57.37 Canadian dollars, reflecting a different geographic and index composition.
The diversified miners that carry heavy copper exposure, BHP Group, Rio Tinto and Teck Resources, have three-year daily return correlations to CPER of 0.59, 0.57 and 0.53 respectively. They provide a softer ride than the pure plays but still respond to the same structural forces. European investors channel their copper exposure through the WisdomTree Copper ETC, which tracks the Bloomberg Copper index of futures contracts and commands a fund size of GBP 1,227 million with a total expense ratio of 0.49%.
06 The outlook
Copper’s forward path turns on whether fresh Chinese data will confirm or soften Monday’s growth scare, and whether supply signals from Chile and Peru tighten enough to offset any demand wobble. The median forecast from 30 analysts in a recent Reuters survey points to an average copper price of USD 10,500 per metric ton in 2026, a 7.2% upward revision from the prior poll and a signal that the analyst class is treating near-term weakness as noise within a structural deficit story.
07 What to watch
- China’s next PMI and fixed-asset investment prints: As the world’s dominant copper consumer, any confirmation of a manufacturing slowdown would force a reassessment of demand models and could deepen the pullback in CPER.
- Chilean mine supply and labour negotiations: Chile is the world’s largest copper producer; any disruption from strike action, regulatory change or water restrictions would quickly tighten the concentrate market.
- Peruvian output and political risk: Peru ranks second globally in mined copper, and persistent social unrest or permitting delays in the southern mining corridor could remove tonnes the market is counting on.
- Energy transition capital flows into copper ETFs: The Global X Copper Miners ETF and CPER attracted billions in fresh inflows even during choppy sessions; sustained buying would signal that long-only investors are treating dips as entry points.
Frequently Asked Questions
Why did copper slip on Monday?
A weak Chinese manufacturing data point spooked traders, because China is the world’s largest copper consumer and its industrial health directly drives short-term price swings.
Does CPER track the spot price of copper?
No. CPER tracks the SummerHaven Copper Index Total Return, a portfolio of COMEX copper futures contracts, so its performance reflects futures curves and roll yields rather than physical warehouse prices.
Why did Southern Copper and Freeport-McMoRan fall more than CPER?
Mining equities are geared to the underlying commodity price and tend to amplify even modest futures moves; their three-year daily return correlations to CPER are 0.67 and 0.65 respectively.
Why do Chile and Peru matter so much for copper prices?
Chile is the world’s largest mined-copper producer and Peru the second-largest, meaning global supply is acutely sensitive to policy shifts, labour disputes and environmental regulation in the Andes.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
In depth
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.