Brazil’s Financial Morning Call for Tuesday, September 29, 2026
Updated 1 time · Latest: 29 September 2026
Key Facts
- The Selic stands at 13.75% after the Copom’s quarter-point cut on 16 September, its fifth in a row; the next decision is due on 4 November.
- September’s IGP-M inflation is out at 08:00 BRT after August’s −0.22%; calendars differ widely on the forecast, from 0.6% to 1.7%.
- Unemployment is seen holding at 5.3% at 09:00 BRT, with Caged formal payrolls for August forecast at 80,000 to 87,000 jobs.
- The Treasury’s August central government result is due at 15:30 BRT, with a forecast deficit of R$14.2 billion (about US$2.7 billion).
- Monday’s calendar was mixed: August foreign direct investment of US$7.40 billion covered a US$5.05 billion current-account deficit, but the Focus survey lifted 2026 inflation expectations to 4.99%.
- Nubank is the corporate story after its New York shares fell 10.0% on Monday on reports of early-stage talks to buy UK digital bank Monzo.
Today’s Focus
Brazil’s B3 opens to a busy data morning. The Copom cut the Selic by a quarter-point to 13.75% on 16 September. Today’s inflation and labour numbers will shape bets on the 4 November meeting.
At 08:00 BRT, the IGP-M wholesale-heavy inflation index is expected to return to a monthly rise after August’s −0.22%. The central bank’s credit data follow at 08:30 and the unemployment rate at 09:00.
The Treasury’s August central government result comes at 15:30 BRT. Caged formal job figures are also listed for today in most calendars.
On the corporate side, Nubank is the story to watch. Its New York-listed shares fell 10.0% on Monday to US$12.23 after reports that it is in early-stage talks to buy Monzo.
What matters today. Whether the inflation and labour prints support more Selic cuts, five days before the 4 October first round.

Today’s Economic Events
| Instrument | Level | Session |
|---|---|---|
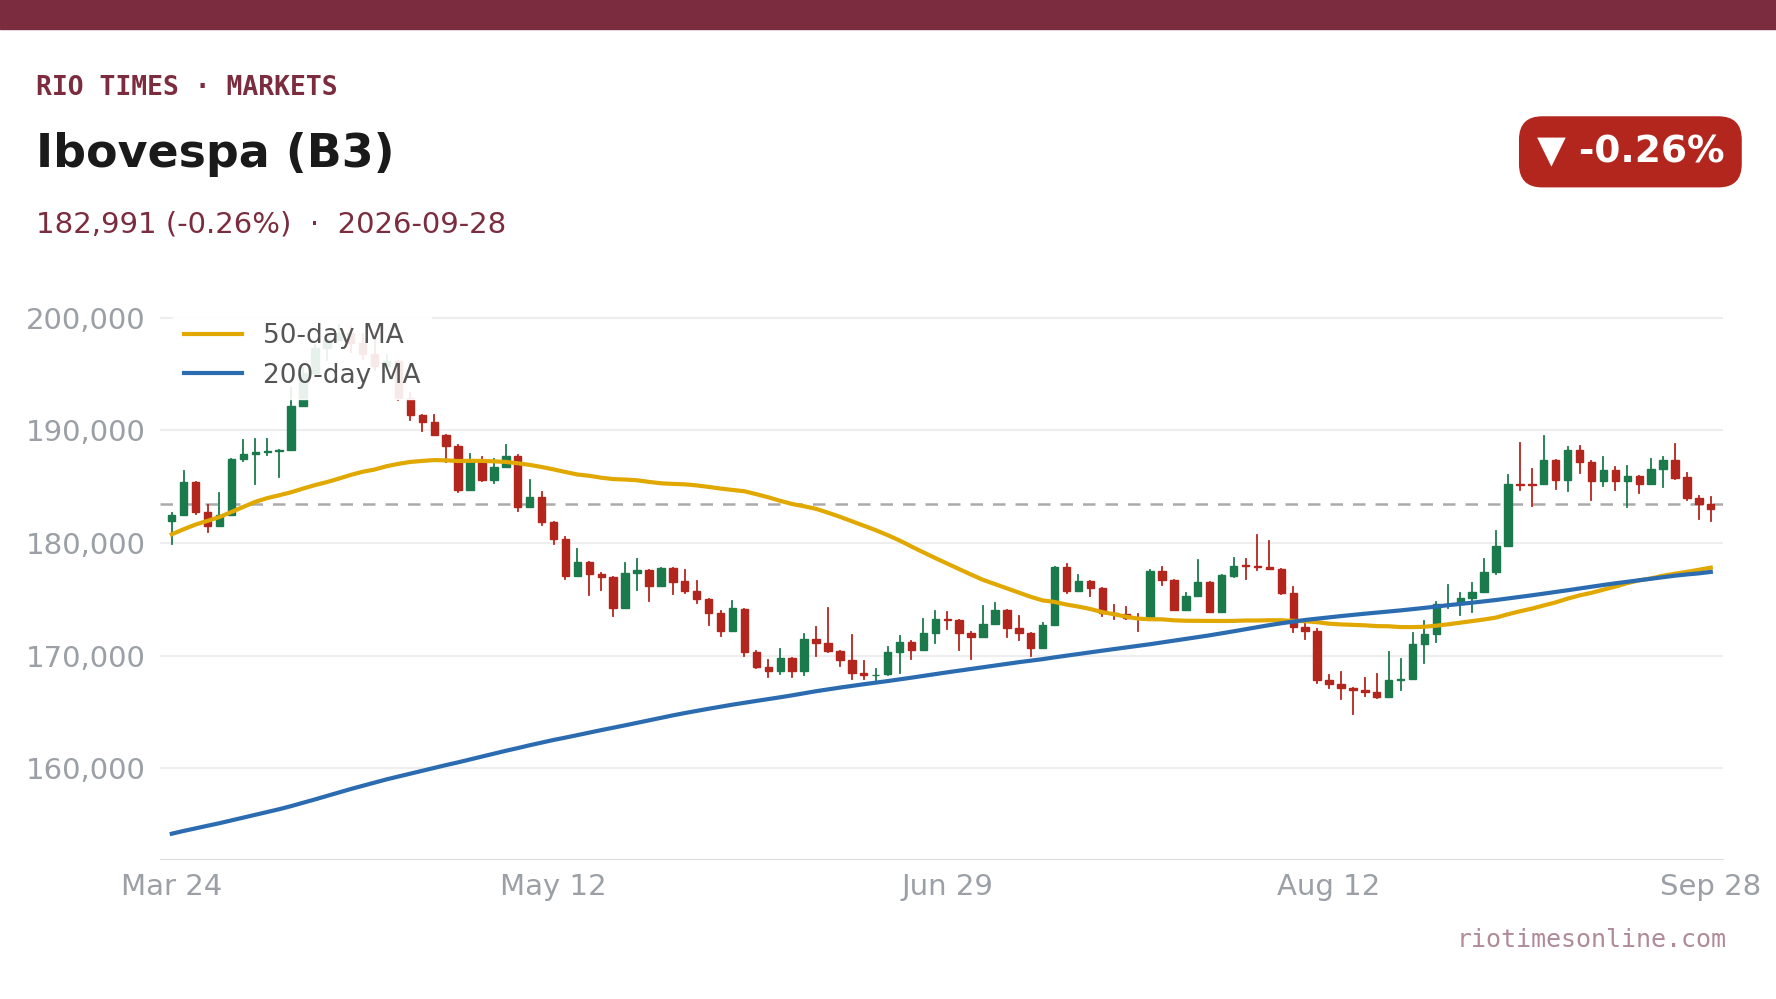
| Ibovespa (Brazil) | 182,991 | -0.26% |
| S&P 500 (US) | 7,684 | -0.77% |
| USD/BRL | 5.2255 | +0.86% |
Source: RT live market data, close of Monday 28 September 2026.
01 The setup in one read
Tuesday’s B3 session opens with a dense run of domestic data. The Selic stands at 13.75% after this month’s quarter-point cut, and every release today feeds the debate over further easing.
The first test is the IGP-M at 08:00 BRT. It fell 0.22% in August. Forecasts for September range from 0.6% to 1.7%, and a hot print would cool hopes of faster easing.
Labour data follow. The unemployment rate at 09:00 BRT is expected to hold at 5.3%, a historically low level. Caged formal payrolls are forecast at 80,000 to 87,000.
The fiscal picture closes the day. The Treasury’s August central government result at 15:30 BRT is expected to show a deficit of R$14.2 billion (about US$2.7 billion). The central bank’s wider public-sector and gross-debt figures follow on Wednesday.
The evidence points to a cautious open. The IGP-M is expected to swing back to a rise, unemployment is forecast to stay at 5.3% and oil prices are high. That mix supports the Copom’s cautious tone on further cuts. Monday’s Focus survey already raised 2026 inflation expectations for a second straight week, so a hot IGP-M would land on a nervous base. The Ibovespa has fallen four sessions in a row, and the real weakened 0.86% on Monday.
The variable to watch is the IGP-M at 08:00 BRT. With forecasts so far apart, the print itself will set the early tone for local rates and the real.
02 Where Brazil is set to open
| Instrument | Last close | Monday | Watch today |
|---|---|---|---|
| Ibovespa | 182,991 | −0.26% | IGP-M and labour data to set the risk tone |
| USD/BRL | 5.2255 | +0.86% | Data and polls; rate near the middle of its 52-week range |
| Petrobras PN | R$48.72 (US$9.32) | +1.35% | Turnover leader on Monday; crude prices and the US–Iran talks |
| Vale ON | R$71.16 (US$13.62) | +0.55% | China demand signals and iron ore into the B3 open |
The Ibovespa and the real both weakened in Monday’s session, tracking a weaker Wall Street. The US 10-year yield is above 5.2%, which keeps pressure on emerging-market assets. S&P 500 futures were slightly lower early on Tuesday, while Brent crude futures were about 1.5% higher, which supports Petrobras into the open.
Today’s direction should come mainly from domestic data. The first number is the IGP-M at 08:00 BRT, an hour before the B3 cash market opens.
Live Market IntelligenceBrazil Morning Call — Live Board
Rio Times · Live Market Intelligence
Brazil Morning Call — Live Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IBOV | 171,880.69 | +0.32% | +9.21% | 171,324.31 | 172,217 | 171,132 | — |
| USD/BRL | 5.66 | +0.37% | +6.98% | 5.64 | 5.67 | 5.63 | — |
| EUR/BRL | 6.26 | +1.12% | +2.12% | 6.19 | 6.26 | 6.23 | — |
| SELIC | 13.75% | — | — | — | — | — | |
| BRENT | 96.74 | +0.96% | +53.53% | 95.82 | 97.05 | 95.07 | 10,498 |
| WTI | 89.08 | +0.38% | +51.78% | 88.74 | 89.47 | 87.80 | 65,955 |
| IRON ORE | 161.91 | — | +55.61% | 161.91 | 161.91 | 1 | |
| GOLD | 3,885 | -0.02% | -7.39% | 3,885 | 3,927 | 3,876 | 89,189 |
| SILVER | 49.73 | -0.48% | -6.30% | 49.97 | 50.73 | 49.55 | 25,051 |
| LITHIUM | 59.43 | -2.69% | -6.69% | 61.07 | 60.05 | 59.34 | 169,960 |
| SOY | 1,232 | +0.41% | +8.83% | 1,227 | 1,238 | 1,219 | 29,616 |
| CORN | 446.00 | +0.79% | +1.02% | 442.50 | 448.25 | 441.75 | 56,048 |
| WHEAT | 590.75 | +1.11% | +10.27% | 584.25 | 596.50 | 582.00 | 24,577 |
| COFFEE | 276.20 | -1.43% | -31.24% | 280.20 | 279.20 | 272.55 | 7,099 |
| SUGAR | 18.44 | +1.21% | +27.70% | 18.22 | 18.46 | 18.16 | 18,654 |
| ORANGE JUICE | 140.10 | -0.60% | — | 140.95 | 145.00 | 139.80 | 96 |
| COTTON | 83.18 | +5.73% | +32.24% | 78.67 | 79.90 | 78.63 | 9,774 |
| BEEF | 218.98 | +0.00% | -0.01% | 218.98 | 220.85 | 218.28 | 31,806 |
| CATTLE | 335.85 | +0.97% | -0.34% | 332.63 | 337.40 | 332.40 | 9,951 |
| COCOA | 5,311 | +4.84% | -3.21% | 5,066 | 5,329 | 5,169 | 8,129 |
| PETR4 | 44.84 | +0.31% | +38.01% | 44.70 | 44.89 | 44.62 | 1,790,000 |
| VALE3 | 64.03 | +0.13% | -2.54% | 63.95 | 64.24 | 63.85 | 563,300 |
| SUZB3 | 55.68 | -0.64% | +16.85% | 56.04 | 55.98 | 55.48 | 230,000 |
| KLABIN | 17.62 | -0.11% | -1.24% | 17.64 | 17.76 | 17.59 | 114,300 |
| SLCE3 | 18.54 | +0.98% | +25.96% | 18.36 | 18.65 | 18.31 | 349,400 |
| ABEV3 | 15.74 | -0.06% | +15.41% | 15.75 | 15.80 | 15.64 | 479,400 |
| ITUB4 | 41.98 | +0.72% | +6.74% | 41.68 | 42.17 | 41.62 | 1,141,200 |
| BBDC4 | 14.31 | -0.07% | -26.54% | 14.32 | 14.44 | 14.28 | 2,196,600 |
| BBAS3 | 15.12 | -2.33% | -32.84% | 15.48 | 15.60 | 15.10 | 14,891,200 |
| B3SA3 | 14.57 | -1.29% | +0.76% | 14.76 | 14.87 | 14.53 | 9,174,900 |
| WEGE3 | 51.74 | +0.17% | +15.44% | 51.65 | 52.05 | 50.93 | 914,400 |
| PRIO3 | 63.30 | +0.00% | +59.55% | 63.30 | 63.83 | 63.02 | 5,534,600 |
| RENT3 | 30.03 | +1.52% | -28.57% | 29.58 | 30.16 | 29.58 | 715,100 |
| AZZA3 | 16.61 | -1.72% | -43.46% | 16.90 | 17.10 | 16.32 | 650,200 |
| CSNA3 | 4.06 | -4.02% | -53.54% | 4.23 | 4.14 | 4.01 | 3,796,200 |
| GGBR4 | 24.97 | +0.00% | +32.05% | 24.97 | 25.09 | 24.73 | 225,400 |
| ENEV3 | 26.79 | -0.78% | +38.88% | 27.00 | 27.09 | 26.76 | 201,000 |
| LREN3 | 9.47 | +0.74% | -36.28% | 9.40 | 9.58 | 9.34 | 2,783,100 |
03 Monday’s calendar, one by one
Monday’s morning call and the weekly preview flagged the Focus survey, the August external accounts, the Dallas Fed index and the Fed speakers. Here is how each landed.
| Release | Actual | Forecast | Previous |
|---|---|---|---|
| Focus: 2026 IPCA inflation | 4.99% | — | 4.92% |
| Focus: year-end Selic | 13.50% | — | 13.50% |
| Current account (Aug) | −US$5.05bn | about −US$4.9bn | −US$9.37bn |
| Foreign direct investment (Aug) | US$7.40bn | about US$6.9bn | US$6.97bn |
| US Dallas Fed manufacturing (Sep) | 9.8 | 1.0 | 11.6 |
Focus survey. Economists lifted their 2026 inflation forecast for a second straight week, after the hot IPCA-15. They still see one more Selic cut to 13.50% by December, and trimmed 2026 growth to 1.86% from 1.88%. Banks fell, with Itaú down 1.00%.
External accounts. The August current-account deficit roughly halved from July, and foreign direct investment beat forecasts and fully covered it. Good news for the real on paper—but it still weakened 0.86% as the dollar rose across Latin America.
US data and Fed. The Dallas Fed index beat forecasts, in line with the rise in US 10-year yields to 5.244%. Vice Chair for Supervision Bowman spoke on bank supervision and gave no rate signal, and Richmond Fed President Barkin published no text. Governor Lisa Cook carried the policy message: after September’s quarter-point hike, she said inflation, an estimated 3.8% in the year to August, has been too high for too long and that she will consider what policy rate may be needed.
Levels we flagged. The Ibovespa broke below the 183,477 pivot and closed at 182,991, extending the slide to four sessions. The real weakened through 5.23 per US dollar to 5.2255, close to the 5.25 per US dollar risk level named on Monday.
04 On the B3 radar today — Brazil data and corporate signals
| Item | When | Why it matters |
|---|---|---|
| IGP-M inflation (September) | 08:00 BRT | Forecasts range from 0.6% to 1.7% after August’s −0.22%; sets the tone for price expectations |
| Credit and monetary data (August) | 08:30 BRT | Central bank credit figures show how the high Selic is feeding through to lending |
| Unemployment rate (three months to August) | 09:00 BRT | Seen holding at 5.3%; a tight labour market keeps the Copom cautious |
| Caged net payrolls (August) | 14:30 BRT | Forecast at 80,000 to 87,000 formal jobs; one calendar lists it for Wednesday |
| Central government result (August) | 15:30 BRT | Forecast deficit of R$14.2 billion (about US$2.7 billion); a fiscal check on rates |
The morning is front-loaded. The IGP-M, credit data and unemployment all land within an hour, before the 10:00 BRT open of the cash market.
The afternoon brings Caged payrolls and the Treasury result. A strong jobs number would confirm the labour market’s resilience, the main channel that keeps services inflation sticky.
05 Copom and the macro backdrop
The Selic sits at 13.75% after the Copom cut it by a quarter-point on 16 September. The minutes said the outlook calls for serenity and caution, and further easing depends on the data. The next meeting is on 3–4 November.
Today’s data speaks directly to that caution. A hot IGP-M would add wholesale price pressure, while a 5.3% unemployment rate and strong Caged payrolls would suggest that wage inflation has not yet cooled enough for comfort.
The fiscal side is equally important. A central government deficit wider than the expected R$14.2 billion (about US$2.7 billion) would add to doubts about Brazil’s fiscal anchor. The central bank’s gross-debt figures follow on Wednesday.
For foreign investors, the arithmetic is simple. High Selic keeps the real attractive, but a deteriorating fiscal outlook erodes that carry-trade appeal. Today’s data will show which force has the upper hand in the near term.
06 Corporate stories to watch today
The biggest corporate story is Nubank. Its New York-listed shares fell 10.0% on Monday to US$12.23. Sky News and Reuters reported early-stage talks over a possible purchase of UK digital bank Monzo. No deal has been announced.
The story matters for B3 sentiment even though Nubank trades mainly in New York. It tests whether investors will reward a large foreign expansion or punish the execution risk.
On the local board, Petrobras and Vale were the two most traded stocks on Monday. Petrobras preferred shares rose 1.35% and Vale 0.55%, and their opening direction will set the tone for the index.
The local corporate calendar is quiet, which leaves the macro agenda and the Nubank headlines in charge.
07 The levels to watch at the open
The real has been trading near the middle of its 52-week range, with the board showing it slightly weaker in the last session. At 5.2255 per US dollar, it sits between a 52-week low of 4.8909 and a high of 5.5901. A hot inflation print or poll surprise could push it weaker.
For the Ibovespa, the recent slide has left it about 7.9% below its 52-week closing high of 198,657. The index has fallen four straight sessions, so today’s data either validates the cautious mood or offers a reason to buy the dip.
Financials are the sector to watch. Banks fell on Monday—Itaú lost 1.00% and Bradesco 1.23%—and they are sensitive to both the Selic path and fiscal risk.
The opening hour may be choppy, with the IGP-M and labour figures landing in quick succession. Traders should watch whether the real holds its ground through that news flow rather than reacting to the first print in isolation.
08 What to watch
- IGP-M inflation at 08:00 BRT: A print near the top of the 0.6% to 1.7% forecast range would signal wholesale price pressure and cool Copom easing hopes
- Treasury result at 15:30 BRT: A central government deficit wider than R$14.2 billion (about US$2.7 billion) would weigh on the real and local rates
- Unemployment and Caged payrolls: A tight labour market with strong job creation is the clearest reason for the Copom to stay cautious
- Nubank-Monzo talks: After Monday’s 10.0% fall in New York, watch for any confirmation or denial of the talks
Background: Brazil’s Nubank in Talks to Buy Britain’s Monzo, Sky News Reports.
Background: What Is Vale? Brazil’s Mining Giant Explained: Iron Ore, the Dam Legacy and What to Watch.
More: Brazil news, every day from The Rio Times.
Frequently Asked Questions
What is the current Selic rate?
The Selic, Brazil’s benchmark interest rate, stands at 13.75% after the Copom cut it by 25 basis points on 16 September. The next decision is due on 4 November.
What data matters most for B3 today?
The IGP-M inflation index at 08:00 BRT and the unemployment rate at 09:00 BRT are the key early drivers. Caged payrolls and the Treasury’s August result follow in the afternoon.
Why is Nubank in focus on a Brazilian morning?
Reports of early-stage talks to buy UK digital bank Monzo sent Nubank’s New York-listed shares down 10.0% on Monday. No deal has been announced.
What is the fiscal constraint on the Copom?
Large deficits raise doubts about Brazil’s public debt. That keeps long-term rates high and limits how far the central bank can cut without weakening the real.
Source: RT live market data, close of Monday 28 September 2026.
This article was produced by The Rio Times’ automated AI newsroom. Editorial responsibility: Matthias Camenzind, Publisher and Editor-in-Chief. The Rio Times also runs Ask Rio Times, which answers from 100,000+ of our own articles, the daily Latin America Power Map, and prediction-market odds on elections and markets.. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Brazil runoff, Sunday, October 25: Brazil runoff date. Latest: Brazil runoff polls, Flávio 51%, Lula 49%.