Brazil’s Financial Morning Call for Thursday, October 1, 2026
Key Facts
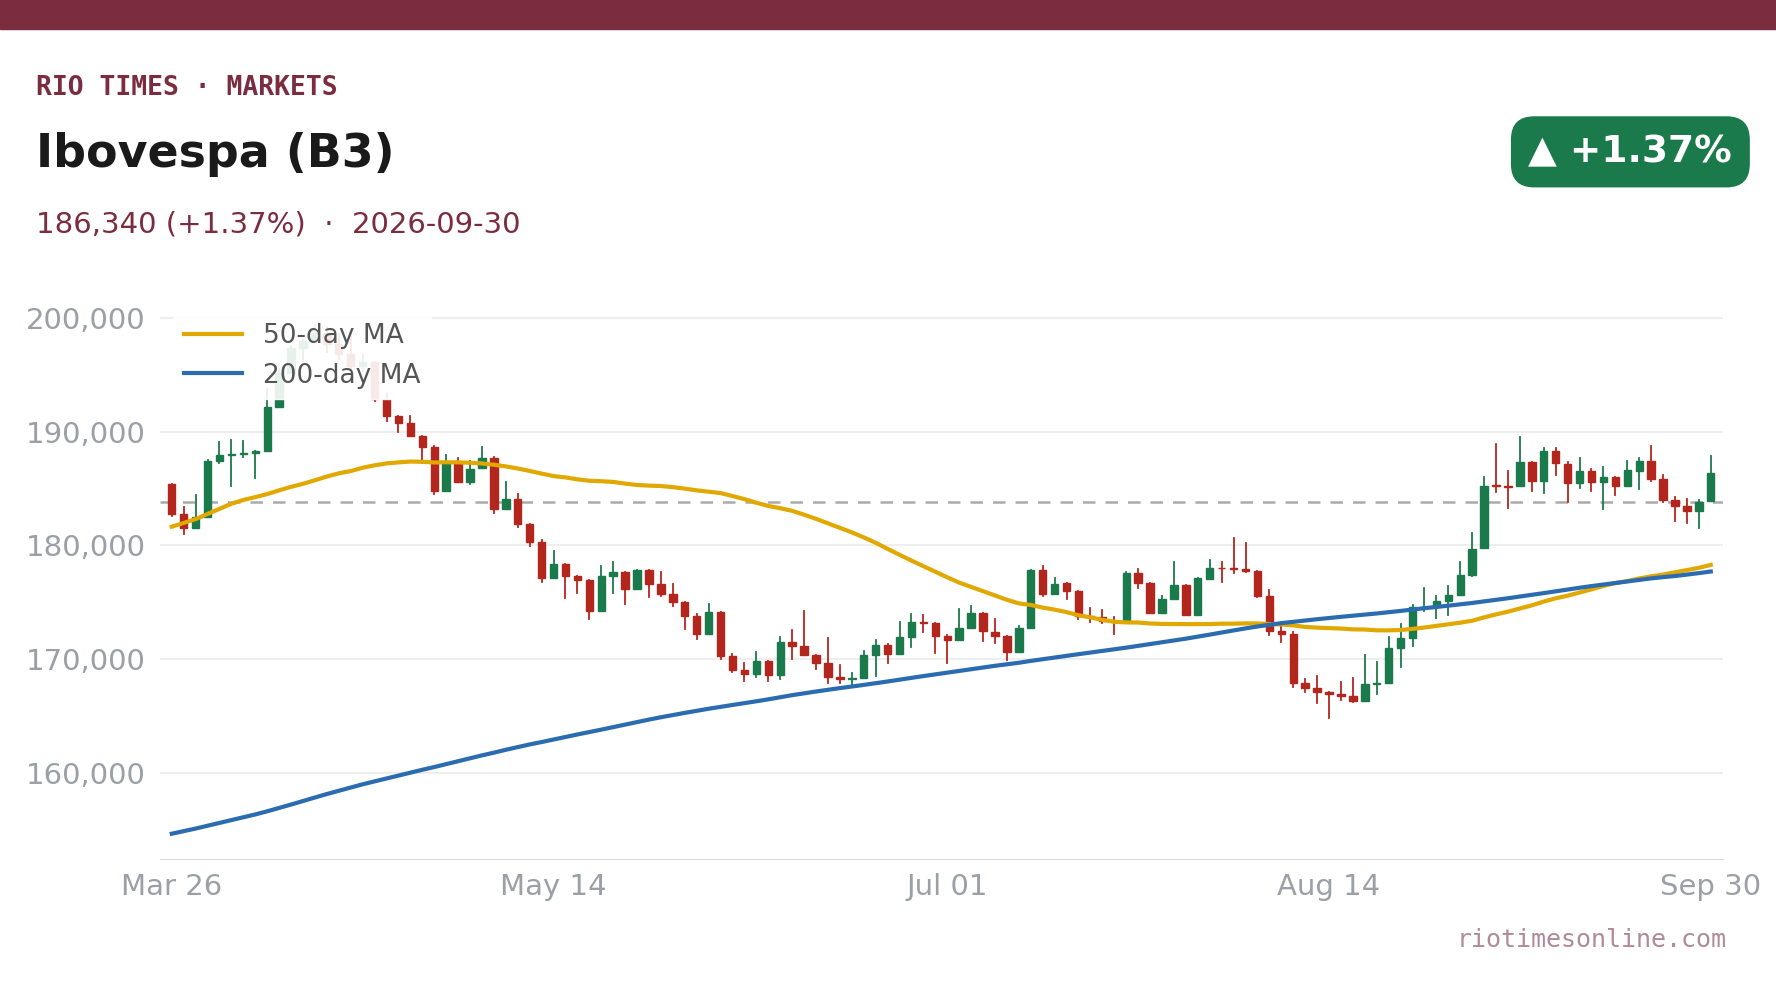
- Wednesday’s driver was US inflation: core PCE prices rose 3.0% on the year in August, below the 3.3% forecast, and the Ibovespa jumped 1.37% to 186,340, led by the big banks.
- Brazil’s fiscal data were mixed: the public sector ran a primary deficit of R$10.0 billion (US$1.9 billion) in August, but gross debt rose to 82.9% of GDP, the highest since 2021.
- Today’s domestic data point is the S&P Global manufacturing PMI at 10:00 BRT, forecast at 46.5; August industrial production follows on Friday.
- The real enters the session at 5.174 per US dollar after firming 0.76%, with the Selic at 13.75% and the next Copom decision on 4 November.
- Sunday’s first round of the presidential election and Friday’s US payrolls are the week’s two big risk events.
Today’s Focus
B3 opens on Thursday after its best session since 10 September. The Ibovespa rose 1.37% to 186,340 on Wednesday, ending September up 5.03%, after softer US inflation data lifted emerging-market assets. Itaú Unibanco and Banco do Brasil each gained 4.7%.
The pre-market question is whether that rally can hold. Brazil’s own calendar is light: the S&P Global manufacturing PMI, due at 10:00 BRT, is expected at 46.5 after 46.3. Anything below 50 signals factory contraction. August industrial production and the IPC-Fipe inflation gauge follow on Friday.
The bigger tests are outside the data. The first round of the presidential election is on Sunday, 4 October, and the US payrolls report lands on Friday. The real closed at 5.174 per US dollar; a strong US jobs number would revive talk of another Fed rate rise and test it.
What matters today. Whether Wednesday’s bank-led rally gets follow-through before the election weekend, with the US ISM manufacturing index at 11:00 BRT the main external input.
Today’s Economic Events
| Instrument | Level | Session |
|---|---|---|
| Ibovespa (Brazil) | 186,340 | +1.37% |
| S&P 500 (US) | 7,652 | -0.25% |
| USD/BRL | 5.174 | -0.76% |
Source: RT live market data, close of Wednesday 30 September 2026.
01 The setup in one read
Brazil’s rate-sensitive assets open with the Copom’s easing path in the background. The central bank has cut the Selic to 13.75% a year, but its weekly Focus survey of economists puts inflation expectations at 4.99% for 2026 and 4.31% for 2027, above the 3% target. Economists expect the Selic to end the year at 13.50%.
Against that backdrop, today’s domestic data are modest. The S&P Global manufacturing PMI will show whether factories are still contracting; August industrial production on Friday is the harder number.
The real, Brazil’s currency, starts at 5.174 per US dollar after Wednesday’s 0.76% gain. The Focus survey sees it ending the year at 5.20 per US dollar.
The Copom’s easing trajectory is the market’s core assumption, yet it rests on two contested pillars: decelerating activity and a stable real. Today’s PMI and Friday’s industrial production test the first pillar. The second depends on Sunday’s election and on Friday’s US payrolls. Watch whether the real holds below 5.20 per US dollar; a move toward 5.30 would unwind the rate-cut trade.
02 Where Brazil is set to open
| Instrument | Last close | Indicated | Watch today |
|---|---|---|---|
| Ibovespa — Brazil’s benchmark share index | 186,340 (+1.37%) | — | Follow-through above 186,000 after the bank-led rally |
| USD/BRL — Brazilian reais per US dollar | 5.174 (−0.76%) | — | Wednesday’s low of 5.1631; 5.20 above |
| Brazil 10-year bond yield | 14.16% (+2.5 bp) | — | Election-week risk premium |
| Dollar index (DXY) | 101.45 (+0.08%) | — | US ISM manufacturing at 11:00 BRT |
| iShares MSCI Brazil ETF (EWZ) | US$37.25 (+2.14%) | — | New York’s read on Brazilian assets |
There is no pre-market indication for the Ibovespa or dollar-real. The EWZ fund, which tracks Brazilian stocks in New York, rose 2.14% on Wednesday, in step with the local rally. The real’s level is the quiet anchor behind every sector; a move away from it changes the Copom calculus faster than any domestic data point.
Turnover leaders from the latest session — Itaú, Vale, Petrobras — remain the liquidity heart of the exchange. Itaú alone traded R$3.27 billion (US$632 million) on Wednesday. Their opening tone shows how foreign money is thinking about Brazil before the election.
Live Market IntelligenceBrazil Morning Call — Live Board
Rio Times · Live Market Intelligence
Brazil Morning Call — Live Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IBOV | 186,340.46 | +1.37% | +21.85% | 183,827.59 | 168,310 | 167,142 | — |
| USD/BRL | 5.16 | +0.01% | -5.13% | 5.16 | 5.18 | 5.14 | — |
| EUR/BRL | 5.95 | +1.01% | -5.83% | 5.89 | 5.98 | 5.94 | — |
| SELIC | 14.00% | — | — | — | — | — | |
| BRENT | 88.88 | -0.03% | +34.42% | 88.91 | 90.07 | 88.12 | 29,713 |
| WTI | 83.11 | -0.11% | +31.57% | 83.20 | 84.35 | 82.40 | 166,848 |
| IRON ORE | 161.91 | — | +58.10% | 161.91 | 161.91 | 1 | |
| GOLD | 4,461 | +1.78% | +33.20% | 4,383 | 4,503 | 4,421 | 139,824 |
| SILVER | 65.59 | +1.26% | +73.05% | 64.77 | 66.98 | 64.81 | 46,406 |
| LITHIUM | 75.20 | +1.47% | +62.95% | 74.11 | 75.80 | 75.08 | 89,275 |
| SOY | 1,184 | +3.20% | +17.05% | 1,148 | 1,199 | 1,168 | 163,179 |
| CORN | 480.50 | +10.02% | +29.34% | 436.75 | 480.75 | 459.50 | 341,248 |
| WHEAT | 655.00 | +3.93% | +29.70% | 630.25 | 657.75 | 631.50 | 128,793 |
| COFFEE | 317.25 | -5.51% | +0.67% | 335.75 | 321.20 | 313.55 | 21,747 |
| SUGAR | 16.43 | -1.79% | -3.01% | 16.73 | 17.11 | 16.22 | 171,992 |
| ORANGE JUICE | 138.55 | -0.47% | -45.38% | 139.20 | 141.05 | 137.50 | 703 |
| COTTON | 85.03 | +2.33% | +26.78% | 83.09 | 82.90 | 81.96 | 16,546 |
| BEEF | 223.60 | -3.93% | -5.18% | 232.75 | 226.40 | 223.00 | 16,126 |
| CATTLE | 339.10 | -3.16% | -1.82% | 350.17 | 345.50 | 338.60 | 10,164 |
| COCOA | 5,719 | +3.18% | -34.96% | 5,543 | 5,779 | 5,574 | 26,773 |
| PETR4 | 41.64 | -0.05% | +35.19% | 41.66 | 41.97 | 41.15 | 41,499,400 |
| VALE3 | 72.97 | +0.83% | +30.75% | 72.37 | 73.54 | 72.66 | 17,658,000 |
| SUZB3 | 41.33 | +2.35% | -23.55% | 40.38 | 41.48 | 40.35 | 3,914,900 |
| KLABIN | 17.69 | +0.80% | -2.95% | 17.55 | 17.74 | 17.48 | 2,057,400 |
| SLCE3 | 13.34 | +0.30% | -12.25% | 13.30 | 13.42 | 13.20 | 1,454,200 |
| ABEV3 | 14.89 | -0.80% | +21.91% | 15.01 | 15.07 | 14.81 | 16,453,100 |
| ITUB4 | 38.60 | -1.03% | +4.57% | 39.00 | 39.34 | 38.39 | 29,487,800 |
| BBDC4 | 16.85 | +0.36% | +3.50% | 16.79 | 16.90 | 16.67 | 19,416,900 |
| BBAS3 | 19.37 | +0.47% | +0.73% | 19.28 | 19.44 | 19.16 | 11,069,200 |
| B3SA3 | 14.26 | -0.21% | +12.73% | 14.29 | 14.47 | 14.11 | 33,037,800 |
| WEGE3 | 47.59 | +0.49% | +29.99% | 47.36 | 48.08 | 47.36 | 3,364,600 |
| PRIO3 | 59.14 | -0.19% | +50.67% | 59.25 | 59.81 | 58.74 | 3,325,600 |
| RENT3 | 34.68 | -0.09% | +0.84% | 34.71 | 34.96 | 34.35 | 7,979,100 |
| AZZA3 | 15.89 | -2.63% | -53.76% | 16.32 | 16.42 | 15.82 | 1,330,300 |
| CSNA3 | 4.30 | +0.47% | -42.65% | 4.28 | 4.41 | 4.26 | 10,076,100 |
| GGBR4 | 24.69 | +2.19% | +51.38% | 24.16 | 24.85 | 24.18 | 7,047,600 |
| ENEV3 | 24.21 | -1.38% | +70.49% | 24.55 | 24.64 | 23.99 | 9,297,000 |
| LREN3 | 11.87 | -1.33% | -28.65% | 12.03 | 12.17 | 11.83 | 9,683,300 |
03 On the B3 radar today — data and silence
| Item | When | Why it matters |
|---|---|---|
| S&P Global manufacturing PMI, September | 10:00 BRT | Below 50 signals contraction; weighs on steel and capital-goods shares |
| Election polls | During the day | Final surveys before Sunday’s 4 October first round |
| IPC-Fipe inflation, September | Fri 05:00 BRT | São Paulo consumer prices, forecast at 0.3% after 0.01% |
| Industrial production, August | Fri 09:00 BRT | Forecast at 0.1% on the month; the Copom’s best evidence of a slowdown |
| Earnings and ex-dividends | — | No verified B3 corporate result or payout event found for today |
The radar is thin on corporate news and thick on macro and politics. The PMI lands at 10:00 BRT, as B3 opens, so the first trades will also reflect the overnight global tone.
The heavier Brazilian data arrive on Friday, when the IPC-Fipe and industrial production land on the same morning as US payrolls.
04 Copom and the macro backdrop
The Copom’s September decision cut the Selic to 13.75% a year, following a move to 14.00% in August. Inflation expectations remain above the 3% target, which limits how fast the bank can move. The next decision is on 4 November.
The market is pricing a slow continuation of this path, and the real’s stability is what makes it possible. A weaker real would feed imported inflation and narrow the room for cuts.
Friday’s US payrolls add suspense. New York Fed President John Williams said on Tuesday that one further US rate rise may be appropriate late this year. If American hiring comes in soft, the dollar may weaken and give the real room to breathe.
05 Wednesday’s data, one by one
Our Wednesday edition flagged Brazil’s fiscal accounts and producer prices, Chile’s data, US jobs and inflation figures, Colombia’s rate decision, quarter-end and the election. Here is how each landed.
Public accounts (central bank), 08:30 BRT. The consolidated public sector posted a primary deficit of R$10.0 billion (US$1.9 billion) in August, against R$17.3 billion (US$3.3 billion) a year earlier. Interest costs of R$105.9 billion (US$20.5 billion) took the nominal deficit to R$115.9 billion (US$22.4 billion), wider than the R$109 billion (US$21 billion) we flagged. Gross debt rose to 82.9% of GDP, just under the 83.1% forecast but the highest since 2021. The real still firmed.
Producer prices (IBGE), 09:00 BRT. Factory-gate prices rose 0.36% in August, against a forecast fall of 0.4% and after a 0.83% drop in July. They are up 2.53% over 12 months. Food producers led. The market ignored it.
Chile (INE), 09:00 BRT. Unemployment rose to 9.6% in the June–August quarter, against 9.5% expected. Industrial production fell 5.7% on the year in August, worse than the 3.0% drop forecast, and copper output was 12.8% lower. Chile’s IPSA fell 0.78%.
United States, 09:15 and 09:30 BRT. ADP counted 90,000 private jobs in September, above the 70,000 forecast. August PCE inflation was 3.4% on the year against the 3.7% we flagged; core PCE was 3.0% against 3.3%. This was the day’s main driver: the Ibovespa rose 1.37% and the real firmed, although the US 10-year yield still rose to 5.291%.
Colombia, 15:00 BRT. Banco de la República surprised with a quarter-point rise to 12.25%; a hold at 12% had been expected. Colombia’s COLCAP fell 0.38%.
Quarter-end and election. The Ibovespa ended the third quarter 8.3% higher. Polls ahead of Sunday’s first round still show a close race between President Luiz Inácio Lula da Silva and Senator Flávio Bolsonaro.
06 Corporate stories to watch today
No verified B3 earnings or ex-dividend events are scheduled for today, but the rate-sensitive complex is the story. Homebuilders, retailers and banks move on Selic expectations even without company-specific news. Magazine Luiza jumped 12.5% on Wednesday, and Totvs fell 3.5%.
Turnover leaders from the latest session — Itaú, Vale, Petrobras — are the names where foreign positioning concentrates ahead of US payrolls. Vale also faces a quiet week for iron-ore signals, because mainland China is on its Golden Week holiday until 7 October.
07 The levels to watch at the open
For the Ibovespa, the 186,000 zone is the psychological hinge after the latest session’s advance. A clean hold above that level keeps the positive domestic narrative intact; a slide back below it would suggest the rally lacked follow-through.
For the real, Wednesday’s close at 5.174 per US dollar and the 5.20 mark above it are the battleground. A move toward 5.30 would unwind the easing wager quickly, hitting rate-sensitive shares first.
Interest-rate futures merit watching alongside the spot market. If the short end flattens, traders are confident in another cut; if it steepens, inflation doubts are creeping back in.
08 What to watch
- Brazil manufacturing PMI, 10:00 BRT: Forecast at 46.5 after 46.3; below 50 signals contraction and pressures cyclical shares
- US data, 09:30 and 11:00 BRT: Weekly jobless claims (200,000 expected), then the ISM manufacturing index, forecast at 55.0 after 54.6
- Fed speakers: Collins, Schmid, Waller, Bowman, Williams and Logan speak today, after Wednesday’s softer inflation data
- Election polls: Final surveys before Sunday’s 4 October first round; Friday brings US payrolls (about 90,000 expected) and Brazil’s August industrial production
Background: Brazil Ibovespa Closes 1.4% Higher at 186,340 as Banks Lead and the Real Firms.
Frequently Asked Questions
What is the Selic and why does it move B3?
The Selic is Brazil’s benchmark interest rate, set by the Copom. Lower rates make borrowing cheaper and typically lift rate-sensitive shares like retailers and homebuilders.
Why does Sunday’s election matter for markets?
The first round of Brazil’s presidential election is on 4 October. Investors watch it for signals on public spending and debt, which feed into the real, interest rates and bank shares.
What is the Copom’s current rate path?
The bank cut the Selic to 13.75% a year in September, after a cut to 14.00% in August. Further cuts are expected but limited by above-target inflation expectations.
Are there any big Brazilian corporate events today?
No verified B3 earnings or ex-dividend events were found for today. The macro calendar is the main driver at the open.
Source: RT live market data, close of Wednesday 30 September 2026; fiscal data from the Central Bank of Brazil; producer prices from IBGE.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.