Key Facts
- London copper held steady: three-month copper on the London Metal Exchange stood at US$14,416.50 a tonne at 16:00 GMT on Wednesday, September 30, 2026, down 0.1%, according to Reuters. At that point it was on course for a 0.9% gain in September and was up 7.9% in the third quarter.
- Chile’s output slumped: the national statistics institute INE said Chile mined 369,500 tonnes of copper in August, down 12.8% year on year and the lowest monthly figure since February 2011.
- Centinela strike risk stays open: unions at Antofagasta Minerals’ Centinela mine are in five-day government mediation after 98.73% of members voted to strike. No strike has started.
- The US proxies slipped: the CPER copper fund fell 0.38% to US$39.78. Freeport-McMoRan lost 1.12% to US$70.00, while Southern Copper edged up 0.04% to US$202.64.
- China’s factories grew: the official September manufacturing PMI rose to 50.1 from 49.8. Shanghai copper stocks fell 17.8% in a week to 38,744 tonnes, the lowest since January 2024.
- The dollar capped prices: the dollar index closed at 101.45, its highest since late July, and the 10-year Treasury yield rose to 5.29%.
Today’s Focus
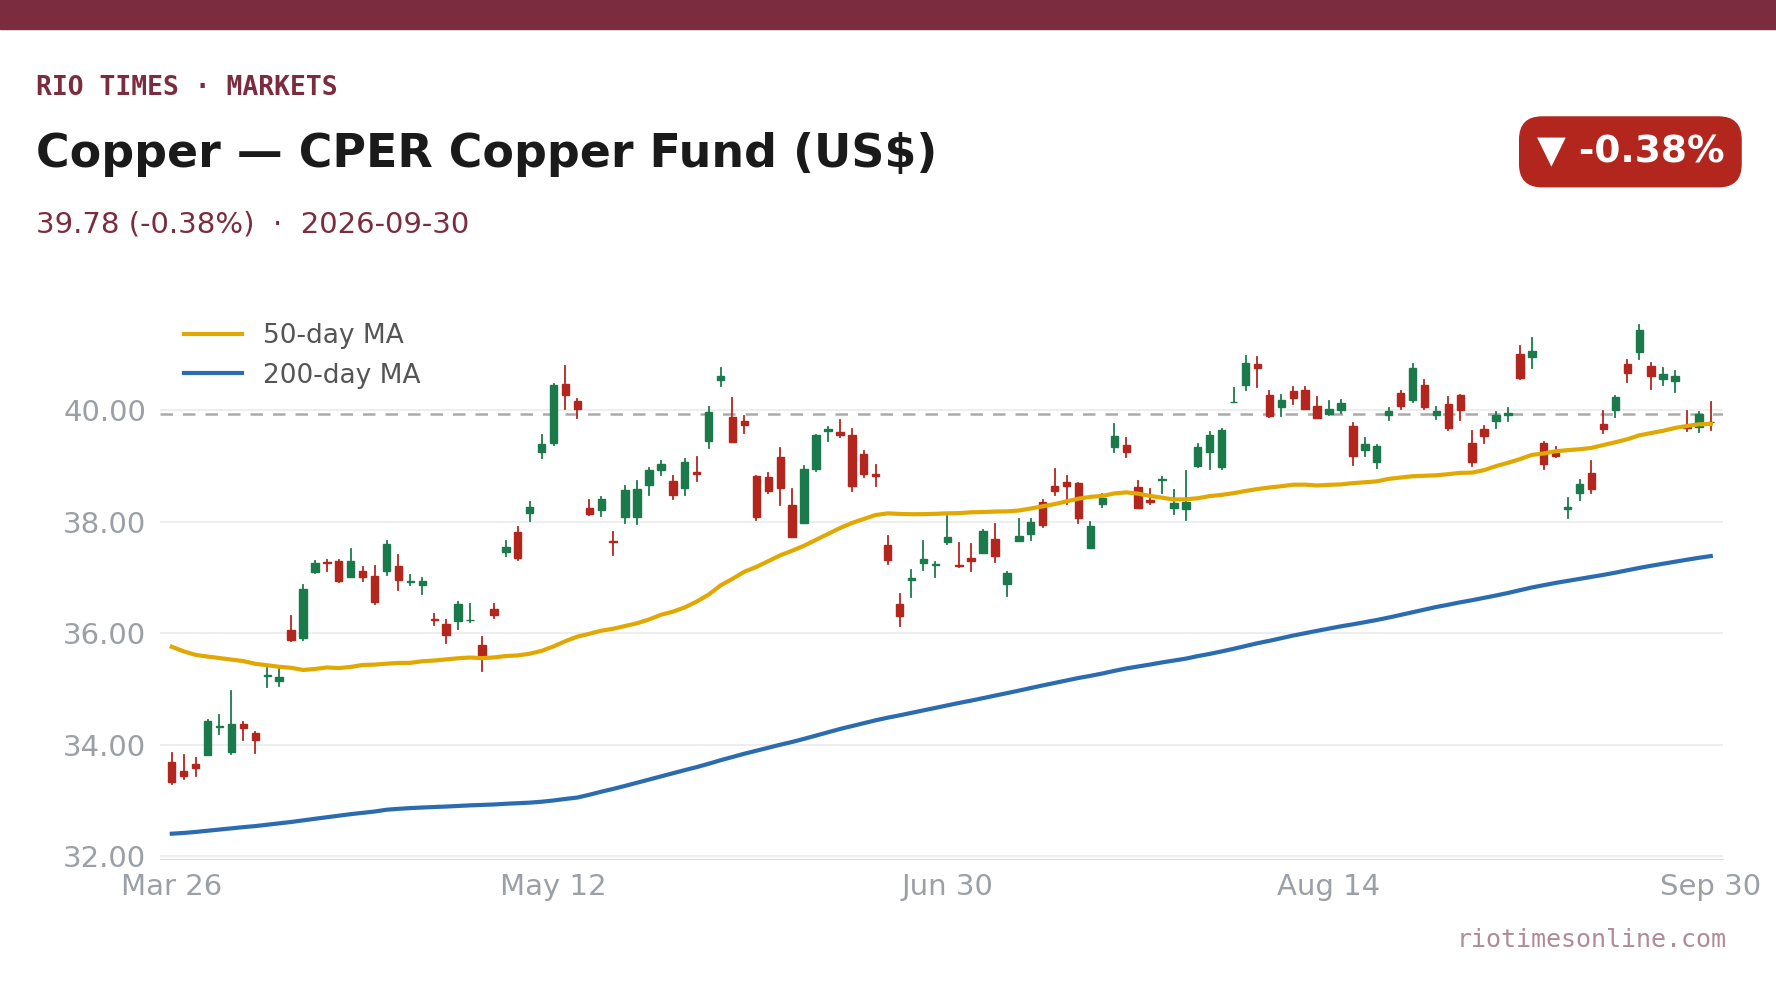
Copper held steady on Wednesday, September 30, 2026. Three-month copper in London stood at US$14,416.50 a tonne late in the session, down 0.1%, according to Reuters. In New York, the CPER fund, which tracks copper futures, fell 0.38% to US$39.78.
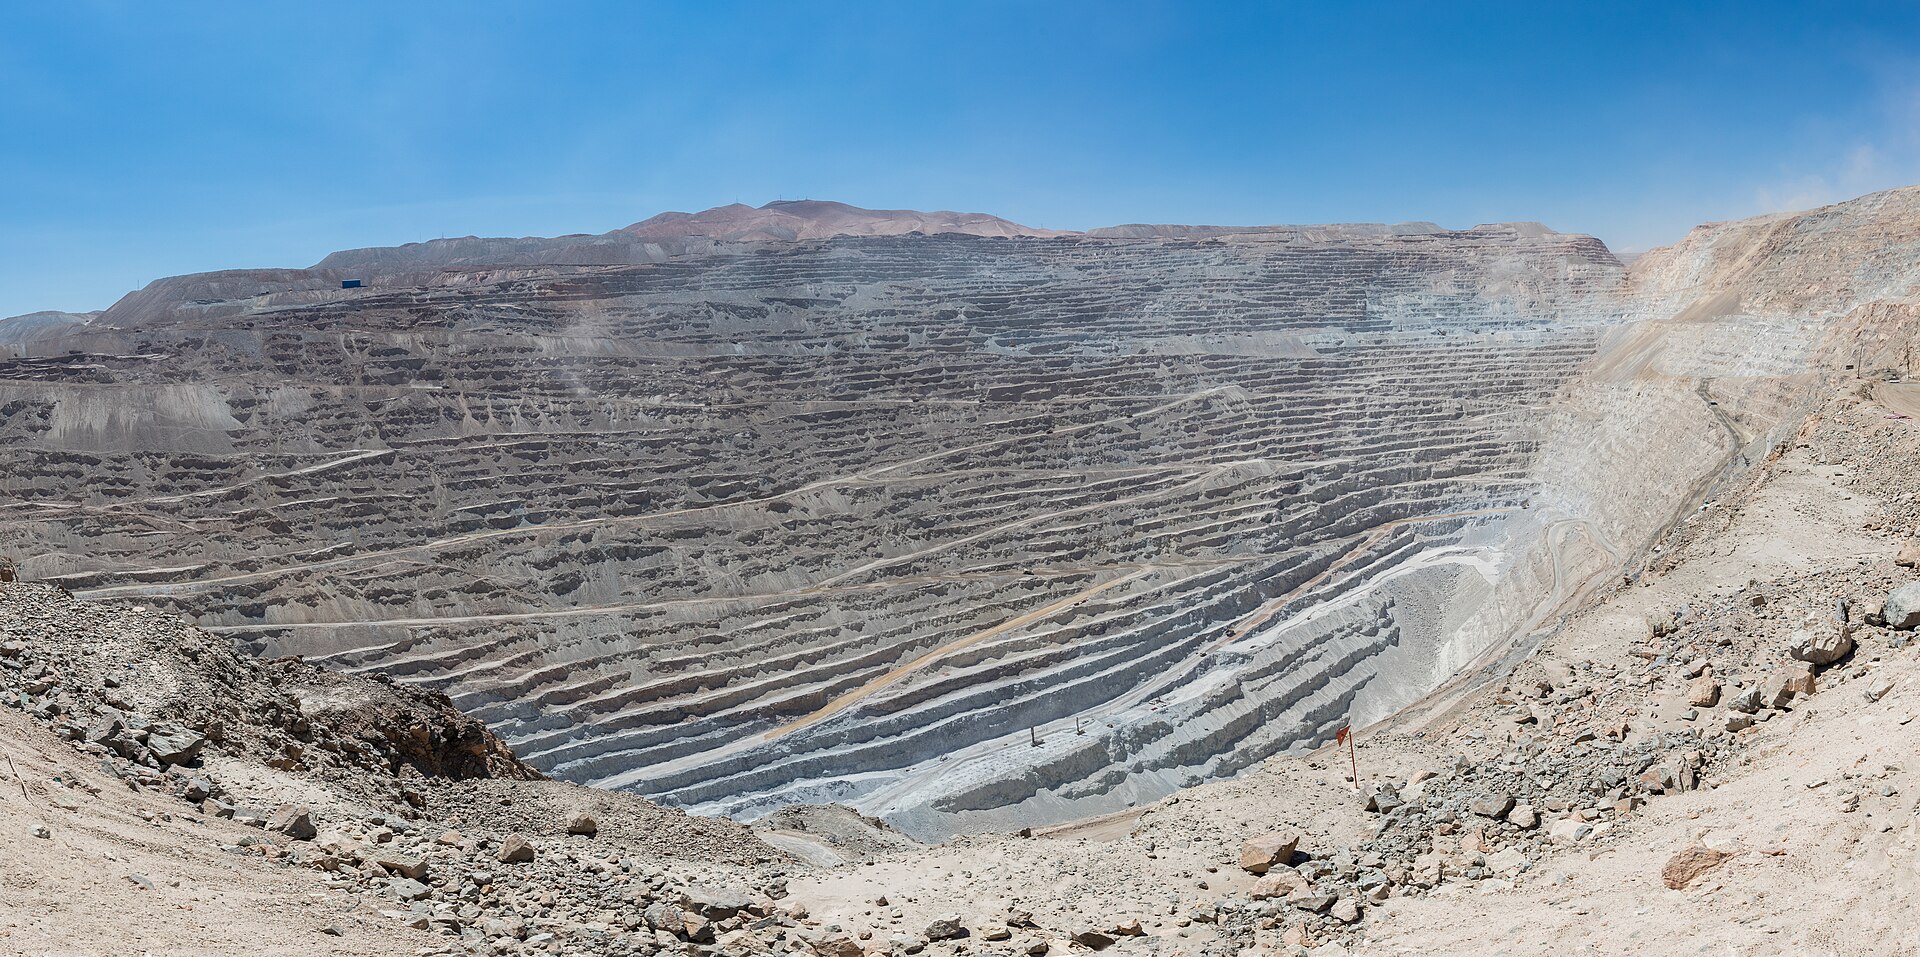
Chile supplied the day’s main news. The national statistics institute INE said the country mined 369,500 tonnes of copper in August, 12.8% less than a year earlier. It was the lowest monthly output since February 2011. Weather damage, operational problems and lower ore grades at major mines weighed on production.
Strike risk is also rising. Unions at Antofagasta Minerals’ Centinela mine rejected the company’s offer, with 98.73% voting to strike. A five-day government mediation is under way, and it can be extended by five days. A legal strike can only follow if talks fail.
Supply worries kept a floor under prices, but a firmer dollar and rising US yields capped them. Copper was still on course for its third straight monthly gain, and Chinese markets are now closed for the Golden Week holiday until October 7.
What matters today. Chile’s weakest copper output in 15 years and the Centinela strike threat are keeping supply risk at the centre of the market as China goes on holiday.
01 The session in one read
London copper eased 0.1% to US$14,416.50 a tonne on Wednesday, September 30, 2026, according to Reuters. It was on course for a 0.9% gain in September and was up 7.9% in the third quarter, below the record high of US$14,875 set on September 10.
In New York, the CPER fund closed at US$39.78, down 0.38%. Freeport-McMoRan fell 1.12% to US$70.00, its lowest close of the week, while Southern Copper edged up 0.04% to US$202.64.
Chile’s August figures confirm that the world’s largest producer is struggling to keep output up. Together with the Centinela dispute, that gives copper a firm floor. But the dollar index is at its highest since late July and long-term US yields are still rising, which limits gains. With Chinese buyers away for Golden Week, trading may be thin until October 8. The next signals are Chile’s August activity index on Thursday and the outcome of the Centinela mediation.
02 The board
The CPER fund follows copper futures, not physical metal, so its 0.38% drop reflects futures pricing at the US close. It ended September down 0.55% but the third quarter up 5.4%.
The producers split. Southern Copper, which mines in Peru and Mexico, closed flat at US$202.64. Freeport-McMoRan, which runs the Cerro Verde mine in Peru, extended its losing run to a third day.
| Asset | Level | Change |
|---|---|---|
| Copper (CPER tracker) | US$39.78 | -0.38% |
| Southern Copper | US$202.64 | +0.04% |
| Freeport-McMoRan | US$70.00 | -1.12% |
Source: RT live market data, close of Wednesday 30 September 2026. CPER is an exchange-traded fund that tracks copper futures and is shown as a labelled proxy.
Live Market IntelligenceThe live market board
Rio Times · Live Market Intelligence
Latin America — Cross-Market Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IBOV | 186,340.46 | +1.37% | +21.85% | 183,827.59 | 168,310 | 167,142 | — |
| IPSA | 10,969.49 | -0.78% | — | 11,055.94 | 11,210 | 10,984 | 1,513,213,483 |
| IPC MEX | 64,214.36 | -1.38% | +12.17% | 65,110.57 | 66,121 | 65,405 | 108,886,187 |
| MERVAL | 2,819,323 | +1.32% | +30.51% | 3,022,485 | 3,042,365 | 2,991,150 | — |
| COLCAP | 2,549.16 | -0.38% | — | 9.04 | 9.05 | 9.02 | 4,133 |
| BVL PERÚ | 60,410.88 | -0.96% | — | — | — | — | — |
| USD/BRL | 5.16 | +0.01% | -5.13% | 5.16 | 5.18 | 5.14 | — |
| EUR/BRL | 5.95 | +1.01% | -5.83% | 5.89 | 5.98 | 5.94 | — |
| USD/MXN | 17.06 | -0.24% | -8.58% | 17.10 | 17.08 | 17.01 | — |
| USD/CLP | 913.98 | +0.04% | -5.67% | 913.65 | 915.11 | 906.68 | — |
| USD/COP | 3,140 | +0.03% | -22.04% | 3,139 | 3,141 | 3,105 | — |
| USD/PEN | 3.36 | -0.66% | -4.82% | 3.38 | 3.38 | 3.35 | — |
| USD/ARS | 1,493 | +0.10% | +12.96% | 1,491 | 1,494 | 1,480 | — |
| USD/UYU | 40.27 | +1.24% | +1.80% | 39.77 | 40.27 | 40.23 | — |
| USD/PYG | 5,939 | +1.68% | -19.54% | 5,841 | 5,939 | 5,925 | — |
| USD/BOB | 11.64 | -0.76% | +72.04% | 11.73 | 11.72 | 11.64 | — |
| USD/DOP | 58.34 | +1.25% | -3.44% | 57.62 | 58.34 | 58.04 | — |
| USD/CRC | 445.92 | +0.89% | -9.71% | 441.97 | 448.50 | 445.92 | — |
03 What moved it
Supply news gave copper its support. Chile’s 12.8% fall in August output was far deeper than the 9.4% drop in July. Lower output at state-owned Codelco and at BHP’s Escondida and Spence mines has weighed on Chilean production this year, according to reports on the INE data.
Chinese demand signals were mixed but positive. The official manufacturing PMI returned to growth at 50.1, and copper stocks in Shanghai warehouses fell to their lowest since January 2024. ING strategist Ewa Manthey said “structural demand trends and constrained supply growth should help keep prices well supported through Q4”, according to Reuters.
The cap came from the dollar and yields. Softer US inflation cut the odds of an October Fed hike, but the 10-year Treasury yield still rose to 5.29%. The dollar index firmed 0.08% to 101.45, which makes dollar-priced copper dearer for buyers using other currencies.
04 Wednesday’s data, one by one
- Chile copper production (August): 369,500 tonnes, down 12.8% year on year after a 9.4% fall in July, according to INE. It was the lowest monthly output since February 2011 and the day’s key release for copper.
- Chile industrial production (August): down 5.7% year on year, worse than the 3.0% fall forecast and the 5.1% drop in July. Manufacturing fell 2.6%, against a 1.7% forecast.
- Chile unemployment (June–August): 9.6%, slightly above the 9.5% forecast and up from 9.5%. Retail sales rose 3.4% year on year, above the 2.0% forecast.
- China PMIs (September): the official manufacturing PMI rose to 50.1 from 49.8, in line with forecasts, and the non-manufacturing PMI to 50.2 from 49.0. The S&P Global manufacturing PMI reached 52.1, above the 51.6 forecast. The data support demand, but Chinese buying slows over the holiday.
- US PCE inflation (August): 3.4% year on year, below the 3.7% forecast; core 3.0%, against 3.3% expected. We flagged a hot reading as a risk. It came in soft, but long-term yields and the dollar still rose.
- Colombia rate decision: Banco de la República raised its policy rate by 25 basis points to 12.25%, against a calendar consensus of no change, in a 4–2–1 vote. It had no visible effect on copper.
- Japan Tankan (third quarter): the large manufacturers’ index rose to 24 from 22, just below the 25 forecast, a steady read for a major copper-consuming economy.
- Centinela mediation: we flagged whether a deal would come before the five-day mediation ends. No agreement was reported by Wednesday, and talks continue.
05 The Latin American read
Chile and Peru mined about 35% of the world’s copper in 2025, according to the US Geological Survey. Chile ranks first and Peru third, behind the Democratic Republic of Congo.
Chile’s slump matters well beyond the mining sector. Copper is the country’s largest export, and weaker output reduces export revenue and royalty income even when prices are high.
For Peru, the tight Chilean supply is a chance to gain share. Its large mines, such as Southern Copper’s Toquepala and Cuajone, Freeport’s Cerro Verde and the Antamina mine co-owned by BHP and Glencore, benefit from high prices.
06 The names to watch
Antofagasta Minerals is the immediate focus. Centinela produced 240,400 tonnes of copper in 2025, according to Shanghai Metals Market, so a strike would remove a meaningful share of Chilean supply.
Codelco’s monthly output figures remain the key gauge of Chile’s recovery. Outside the region, a Panamanian government study recommended negotiating an arrangement that could allow a temporary restart of First Quantum’s Cobre Panamá mine, shut since 2023, to help its orderly closure, according to Reuters. It is a recommendation, not a decision.
07 The outlook
Copper enters the fourth quarter after three straight monthly gains and with supply still under pressure in Chile. The main risks to the copper price are a stronger dollar and rising US yields rather than weak demand. With Shanghai closed until October 8, London will set prices this week, and the Centinela talks could move the market at short notice.
08 What to watch
- China Golden Week: mainland Chinese markets, including the Shanghai Futures Exchange, are closed from October 1 to 7. Expect thinner trading in London.
- Chile economic activity (August): the IMACEC index is due at 11:30 UTC (08:30 BRT); forecast −0.4% year on year after −1.5%. Mining weakness is likely to weigh.
- Centinela mediation: whether Antofagasta Minerals and the unions reach a deal before the mediation period ends or is extended.
- US ISM manufacturing (September): 14:00 UTC (11:00 BRT); the PMI is forecast at 55.0 after 54.6. A strong reading would support industrial demand but could also lift the dollar.
- Mexico manufacturing PMI (September): 15:00 UTC (12:00 BRT); forecast 50.0 after 49.8.
Frequently Asked Questions
Why did copper hold steady on Wednesday, September 30, 2026?
Chile’s weak August output and the Centinela strike threat supported prices, while a firmer dollar and rising US yields capped them. London copper eased 0.1% to US$14,416.50 a tonne.
How much did Chile’s copper output fall in August?
Chile mined 369,500 tonnes of copper in August, down 12.8% year on year and the lowest monthly figure since February 2011, according to the statistics institute INE.
What is happening at the Centinela mine?
Unions at Antofagasta Minerals’ Centinela mine voted 98.73% to strike after rejecting the company’s offer. A five-day government mediation is under way, and no strike has started.
Why does China’s Golden Week matter for copper?
China is the largest copper consumer. Its markets are closed from October 1 to 7, so Chinese buying slows and London sets prices with thinner trading.
Source: RT live market data, close of Wednesday 30 September 2026.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
In depth
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Read More from The Rio Times