Zinc Slips to US$3,842 as Backwardation Widens and Nexa Falls 1.5%
Key Facts
- LME zinc eased. The official three-month price fell 0.75% to US$3,842 a tonne on Wednesday, 30 September 2026, and the cash settlement price fell 0.58% to US$3,954.
- Nearby metal stayed tight. The premium of cash over three-month zinc widened to US$112 a tonne from US$106 on Tuesday, the widest since 15 September on official prices.
- LME stocks fell 1,950 tonnes to 121,600 tonnes, with 11,250 tonnes, or 9.25%, earmarked for withdrawal.
- Shanghai zinc slipped 0.36% to 26,435 yuan (about US$3,943) a tonne in the last session before China’s 1–7 October National Day holiday.
- Nexa Resources fell 1.53% to US$12.19 and Buenaventura 1.28% to US$31.58.
- Peru’s zinc output fell 12% year on year to 746,000 tonnes in January–July 2026, according to the Ministry of Energy and Mines.
Today’s Focus
Zinc eased on Wednesday, 30 September 2026, but nearby metal stayed tight. The LME official three-month price fell 0.75% to US$3,842 a tonne, while the premium for cash metal over three-month metal widened to US$112 a tonne from US$106 on Tuesday.
Peru’s falling mine output underpins that tightness. The country produced 746,000 tonnes of zinc in concentrate in January–July 2026, down 12% year on year. July output fell 11.1% to 102,100 tonnes, leaving smelters with less feed.
China was quiet. Shanghai zinc fell 0.36% to 26,435 yuan (about US$3,943) a tonne in its last session before the National Day holiday.
Equity proxies moved with the metal. Nexa Resources fell 1.53% to US$12.19 and Buenaventura lost 1.28% to US$31.58.
What matters today. Shanghai is shut until 8 October, so the LME alone sets the zinc price this week. The widening backwardation shows nearby supply is tight even as the outright price slips.
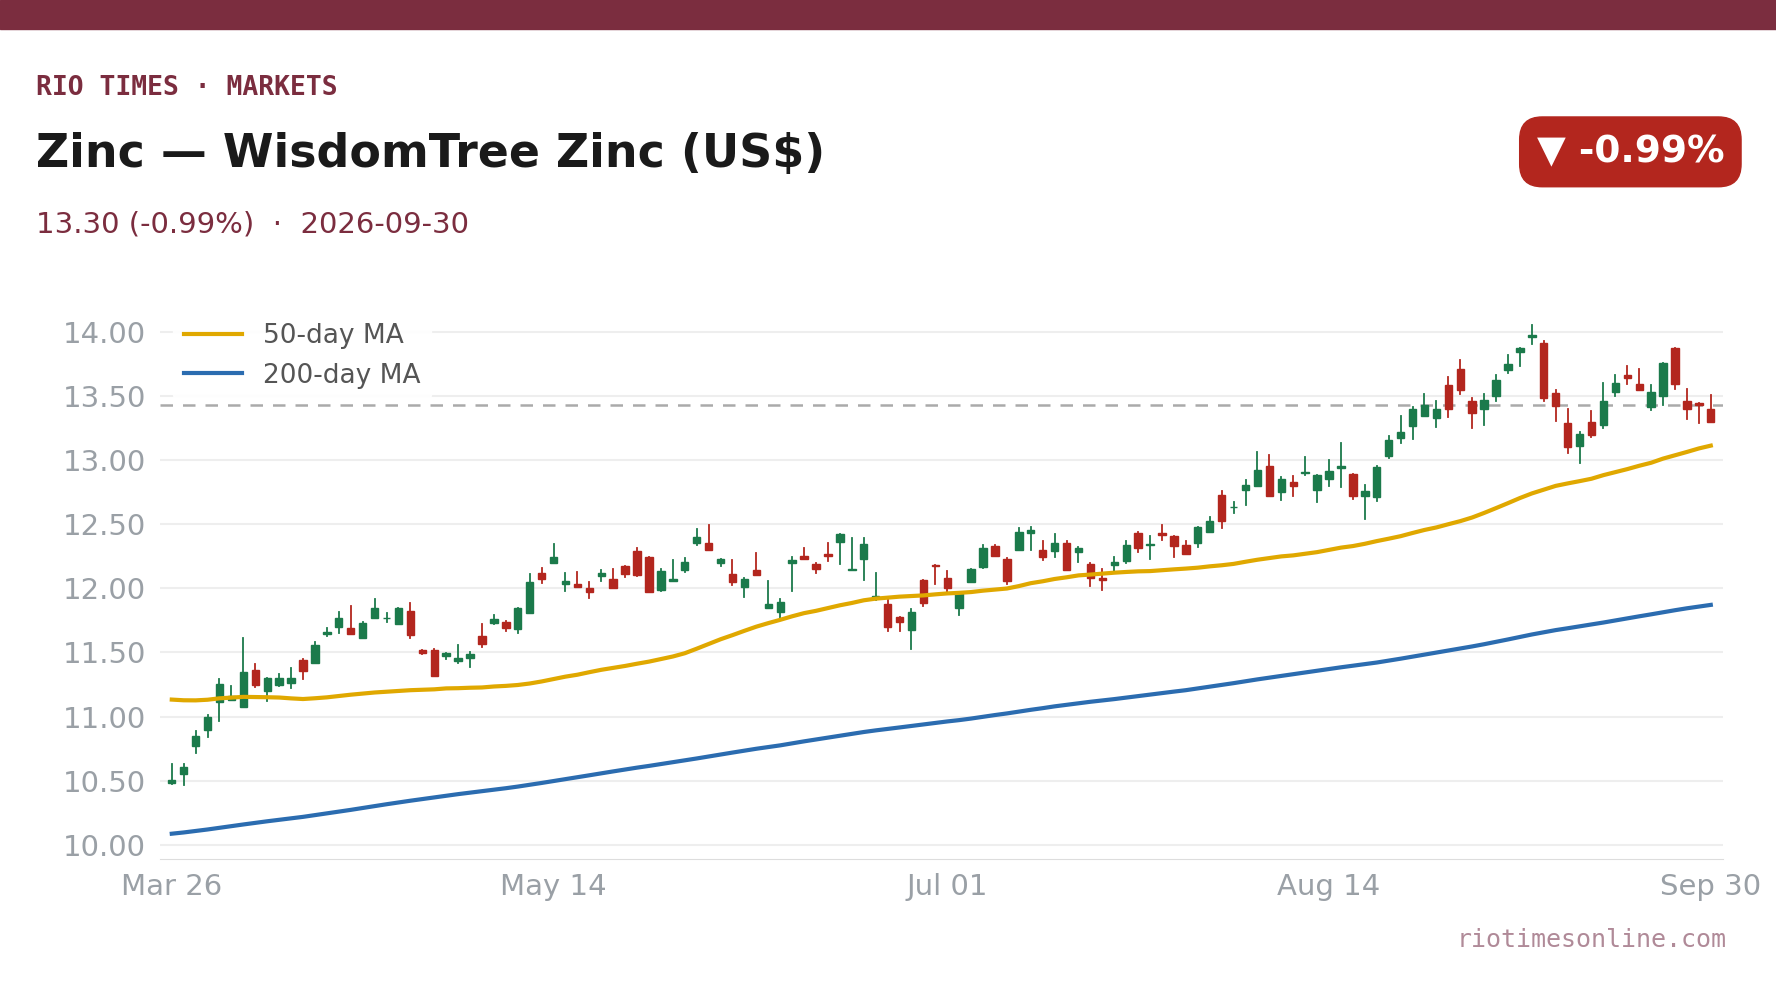
01 The session in one read
Zinc slipped on Wednesday, 30 September 2026. The LME official three-month price fell 0.75% to US$3,842 a tonne, and the cash settlement price fell 0.58% to US$3,954. The WisdomTree Zinc tracker in London lost 0.99% to US$13.30.
The spread tells a tighter story. Cash zinc traded US$112 a tonne above three-month metal, up from US$106 on Tuesday. That is a backwardation, meaning buyers pay more for metal they can take immediately.
Peru, the world’s second-largest zinc miner after China, is central to that tightness. Output of zinc in concentrate dropped 12% year on year to 746,000 tonnes in January–July 2026, and July production alone fell 11.1% to 102,100 tonnes.
The widening backwardation, now US$112 a tonne on official prices, is the clearest evidence that zinc is tight on the spot market, helped by a 12% fall in Peruvian mine output this year. What is missing is Chinese buying: Shanghai slipped 0.36% before the holiday. The variable to watch is whether Chinese construction and galvanising demand returns after the break strongly enough to lift prices alongside the physical premium.
02 The board
Latin America’s two main listed zinc proxies weakened along with the metal. Nexa Resources, the Peru- and Brazil-focused integrated miner and smelter, ended at US$12.19, down 1.53% on the session.
Buenaventura, the Peruvian precious and base metals producer, closed at US$31.58, a 1.28% decline. Both have now fallen in three of the last four sessions.
| Asset | Level | Change |
|---|---|---|
| Zinc, LME official three-month (per tonne) | US$3,842.00 | -0.75% |
| Zinc, LME cash settlement (per tonne) | US$3,954.00 | -0.58% |
| Zinc, Shanghai November (per tonne) | 26,435 yuan (US$3,943) | -0.36% |
| WisdomTree Zinc (London) | US$13.30 | -0.99% |
| Nexa Resources | US$12.19 | -1.53% |
| Buenaventura | US$31.58 | -1.28% |
Source: RT live market data, close of Wednesday 30 September 2026; LME official prices; Shanghai Futures Exchange (change against the previous settlement). Where a commodity has no spot feed, an exchange-traded tracker or leading producer is shown as a labelled proxy.
Live Market IntelligenceThe live market board
Rio Times · Live Market Intelligence
Latin America — Cross-Market Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IBOV | 186,340.46 | +1.37% | +21.85% | 183,827.59 | 168,310 | 167,142 | — |
| IPSA | 10,969.49 | -0.78% | — | 11,055.94 | 11,210 | 10,984 | 1,513,213,483 |
| IPC MEX | 64,214.36 | -1.38% | +12.17% | 65,110.57 | 66,121 | 65,405 | 108,886,187 |
| MERVAL | 2,819,323 | +1.32% | +30.51% | 3,022,485 | 3,042,365 | 2,991,150 | — |
| COLCAP | 2,549.16 | -0.38% | — | 9.04 | 9.05 | 9.02 | 4,133 |
| BVL PERÚ | 60,410.88 | -0.96% | — | — | — | — | — |
| USD/BRL | 5.16 | +0.01% | -5.13% | 5.16 | 5.18 | 5.14 | — |
| EUR/BRL | 5.95 | +1.01% | -5.83% | 5.89 | 5.98 | 5.94 | — |
| USD/MXN | 17.06 | -0.24% | -8.58% | 17.10 | 17.08 | 17.01 | — |
| USD/CLP | 913.98 | +0.04% | -5.67% | 913.65 | 915.11 | 906.68 | — |
| USD/COP | 3,140 | +0.03% | -22.04% | 3,139 | 3,141 | 3,105 | — |
| USD/PEN | 3.36 | -0.66% | -4.82% | 3.38 | 3.38 | 3.35 | — |
| USD/ARS | 1,493 | +0.10% | +12.96% | 1,491 | 1,494 | 1,480 | — |
| USD/UYU | 40.27 | +1.24% | +1.80% | 39.77 | 40.27 | 40.23 | — |
| USD/PYG | 5,939 | +1.68% | -19.54% | 5,841 | 5,939 | 5,925 | — |
| USD/BOB | 11.64 | -0.76% | +72.04% | 11.73 | 11.72 | 11.64 | — |
| USD/DOP | 58.34 | +1.25% | -3.44% | 57.62 | 58.34 | 58.04 | — |
| USD/CRC | 445.92 | +0.89% | -9.71% | 441.97 | 448.50 | 445.92 | — |
03 What moved it
The widening cash premium was the session’s main signal, pointing to scarce immediately available metal. LME stocks fell 1,950 tonnes to 121,600 tonnes, and 11,250 tonnes, or 9.25% of the total, were cancelled warrants, meaning metal earmarked for withdrawal.
The outright price fell with the wider macro mood. The dollar index rose 0.08% to 101.45 and the 10-year Treasury yield climbed to 5.29%, which tends to weigh on metals priced in dollars.
On the demand side, Chinese trading was quiet before the National Day holiday. Galvanised steel, which is steel coated with zinc to prevent rust, is zinc’s main use, so soft Chinese construction weighs directly on demand. Shanghai’s November contract fell 0.36% to 26,435 yuan (about US$3,943) a tonne.
04 Wednesday’s data, one by one
Our 30 September edition told readers to watch five things on Wednesday. Here is how each turned out.
- China’s last session before the holiday: Shanghai closed for the 1–7 October break with the November zinc contract down 0.36% at 26,435 yuan (about US$3,943) a tonne; the LME keeps trading. Overnight, China’s official manufacturing PMI rose to 50.1 in September from 49.8, in line with forecasts, and the private RatingDog PMI to 52.1 (forecast 51.6). Neither lifted zinc.
- US ADP and PCE: Private employers added 90,000 jobs in September, according to ADP, above the 70,000 forecast. The Bureau of Economic Analysis said August PCE inflation was 3.4% year on year (forecast 3.7%) and core PCE 3.0% (forecast 3.3%). Yields still rose, the 10-year to 5.29%, and the dollar firmed slightly, a mild headwind for metals.
- Chile’s August output: INE said industrial production fell 5.7% year on year (forecast −3.0%) and mining output 11.7%. Copper production dropped 12.8% to 369,500 tonnes, the lowest monthly figure since February 2011. It adds to evidence of weak Andean mine supply, the same theme behind Peru’s falling zinc output.
- Colombia’s rate decision: Banco de la República surprised with a 25-basis-point hike to 12.25%, against a forecast hold at 12%; the board split 4–2–1. There is no direct zinc read.
- LME spreads: We asked whether the cash-to-three-month backwardation would keep widening. It did: on official prices it rose to US$112 a tonne from US$106 on Tuesday, while LME stocks fell.
05 The Latin American read
Peru supplies roughly one-tenth of global mine output, so a 12% drop in its concentrate production this year has an outsized effect on regional zinc flows. Mexico and Bolivia are also major producers, but Peru’s decline is the most consequential for the nearby market.
Nexa Resources operates Cerro Lindo, El Porvenir and Atacocha in Peru, as well as Vazante and Aripuanã in Brazil, and runs zinc smelters in both countries. That integrated mining-and-smelting footprint makes it the clearest Latin American equity proxy for the metal, even as its New York shares slipped to US$12.19.
06 The names to watch
Nexa Resources remains the primary name for investors wanting direct zinc exposure because it mines and smelts the metal in Peru and Brazil. Its shares closed at US$12.19 after a 1.53% drop, tracking the softer LME price.
Buenaventura is a less direct proxy because its portfolio also includes precious metals, though it does have zinc exposure through Uchucchacua and Tambomayo. At US$31.58, down 1.28%, it followed the same cautious mood as Nexa.
07 The outlook
The market faces a standoff: physical zinc is tight because Peruvian mine output is shrinking, but Chinese construction demand has not returned strongly enough to lift the outright price, which slipped to US$3,842 a tonne. The cash-to-three-month backwardation, now US$112 a tonne, will be the clearest sign of how long the squeeze lasts.
With Shanghai shut until 8 October, attention turns to post-holiday buying in China. If galvanised-steel users restock after National Day, Shanghai prices should climb and pull Latin American miners higher; if they stay cautious, the physical premium may prove the only source of strength.
08 What to watch
- China’s holiday: Shanghai is shut from 1 to 7 October and reopens on 8 October; the LME keeps trading and sets the price this week.
- Peru today: September inflation at 08.00 UTC (forecast 4.7% year on year, August 4.44%).
- US data today: Weekly jobless claims at 12.30 UTC (forecast 200,000, prior 197,000) and the ISM manufacturing PMI for September at 14.00 UTC (forecast 55.0, prior 54.6).
- Chile and Brazil today: Chile’s August Imacec activity index at 11.30 UTC (8.30 am in Santiago and Brasília; forecast −0.4% year on year, prior −1.5%); Brazil’s S&P Global manufacturing PMI at 13.00 UTC (forecast 46.5, prior 46.3).
- LME spreads and stocks: Whether the backwardation keeps widening from US$112 a tonne while stocks fall from 121,600 tonnes.
- Nexa Resources: Whether the shares recover from US$12.19 if the LME price steadies.
Frequently Asked Questions
Why is zinc supply tight?
Peru’s zinc-concentrate output fell 12% year on year to 746,000 tonnes in January–July 2026, and July production dropped 11.1% to 102,100 tonnes, leaving smelters with less feed.
What does the cash-to-three-month spread tell us?
On official LME prices, cash zinc was US$112 a tonne above three-month zinc on Wednesday, up from US$106 on Tuesday. Buyers are paying a stronger premium for metal they can take immediately, a sign of physical scarcity.
Why did Latin American zinc equities fall?
They moved with the metal. The LME official three-month price fell 0.75%, and Nexa Resources declined 1.53% to US$12.19 while Buenaventura slipped 1.28% to US$31.58.
What is galvanised steel and why does it matter for zinc?
Galvanised steel is steel coated with zinc to prevent rust, and it is zinc’s main use. Soft construction and infrastructure activity in China therefore directly weakens zinc demand.
Source: RT live market data, close of Wednesday 30 September 2026; LME official prices.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Read More from The Rio Times