Mexico Markets: IPC & the Peso — October 1, 2026
Key Facts
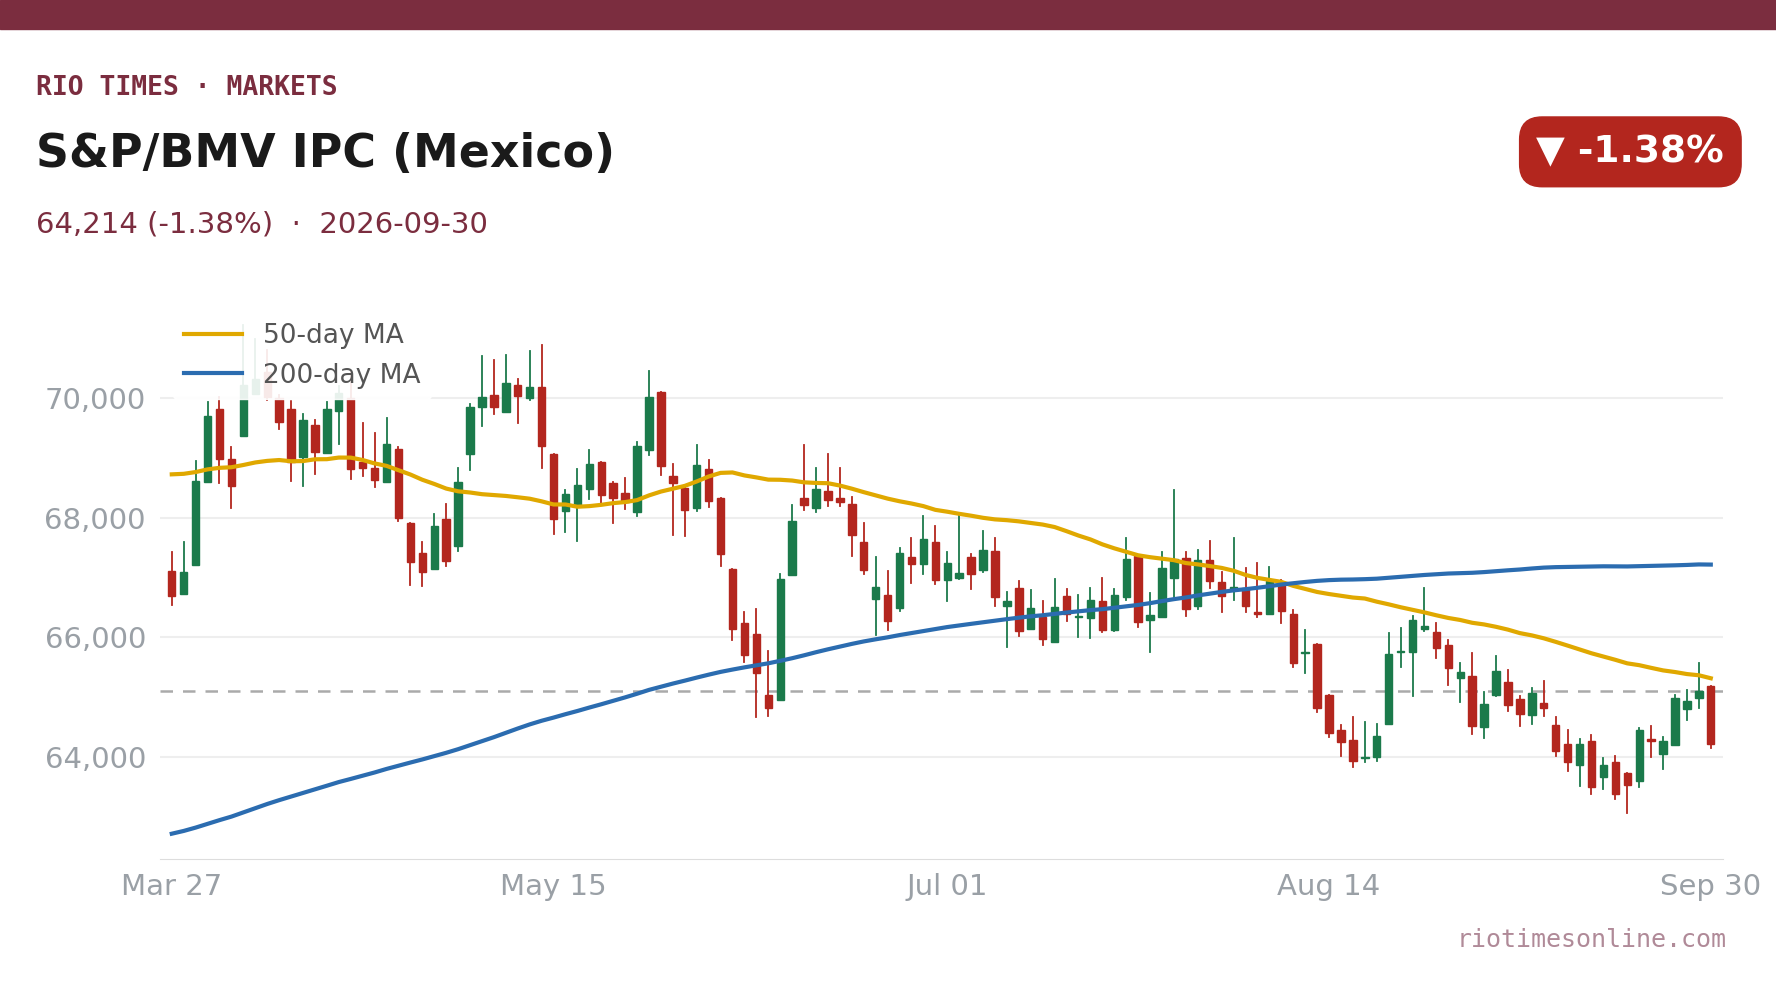
- Mexico’s main stock index, the S&P/BMV IPC, fell 1.38% (896.21 points) to 64,214.36 on Wednesday, 30 September, its lowest close since 21 September
- September ended in the red: the IPC lost 1.86% in the month, its fourth monthly decline in a row, and 4.11% in the third quarter; it is now 0.15% below its end-2025 level
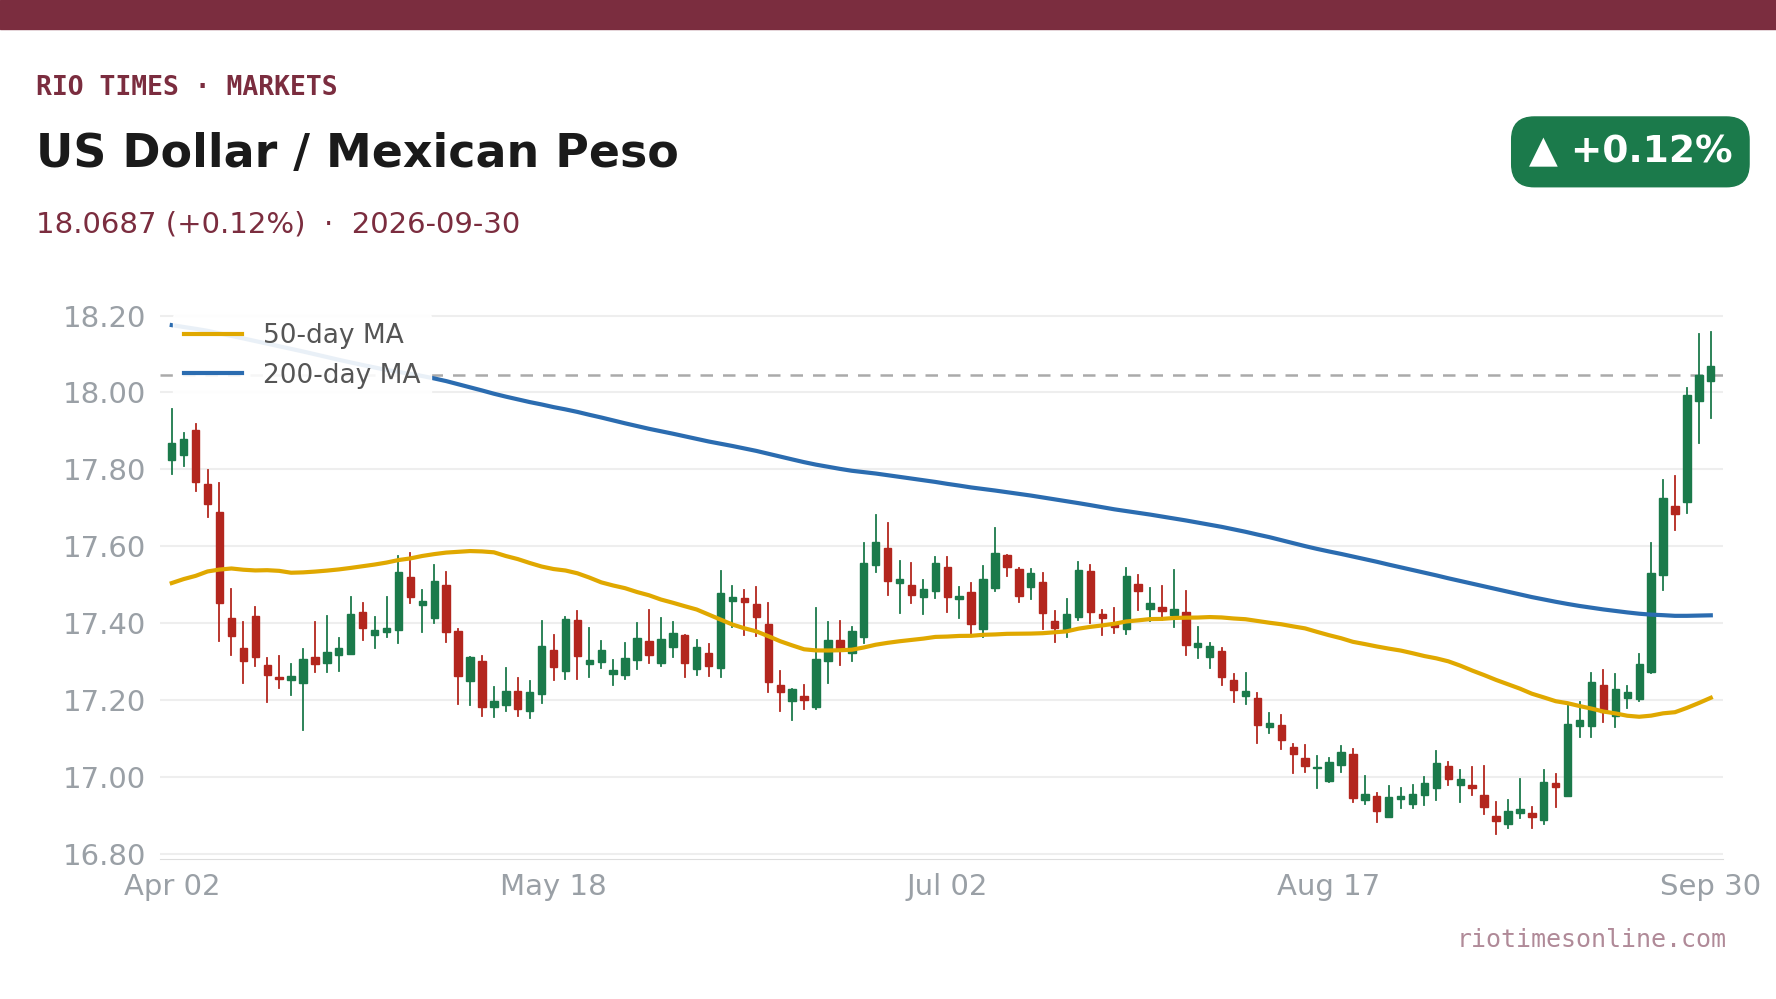
- The peso, Mexico’s currency, weakened 0.12% to 18.0687 per US dollar, its weakest close since 30 March; it lost about 6% against the dollar in September
- Heavyweights led the fall: Banorte lost 2.59%, América Móvil 2.39%, Walmex 1.24% and Femsa 1.24%; Kimberly-Clark de México fell 4.24%
- Main driver: strong US data (second-quarter GDP revised up to 2.2%, a Chicago PMI of 58.8) pushed the US ten-year yield up to 5.29%, squeezing the rate gap after the Fed’s September hike and Banxico’s hold at 6.50%
Today’s Focus
Mexico’s main stock index fell on Wednesday, 30 September, on the last day of the quarter, as US bond yields rose again.
The S&P/BMV IPC closed at 64,214.36, down 1.38% or 896.21 points. It opened at its high near 65,185 and slid through the day.
The peso slipped 0.12% to 18.0687 per US dollar, its weakest close since 30 March.
Strong US data set the tone. Second-quarter US growth was revised up to 2.2% and the Chicago business survey jumped to 58.8. The US ten-year Treasury yield rose to 5.29%.
Higher US yields shrink the extra return that investors earn on peso assets. That gap has already narrowed since the US Federal Reserve raised rates on 16 September and Banxico, Mexico’s central bank, held at 6.50% on 24 September.
What matters today. Mexico’s September manufacturing survey and business confidence, plus the US ISM factory index, test whether the peso can stay near 18 per US dollar.
01 The session in one read
Mexico’s S&P/BMV IPC — the country’s main stock index — fell 1.38% to close at 64,214.36. It was the lowest close since 21 September.
The index opened at its high of about 65,185 and dropped to about 64,146 late in the session. About 305.8 million shares changed hands, worth 30.0 billion pesos (about US$1.66 billion), according to exchange figures reported by EFE.
The peso, Mexico’s currency, also eased. It closed at 18.0687 per US dollar, 0.12% weaker on the day. A higher number means a weaker peso, because it takes more pesos to buy one dollar.
It was the last session of the month and the quarter. The IPC lost 1.86% in September, its fourth monthly fall in a row, and 4.11% in the third quarter.
Big, easy-to-trade names led the decline. Banorte, América Móvil, Walmex and Femsa all fell more than 1%, while Grupo México was flat.
The session fits a market still adjusting to a smaller rate cushion. The Fed raised rates on 16 September, to a 3.75%–4.00% range, and Banxico kept its rate at 6.50% on 24 September.
Wednesday’s strong US data pushed the ten-year Treasury yield up to 5.29%. That makes US bonds more attractive compared with peso assets.
A 1.38% fall led by the largest, most liquid stocks points to broad, quarter-end selling rather than a single Mexican shock. Mexico had no data of its own on Wednesday.
The variable to watch is whether the peso holds near 18 per US dollar. A move towards the 52-week extreme of about 18.68 would keep stocks on the back foot.
02 The day’s numbers
| Measure | Level | Change | Read |
|---|---|---|---|
| S&P/BMV IPC | 64,214.36 | −1.38% | Lowest close since 21 September |
| USD/MXN | 18.0687 | +0.12% | Peso weaker; weakest close since 30 March |
| Session range (IPC) | about 64,146–65,185 | — | Opened at the high, closed near the low |
| Turnover | 305.8m shares | — | 30.0 billion pesos (about US$1.66 billion) |
| IPC in September | −1.86% | −4.11% Q3 | Fourth monthly loss in a row |
| 52-week IPC closing range | 60,216–71,601 | — | About 10.3% below the 11 February peak |
The IPC’s close at 64,214.36 leaves it just above the round 64,000 mark. The index closed below that level for much of mid-September, with a monthly closing low of 63,375.93 on 18 September.
On the currency, the peso has now closed above 18 per US dollar for two sessions. At the start of September it traded near 17. The 52-week extreme for the dollar is about 18.68, set in November 2025.
Live Market IntelligenceMexico — Live Market Board
Rio Times · Live Market Intelligence
Mexico — Live Market Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IPC MEX | 64,951.10 | -0.24% | +12.17% | 65,110.57 | 66,121 | 65,405 | 108,886,187 |
| USD/MXN | 17.06 | -0.24% | -8.58% | 17.10 | 17.08 | 17.01 | — |
| WALMEX | 48.07 | -0.62% | -14.38% | 48.37 | 48.65 | 48.02 | 10,781,446 |
| GMEXICO | 223.28 | +0.35% | +73.59% | 222.50 | 226.18 | 222.17 | 1,325,556 |
| FEMSA | 201.19 | -0.24% | +25.67% | 201.67 | 206.71 | 199.56 | 750,706 |
| CEMEX | 19.32 | +0.89% | +19.10% | 19.15 | 19.35 | 19.04 | 14,327,054 |
| GFNORTE | 193.98 | +1.18% | +14.36% | 191.71 | 195.79 | 191.83 | 1,579,115 |
| BIMBO | 60.98 | -0.96% | +11.89% | 61.57 | 61.46 | 60.29 | 1,048,115 |
| TELEVISA | 9.71 | +0.21% | +12.78% | 9.69 | 9.75 | 9.60 | 577,851 |
| AMX | 19.80 | -0.95% | +12.53% | 19.99 | 20.05 | 19.70 | 58,058,525 |
| GAP | 366.23 | +0.43% | -21.21% | 364.68 | 370.85 | 362.82 | 226,946 |
| ASUR | 275.04 | +1.25% | -15.28% | 271.64 | 275.08 | 271.31 | 15,451 |
| OMA | 233.50 | +0.62% | -6.48% | 232.06 | 235.00 | 230.62 | 555,693 |
| KOF | 188.04 | +0.86% | +18.94% | 186.44 | 188.56 | 185.52 | 425,273 |
| GRUMA | 252.90 | +0.11% | -21.85% | 252.61 | 254.74 | 250.36 | 90,048 |
| KIMBER | 39.74 | +0.43% | +8.85% | 39.57 | 40.09 | 39.33 | 490,551 |
| AMX ADR | 23.38 | -0.23% | +22.25% | 23.43 | 23.49 | 23.06 | 1,347,445 |
03 Why it moved — US yields and a narrower rate gap
The root cause is the shrinking interest-rate cushion between Mexico and the United States. Higher rates in Mexico have long made peso assets, such as government bonds, attractive to foreign investors.
That advantage has narrowed. The Fed raised its key rate by a quarter point on 16 September, to 3.75%–4.00%. Banxico held its own rate at 6.50% on 24 September. The gap is now about 2.5 to 2.75 percentage points.
Wednesday’s US data added pressure. Second-quarter growth was revised up to 2.2% a year, and the Chicago purchasing managers’ index jumped to 58.8. Strong growth gives the Fed room to keep rates high, so the ten-year Treasury yield rose to 5.29%.
A softer US inflation reading did not change that picture. The Fed’s preferred price gauge, core PCE, rose 3.0% on the year in August, below the 3.3% expected.
A weaker peso feeds through to Mexican stocks. Earnings in pesos are worth fewer dollars to foreign investors. It was also the last day of the quarter, when funds often rebalance their portfolios.
04 The day’s movers
| Driver | Level / Move | Change | Note |
|---|---|---|---|
| Banorte (GFNORTEO) | Banking | −2.59% | Largest Mexican-owned bank; 11.5m shares traded |
| América Móvil (AMXB) | Telecoms | −2.39% | Index heavyweight; 44.9m shares traded |
| Walmex (WALMEX) | Retail | −1.24% | Defensive name caught in the selling |
| Femsa (FEMSAUBD) | Bottling and stores | −1.24% | Gave back part of Tuesday’s gain |
| Kimberly-Clark de México (KIMBERA) | Consumer goods | −4.24% | Biggest decliner in the index |
| Peñoles / Televisa | Mining / media | −2.86% / −2.96% | Among the day’s heaviest losses |
| Airports: ASUR / GAP / OMA | Transport | −2.54% / −2.19% / −1.89% | All three airport groups fell |
| Grupo México (GMEXICOB) | Mining | +0.09% | Flat; copper miner held up |
Banorte and América Móvil set the tone. When the heaviest, most liquid stocks fall together, the whole index follows, because the IPC is weighted by company size.
The three airport groups, ASUR, GAP and OMA, all fell. Their revenue is closely tied to traffic and the peso. Outside the index, homebuilder Consorcio ARA jumped 13.33%, the day’s biggest gain on the exchange.
05 The regional scoreboard
| Index | Country | Change |
|---|---|---|
| S&P/BMV IPC | Mexico | −1.38% |
| Ibovespa | Brazil | +1.37% |
| S&P Merval | Argentina | +1.32% |
| S&P IPSA | Chile | −0.78% |
| MSCI COLCAP | Colombia | −0.38% |
Mexico was the weakest of the five big Latin American markets on Wednesday. Brazil’s Ibovespa rose 1.37% and Argentina’s Merval 1.32%, while Chile’s IPSA fell 0.78% and Colombia’s COLCAP 0.38%.
The split suggests the selling in Mexico was tied to the peso and the rate gap with the United States, rather than to a region-wide retreat.
06 The technical picture
The IPC is about 10.3% below its 52-week closing high of 71,601, set on 11 February. It has fallen in each of the past four months.
The first level below is 64,000. Under that sits the September closing low of 63,375.93 from 18 September.
For the peso, 18 per US dollar is the line to watch. A return below it would ease the pressure. A move towards 18.68, the dollar’s 52-week closing high from November 2025, would mark a new low for the peso over the past year.
Until the US–Mexico rate gap stabilises, rallies in Mexican assets are likely to meet selling.
07 Wednesday’s data, one by one
Our previous edition told readers to watch China’s factory surveys, a batch of US data, Colombia’s rate decision and whether the peso would hold above 18 per US dollar. Mexico had no releases of its own on Wednesday.
- China PMIs (September): the official manufacturing index rose to 50.1 from 49.8, as expected, and the services index to 50.2, above the 49.3 forecast. Readings above 50 signal growth. Little direct effect on Mexico; Grupo México, the copper miner, was flat.
- US ADP private payrolls (September): 90,000 jobs, above the roughly 70,000 expected. It was a sign the US labour market is holding up, which supports higher US rates.
- US PCE prices (August): the headline index rose 3.4% on the year, below the 3.7% expected; the core index rose 3.0%, against 3.3% forecast. Personal spending rose 0.9% on the month and income 0.2%. The softer inflation reading did not stop the peso from ending the day weaker.
- US second-quarter GDP (third estimate): growth was revised up to an annual rate of 2.2%, from 1.5% in the previous estimate. This, and the Chicago survey below, pushed the ten-year Treasury yield up to 5.29%.
- Chicago PMI (September): 58.8, far above the 51.2 expected and up from 47.1 in August. It was the biggest upside surprise of the day.
- Colombia rate decision: Banco de la República surprised with a quarter-point hike to 12.25%; a hold at 12% had been expected. It had no visible effect on Mexican assets.
- Peso above 18: the level held. The peso closed at 18.0687 per US dollar, a second close above 18 and its weakest since 30 March.
08 What to watch
- Mexico business confidence (September, 12:00 UTC): INEGI’s survey, last at 48.1; below 50 means more firms are pessimistic than optimistic.
- Mexico manufacturing PMI (September, 15:00 UTC): S&P Global’s factory survey, forecast at about 50 after 49.8 in August.
- Mexico public finances (August, 19:00 UTC): the Finance Ministry’s monthly report on revenue, spending and the budget balance.
- US ISM manufacturing (September, 14:00 UTC): forecast at 55 after 54.6; a strong reading would keep US yields high. US weekly jobless claims are due at 12:30 UTC.
- Fed speakers: Fed official Christopher Waller (14:00 UTC) and New York Fed president John Williams (19:30 UTC) are among several officials due to speak.
- Peso near 18: whether Mexico’s currency can move back below 18 per US dollar.
Background: Mexico’s IPC Falls 0.78% as the Peso Slips Before Banxico.
Frequently Asked Questions
What happened to Mexico’s stock market on Wednesday?
The S&P/BMV IPC fell 1.38% to close at 64,214.36 on 30 September, its lowest close since 21 September. It lost 1.86% in September, its fourth monthly decline in a row.
Why is the peso weakening?
The interest-rate advantage of holding Mexican assets has narrowed. The US Federal Reserve raised rates on 16 September while Banxico held at 6.50%, and strong US data on Wednesday pushed US yields higher. The peso closed at 18.0687 per US dollar.
Which stocks led the decline?
Banorte fell 2.59%, América Móvil 2.39%, and Walmex and Femsa 1.24% each. Kimberly-Clark de México lost 4.24%, while Grupo México ended flat.
What levels should investors watch?
For the IPC, 64,000 and the September closing low of 63,375.93. For the peso, 18 per US dollar; the dollar’s 52-week closing high of about 18.68 is the next marker.
Source: RT live market data, close of Wednesday 30 September 2026; exchange figures from BMV.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
In depth
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Read More from The Rio Times