Lithium Stocks Give Back Bounce as SQM Drops 1.8% Before China Holiday
Key Facts
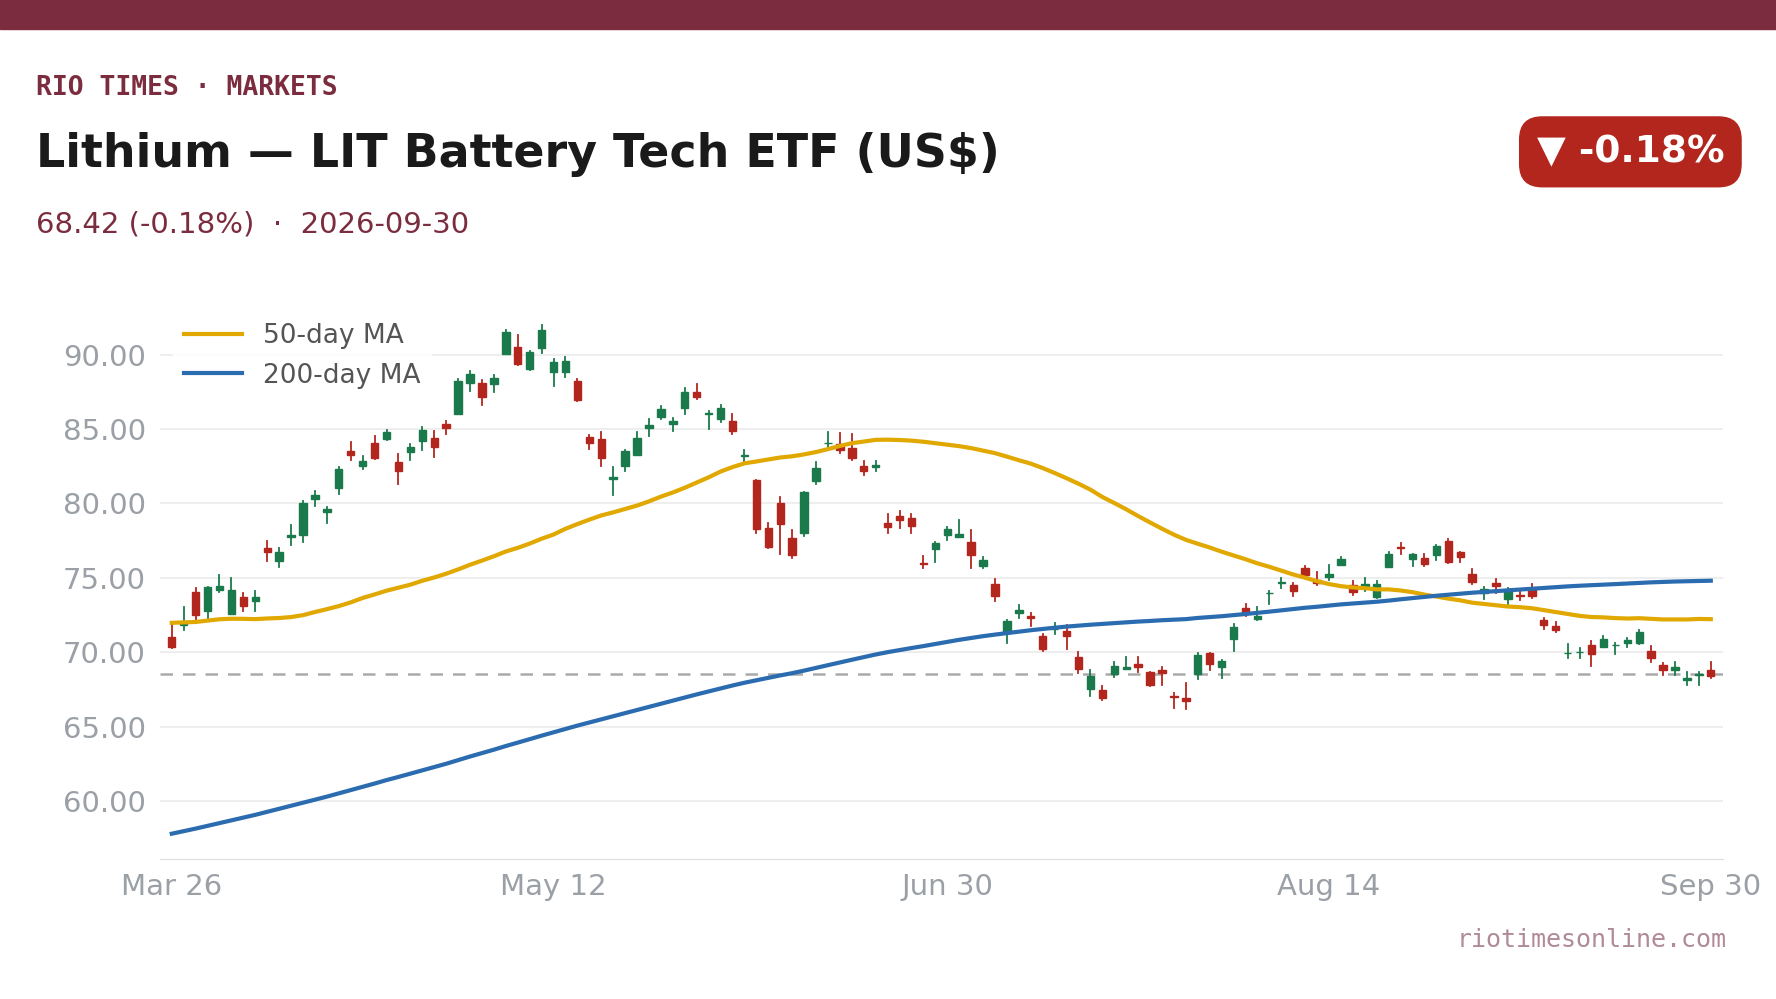
- Lithium producers gave back Tuesday’s bounce. The lithium-tracking LIT ETF held up better, closing at US$68.42, down 0.18%, on Wednesday, 30 September 2026.
- Chile’s SQM was the weaker of the two big producers, falling 1.83% to US$64.87 in New York. Its Santiago shares lost 2.47% to 62,900 pesos (about US$64.68).
- Albemarle shares fell 1.71% to US$105.78.
- China’s most-traded lithium-carbonate contract fell 0.94% to 118,420 yuan (about US$17,660) a tonne on Wednesday, its third straight decline after drops of 5.69% on Monday and 1.69% on Tuesday. Guangzhou is now shut for the 1–7 October National Day holiday.
- US data did not ease rates. August PCE inflation came in at 3.4% year on year, below the 3.7% forecast, and ADP counted 90,000 new private jobs. The 10-year Treasury yield still rose to 5.29%.
- Chile’s mining slump deepened. Industrial output fell 5.7% year on year in August, and copper production dropped 12.8% to 369,500 tonnes, the lowest monthly figure since February 2011.
Today’s Focus
Lithium shares gave back Tuesday’s bounce on Wednesday, 30 September 2026. Chile’s SQM fell 1.83% to US$64.87 and Albemarle lost 1.71% to US$105.78. The LIT fund, which holds miners, refiners and battery-tech companies rather than physical lithium, slipped only 0.18% to US$68.42.
The pressure came from China. In the last Guangzhou session before the National Day holiday, the most-traded lithium-carbonate contract fell 0.94% to 118,420 yuan (about US$17,660) a tonne. It was the third straight fall, after drops of 5.69% on Monday and 1.69% on Tuesday. Traders read the slide as supply catching up with battery demand.
Rates did not help either. US inflation for August came in softer than forecast, yet the 10-year Treasury yield rose to 5.29%. In Chile, August industrial output fell 5.7% year on year as copper production sank to its lowest level since 2011.
What matters today. Chinese lithium futures will not trade again until 8 October. Until then, producer shares have no fresh price signal from the main market, and Tuesday’s bounce has already faded.
01 The session in one read
Lithium equities drifted lower on Wednesday, 30 September 2026, and the producers gave back Tuesday’s gains. The lithium-tracking LIT ETF closed at US$68.42, down 0.18% on the day.
Albemarle, a bellwether for lithium chemicals, fell 1.71% to US$105.78. Chile’s SQM lost 1.83% to US$64.87, the steeper decline of the two producers. In Santiago, SQM’s B shares fell 2.47% to 62,900 pesos (about US$64.68) and closed at the day’s low.
Among smaller names, Sigma Lithium fell 3.19% to US$9.40, while Lithium Americas was unchanged at US$2.63.
The lithium complex is not one market, but China’s contract remains the dominant reference for short-term direction. With the Guangzhou contract down for three sessions in a row, including a 5.69% drop on Monday, producers in Chile and Argentina face renewed pressure on realised prices even as long-term EV demand looks intact. The variable to watch is whether China’s downstream battery-cell buying returns after the National Day holiday, or whether supply discipline forces further cuts in carbonate output.
02 The board
The board tells a story of selective weakness in producer shares. The LIT fund, which spreads risk across miners, refiners and battery-technology names, held up better than the pure-play producers.
Albemarle’s US-listed shares at US$105.78 and SQM at US$64.87 both underperformed the ETF, a sign that investors were penalising companies with direct exposure to lithium prices. LIT’s US$68.42 close reflected the cushion of diversified holdings, led by Rio Tinto at roughly 23% of the fund.
All three remain far below their May peaks. LIT’s 52-week high is US$91.98, Albemarle’s US$221.00 and SQM’s US$98.00.
| Asset | Level | Change |
|---|---|---|
| Lithium (LIT ETF) | US$68.42 | -0.18% |
| Albemarle | US$105.78 | -1.71% |
| SQM | US$64.87 | -1.83% |
| SQM-B (Santiago) | 62,900 pesos (US$64.68) | -2.47% |
| Lithium carbonate, Guangzhou (per tonne) | 118,420 yuan (US$17,660) | -0.94% |
Source: RT live market data, close of Wednesday 30 September 2026; lithium carbonate: Guangzhou Futures Exchange, most-traded contract. Where a commodity has no spot feed, an exchange-traded tracker or leading producer is shown as a labelled proxy.
Live Market IntelligenceThe live market board
Rio Times · Live Market Intelligence
Latin America — Cross-Market Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IBOV | 186,340.46 | +1.37% | +21.85% | 183,827.59 | 168,310 | 167,142 | — |
| IPSA | 10,969.49 | -0.78% | — | 11,055.94 | 11,210 | 10,984 | 1,513,213,483 |
| IPC MEX | 64,951.10 | -0.24% | +12.17% | 65,110.57 | 66,121 | 65,405 | 108,886,187 |
| MERVAL | 2,819,323 | +1.32% | +30.51% | 3,022,485 | 3,042,365 | 2,991,150 | — |
| COLCAP | 2,549.16 | -0.38% | — | 9.04 | 9.05 | 9.02 | 4,133 |
| BVL PERÚ | 60,410.88 | -0.96% | — | — | — | — | — |
| USD/BRL | 5.16 | +0.01% | -5.13% | 5.16 | 5.18 | 5.14 | — |
| EUR/BRL | 5.95 | +1.01% | -5.83% | 5.89 | 5.98 | 5.94 | — |
| USD/MXN | 17.06 | -0.24% | -8.58% | 17.10 | 17.08 | 17.01 | — |
| USD/CLP | 913.98 | +0.04% | -5.67% | 913.65 | 915.11 | 906.68 | — |
| USD/COP | 3,140 | +0.03% | -22.04% | 3,139 | 3,141 | 3,105 | — |
| USD/PEN | 3.36 | -0.66% | -4.82% | 3.38 | 3.38 | 3.35 | — |
| USD/ARS | 1,493 | +0.10% | +12.96% | 1,491 | 1,494 | 1,480 | — |
| USD/UYU | 40.27 | +1.24% | +1.80% | 39.77 | 40.27 | 40.23 | — |
| USD/PYG | 5,939 | +1.68% | -19.54% | 5,841 | 5,939 | 5,925 | — |
| USD/BOB | 11.64 | -0.76% | +72.04% | 11.73 | 11.72 | 11.64 | — |
| USD/DOP | 58.34 | +1.25% | -3.44% | 57.62 | 58.34 | 58.04 | — |
| USD/CRC | 445.92 | +0.89% | -9.71% | 441.97 | 448.50 | 445.92 | — |
Live Company IntelligenceSociedad Quimica y Minera de Chile SA ADR B — the full investor dossier
Wall Street view
Valuation & profitability
Price & risk
$39.7952-wk high
$96.09
Revenue trend · 6y
Ownership
Dividend
03 What moved it
The main driver came from China, the world’s largest lithium consumer. In its last session before the holiday, the most-traded lithium-carbonate contract in Guangzhou fell 0.94% to 118,420 yuan (about US$17,660) a tonne, after drops of 1.69% on Tuesday and 5.69% on Monday.
That three-day slide suggested supply is catching up with battery demand, reversing some of the tightness that had supported prices. For Western producers, the direction was enough to drag shares lower even with no equivalent spot move in the Americas.
Investors also weighed Albemarle’s second-quarter realised price of US$19.53 per kilogram, a sharp rise from US$12.17 a year earlier. The challenge is that spot weakness in China can erode that pricing power in future quarters.
The rate backdrop stayed tight. Softer US inflation data failed to pull yields lower: the 10-year Treasury yield rose about four basis points to 5.29%, and the dollar index edged up 0.08% to 101.45. High borrowing costs weigh on capital-hungry mining and battery stocks.
04 Wednesday’s data, one by one
Our 30 September edition flagged five items for Wednesday. Here is how each turned out.
- China’s last session before the holiday: Wednesday was the final Guangzhou trading day before the 1–7 October National Day break. Lithium carbonate fell 0.94% to 118,420 yuan (about US$17,660) a tonne, its lowest close of the week. Overnight, China’s official manufacturing PMI rose to 50.1 in September from 49.8, in line with forecasts, and the private RatingDog gauge rose to 52.1 from 51.5. Neither stopped the slide.
- US ADP payrolls: Private employers added 90,000 jobs in September, according to ADP, above the 70,000 forecast and up from 36,000 in August. A firmer labour market supports the case for keeping rates high.
- US PCE inflation: The Bureau of Economic Analysis said August PCE prices rose 3.4% year on year (forecast 3.7%, July 3.4%) and 0.3% on the month. Core PCE was 3.0% (forecast 3.3%). Personal spending jumped 0.9%. The softer price data did not ease rates: the 10-year yield rose to 5.29%, and the S&P 500 fell 0.25% to 7,651.54.
- Chile’s August data: The statistics office INE reported industrial production down 5.7% year on year (forecast −3.0%, July −5.1%). Mining output fell 11.7%, and copper production dropped 12.8% to 369,500 tonnes, the lowest monthly figure since February 2011. Unemployment rose to 9.6% in June–August (forecast 9.5%), and trade activity was flat year on year. The IPSA fell 0.78% to 10,969.49, and the peso was little changed at 972.53 per US dollar.
- Colombia’s rate decision: Banco de la República surprised with a 25-basis-point hike to 12.25%, against a forecast hold at 12%. The board split 4–2–1. There is no direct lithium read, but the move adds to a tight-money backdrop across the region.
- SQM and Albemarle: We asked whether Tuesday’s bounce would hold if Chinese prices kept falling. It did not. Chinese prices fell again, and both stocks lost more on Wednesday than they had gained on Tuesday.
05 The Latin American read
For the Lithium Triangle, the session confirmed that China’s carbonate price remains the short-term reference. Chile’s producing assets in the Salar de Atacama are world-class, but SQM’s share-price decline shows that even established operators are not insulated. Chile’s wider mining sector is also weak: August mining output fell 11.7% year on year, mainly on lower copper production.
Argentina is moving from project development into production ramp-up, making it the more dynamic growth story. Bolivia, despite a large resource base, remains at an early commercial stage, with state producer YLB focused on restarting and expanding output while legal and institutional issues continue to affect major projects.
06 The names to watch
Albemarle and SQM are the two most direct lithium producers with US-listed shares. SQM retains control of Atacama operations through 2030 in its NovaAndino Litio partnership with Codelco, with the state-owned miner scheduled to take majority control from 2031.
Rio Tinto, LIT’s largest holding, is an indirect play through its lithium business, which includes projects in Argentina that are still ramping up.
Argentina’s project pipeline offers a more speculative angle. Names tied to production ramp-up there may move more aggressively on sentiment, though they lack the liquidity and balance-sheet strength of Albemarle or SQM.
07 The outlook
The immediate outlook depends on whether China’s lithium-carbonate contract stabilises when trading resumes on 8 October. The market is watching whether supply discipline returns or battery-cell buyers stay on the sidelines.
For Latin America, the medium-term story remains intact: EV demand is still lithium’s largest source of growth, and grid-scale energy storage is expanding. But the next few sessions will be about price, not potential.
08 What to watch
- China’s holiday: Guangzhou lithium-carbonate futures are shut from 1 to 7 October and reopen on 8 October, so producer shares trade without a Chinese price signal all week.
- US data today: Weekly jobless claims at 12.30 UTC (forecast 200,000, prior 197,000) and the ISM manufacturing PMI for September at 14.00 UTC (forecast 55.0, prior 54.6), with its prices index forecast at 72.3.
- Chile and Brazil today: Chile’s August Imacec activity index at 11.30 UTC (8.30 am in Santiago and Brasília; forecast −0.4% year on year, prior −1.5%), after Wednesday’s weak mining data. Brazil’s S&P Global manufacturing PMI at 13.00 UTC (forecast 46.5, prior 46.3).
- Fed speakers: Christopher Waller at 14.00 UTC and John Williams at 19.30 UTC, with the 10-year Treasury yield near 5.3%.
- SQM and Albemarle: Whether the shares find support after giving back Tuesday’s gains, and any update on whether Albemarle’s US$19.53-per-kilogram realised price is holding in the third quarter.
Frequently Asked Questions
Is LIT a pure lithium ETF?
No, LIT owns a basket of lithium miners, refiners and battery-technology companies, so it tracks equities rather than the spot price of physical lithium.
Why did Albemarle and SQM fall harder than LIT?
Both are direct producers with greater sensitivity to lithium prices, while LIT’s diversified holdings cushioned the move.
What is the most important lithium price to watch?
China’s Guangzhou lithium-carbonate contract is the main short-term reference for global trade. It is closed for China’s National Day holiday from 1 to 7 October.
Is Bolivia a major lithium producer?
Not yet. Bolivia has a large resource base but remains at an early commercial stage, with legal and institutional hurdles affecting major projects.
Source: RT live market data, close of Wednesday 30 September 2026.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Read More from The Rio Times