Key Facts
- LIT ETF closed higher The Global X Lithium & Battery Tech ETF settled at US$70.83, a gain of 0.47% on the day.
- Albemarle shares rebounded Albemarle Corporation ended Monday at US$112.92, up +1.81% as traders returned to major lithium producers.
- SQM led the producer board Chile’s SQM climbed +2.67% to US$69.53, the strongest percentage move among the three lithium proxies.
- Battery-grade carbonate firmed Chinese battery-grade lithium carbonate rose modestly, with one regional assessment up US$34.22 to US$20,009.83 per tonne.
- Hydroxide tracked cathode demand Battery-grade lithium hydroxide in China gained about 1.66%, reflecting restocking for high-nickel EV cathodes.
- Equities, not spot, drove the tape The live board tracks lithium through miners’ shares and an ETF, not the raw commodity’s own spot price.
Today’s Focus
Lithium equities started the week with a quiet rebound as modest gains in Chinese battery chemicals encouraged buyers of miners’ shares. The Global X Lithium & Battery Tech ETF, a fund holding lithium producers and battery makers, settled at US$70.83, up 0.47%.
Albemarle, one of the world’s largest lithium producers with brine operations in Chile, climbed +1.81% to US$112.92. SQM, the Chilean miner whose Atacama brine operations anchor the Lithium Triangle, rose +2.67% to US$69.53.
The trigger was a small but synchronised firming in Chinese refined lithium prices. Battery-grade lithium carbonate was assessed at US$20,009.83 per tonne, up US$34.22, while battery-grade lithium hydroxide gained about 1.66% as cathode manufacturers restocked.
The moves remain modest by historical standards, but they reversed a month-long drift lower and linked the Andean brine producers to Asian EV battery demand.
What matters today. The lithium recovery is equity-led and demand-dependent: a modest Chinese restocking of battery-grade chemicals lifted miner shares, not a structural supply shock.
01 The session in one read
Lithium equities opened the week with a synchronised but gentle climb on Monday, September 21, 2026. The Global X Lithium & Battery Tech ETF, which holds shares of miners and battery makers rather than physical lithium, settled at US$70.83, up 0.47%.
The smaller gains in Chinese spot benchmarks translated into larger moves in listed producers. Albemarle closed at US$112.92, a +1.81% rise, while Chile’s SQM jumped +2.67% to US$69.53 — the standout performer among the three proxies.
The catalyst was not a headline but a quiet firming of battery-grade material used in electric-vehicle cathodes. Battery-grade lithium carbonate in China was assessed at US$20,009.83 per tonne, up US$34.22 on the day.
The moves mark a pause in a month-long price slide. They sit well within normal trading ranges, but they hint at renewed cathode restocking ahead of the year-end manufacturing push.
Monday’s gains were a ripple, not a wave. Chinese battery-grade carbonate rose just 0.07% in one benchmark and 0.08% in another, while hydroxide climbed about 1.66% on cathode restocking. That was enough to lift equities, but the absence of a large price impulse or supply disruption suggests the rally is built on short-term inventory timing rather than a fundamental shortage.
The variable to watch is whether Chinese battery-grade carbonate and hydroxide gains extend into the rest of the week, or fade as restocking orders are filled.
02 The board
The board tells a story of broad exposure to the lithium value chain. LIT, the New York-listed ETF, rose 0.47% to US$70.83; the fund spans miners, refiners and battery manufacturers, so it moves with the equity risk appetite as much as with the underlying metal.
Albemarle, the North Carolina chemicals group whose Atacama brine operations supply lithium to Asia, advanced +1.81% to US$112.92. SQM, Chile’s state-tied miner and specialty fertiliser producer, outpaced both with a +2.67% gain to US$69.53, reflecting its higher beta to lithium pricing.
No physical commodity price appears on the board. Every figure attaches to a proxy asset: an ETF or the shares of a named producer tracking the lithium market, not spot lithium itself.
| Asset | Level | Change |
|---|---|---|
| Lithium (LIT ETF) | US$70.83 | +0.47% |
| Albemarle | US$112.92 | +1.81% |
| SQM | US$69.53 | +2.67% |
Source: RT close, 2026-09-21. Where a commodity has no spot feed, an exchange-traded tracker or leading producer is shown as a labelled proxy.
Live Market IntelligenceThe live market board
Rio Times · Live Market Intelligence
Latin America — Cross-Market Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IBOV | 186,595.60 | +0.74% | +21.85% | 185,229.17 | 168,310 | 167,142 | — |
| IPSA | 11,357.82 | -0.21% | — | 11,381.18 | 11,210 | 10,984 | 1,513,213,483 |
| IPC MEX | 63,536.96 | +0.25% | +12.17% | 63,375.93 | 66,121 | 65,405 | 108,886,187 |
| MERVAL | 2,998,956 | -0.76% | +30.51% | 3,022,485 | 3,042,365 | 2,991,150 | — |
| COLCAP | 2,565.55 | +0.68% | — | 9.04 | 9.05 | 9.02 | 4,133 |
| BVL PERÚ | 59,344.04 | +0.31% | — | — | — | — | — |
| USD/BRL | 5.16 | +0.01% | -5.13% | 5.16 | 5.18 | 5.14 | — |
| EUR/BRL | 5.95 | +1.01% | -5.83% | 5.89 | 5.98 | 5.94 | — |
| USD/MXN | 17.06 | -0.24% | -8.58% | 17.10 | 17.08 | 17.01 | — |
| USD/CLP | 913.98 | +0.04% | -5.67% | 913.65 | 915.11 | 906.68 | — |
| USD/COP | 3,140 | +0.03% | -22.04% | 3,139 | 3,141 | 3,105 | — |
| USD/PEN | 3.36 | -0.66% | -4.82% | 3.38 | 3.38 | 3.35 | — |
| USD/ARS | 1,493 | +0.10% | +12.96% | 1,491 | 1,494 | 1,480 | — |
| USD/UYU | 40.27 | +1.24% | +1.80% | 39.77 | 40.27 | 40.23 | — |
| USD/PYG | 5,939 | +1.68% | -19.54% | 5,841 | 5,939 | 5,925 | — |
| USD/BOB | 11.64 | -0.76% | +72.04% | 11.73 | 11.72 | 11.64 | — |
| USD/DOP | 58.34 | +1.25% | -3.44% | 57.62 | 58.34 | 58.04 | — |
| USD/CRC | 445.92 | +0.89% | -9.71% | 441.97 | 448.50 | 445.92 | — |
Live Company IntelligenceSociedad Quimica y Minera de Chile SA ADR B — the full investor dossier
Wall Street view
Valuation & profitability
Price & risk
$39.7952-wk high
$96.09
Revenue trend · 6y
Ownership
Dividend
03 What moved it
The proximate driver was Chinese restocking of battery chemicals. Battery-grade lithium carbonate in China rose US$34.22 to US$20,009.83 per tonne, while industrial-grade carbonate added US$26.26 to US$19,473.85 per tonne, according to regional assessments.
Battery-grade lithium hydroxide, used in long-range, high-nickel EV cathodes, gained about 1.66% on September 21. That matters because hydroxide demand tightens when automakers favour longer-range battery chemistries.
The gains were modest — the headline Chinese carbonate benchmark rose just 0.07% to 134,400 CNY per tonne — but they were synchronised across grades and indices. Several GFEX futures contracts settled in a contango, with near maturities below later ones, signalling that buyers expect slightly firmer prices ahead.
Stable upstream spodumene prices removed a key source of downside pressure, allowing the refined chemicals to tick higher without a feed cost squeeze. Cathode manufacturers restocking before year-end provided the demand-side nudge.
04 The Latin American read
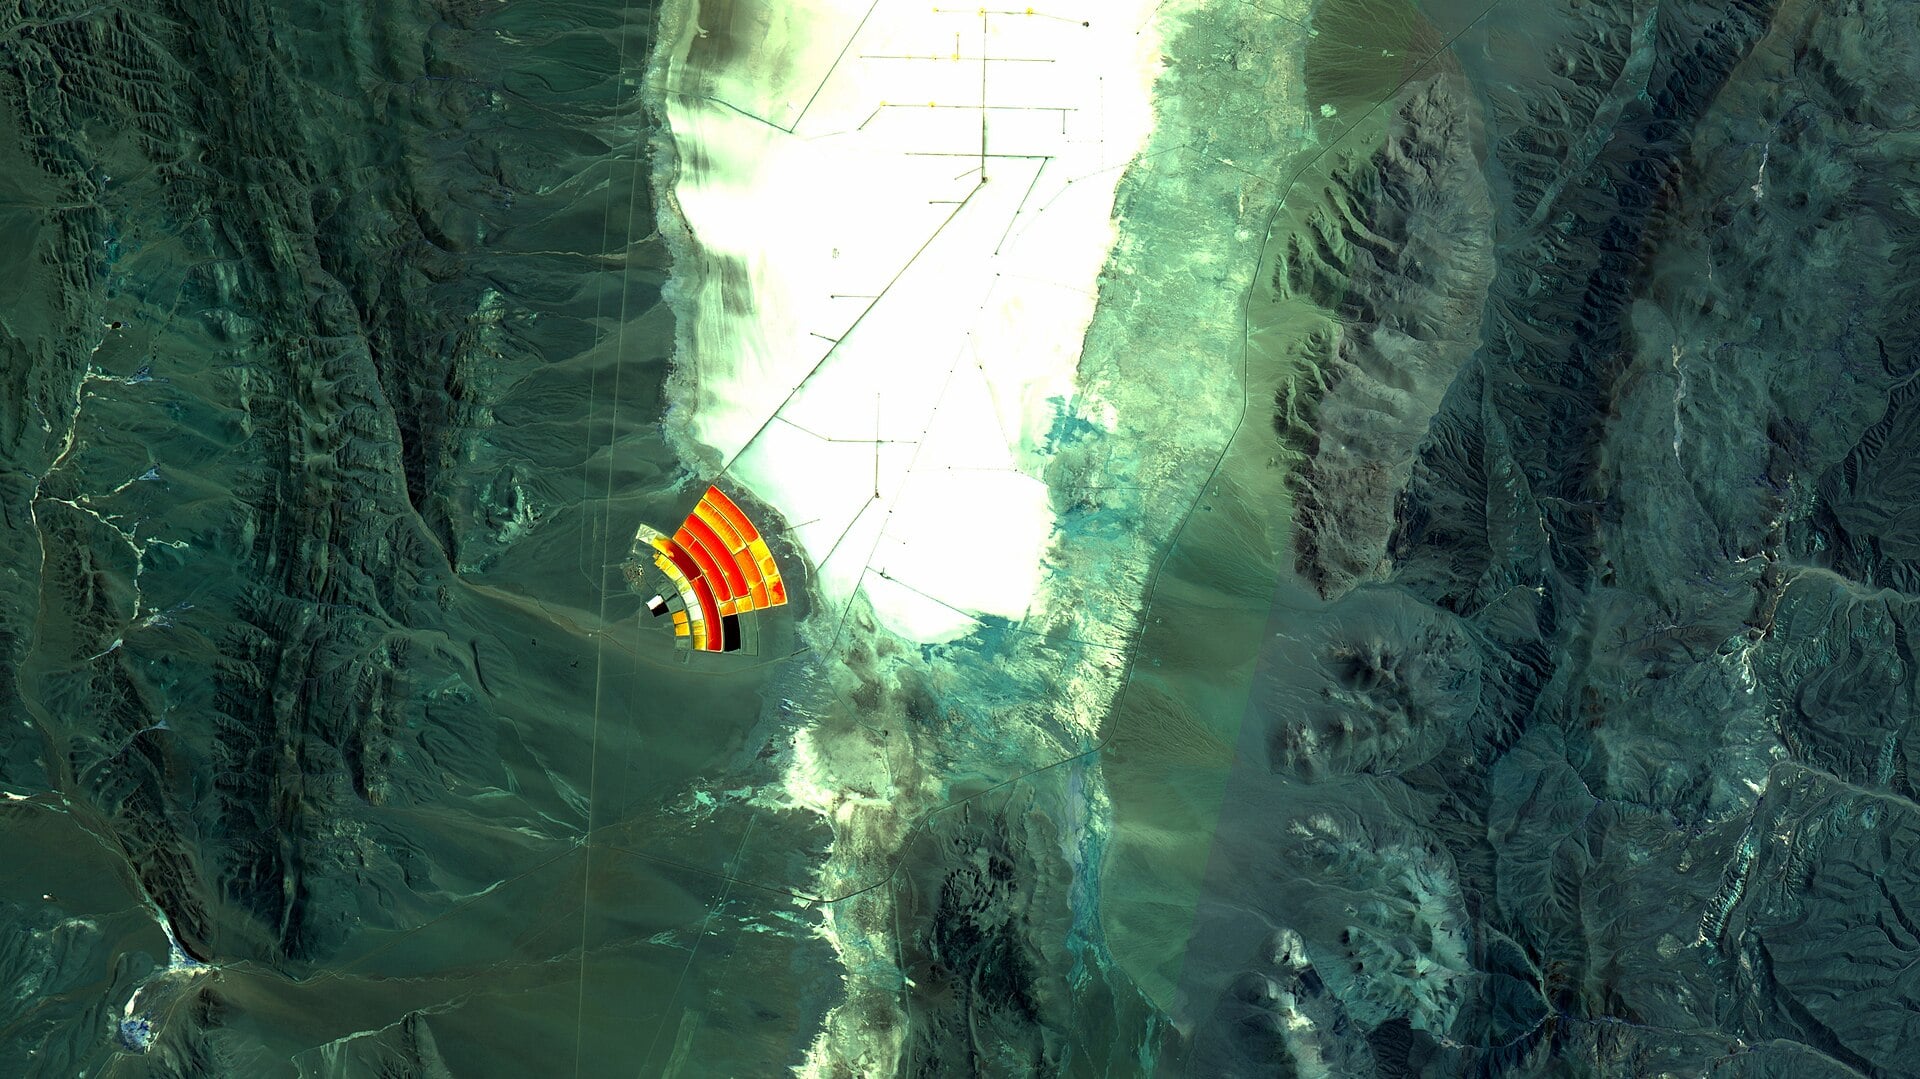
For the Lithium Triangle, Monday’s moves are a reminder that seaborne brine supply sets a reference for global battery markets. South American FOB assessments for 99.5% lithium carbonate from Chile, Argentina and Bolivia feed directly into Asian converters, linking Atacama brine economics to Chinese cathode pricing.
Albemarle and SQM are the purest listed expressions of that link. Albemarle’s brine operations in Chile and hard-rock interests elsewhere make it a barometer for diversified lithium supply; SQM’s Atacama leases make it the primary Chilean vehicle for Lithium Triangle exposure.
The rise in Chinese battery-grade hydroxide also favours Andean brine producers, whose carbonate can be converted to hydroxide for high-nickel cathode applications. A firmer hydroxide market supports prices for South American carbonate delivered to Asian refiners.
Neither producer’s shares moved on news specific to Chile or Argentina. Monday’s equity gains were imported from Asia, illustrating how Lithium Triangle assets are priced by Chinese battery demand rather than local politics alone.
05 The names to watch
Albemarle remains the bellwether for large-cap lithium exposure. Its shares closed at US$112.92 on Monday, and the company’s next quarterly results are projected around November 4, 2026, with consensus earnings per share of US$2.55.
SQM offers a higher-beta Chile-focused alternative. Its +2.67% gain to US$69.53 outpaced Albemarle and the LIT ETF, reflecting its concentration in Atacama brine and sensitivity to lithium prices.
The LIT ETF, up 0.47% to US$70.83, is the diversified play. It spreads exposure across miners, refiners and battery makers, reducing single-company risk while tracking the broader value chain.
For readers watching the underlying commodity, the Chinese battery-grade carbonate assessment of US$20,009.83 per tonne and the hydroxide index’s 1.66% daily gain are the numbers guiding near-term equity sentiment.
06 The outlook
The modest scale of Monday’s gains argues for caution. A 0.07% rise in headline Chinese carbonate and a 1.66% hydroxide uptick are restocking ripples, not the start of a sustained bull trend.
The key test is persistence. If cathode manufacturers continue buying into October, lithium equities could extend their rebound; if restocking pauses, the month-long drift lower may resume.
For Lithium Triangle producers, the longer-term question is how much South American brine supply reaches Asian converters as EV battery plants expand. Monday’s prices suggest the market is watching that flow closely.
07 What to watch
- Chinese battery-grade carbonate: Whether the assessed US$20,009.83 per tonne level holds or extends; this is the daily anchor for miner equity sentiment.
- Hydroxide restocking momentum: The 1.66% gain in Chinese battery-grade hydroxide shows EV cathode demand; a reversal would signal softer long-range battery orders.
- Albemarle’s November earnings: Projected around November 4, 2026, with consensus EPS of US$2.55; any guidance on brine volumes will move Lithium Triangle names.
- GFEX futures contango: Near contracts below later maturities suggest buyers expect firmer prices; steepening would confirm restocking, flattening would not.
Frequently Asked Questions
Is LIT the same as the lithium spot price?
No. LIT is an exchange-traded fund holding shares of lithium miners and battery makers. Monday’s close of US$70.83 is an equity value, not a tonne price for lithium.
Why did SQM outperform Albemarle?
SQM rose +2.67% to US$69.53, ahead of Albemarle’s +1.81% gain. SQM’s Atacama brine concentration gives it higher sensitivity to lithium price expectations.
What moved lithium prices on Monday?
Chinese cathode manufacturers restocked battery-grade material. Battery-grade carbonate rose to US$20,009.83 per tonne, and hydroxide gained about 1.66%.
Does the Lithium Triangle set the global price?
South American FOB brine supply from Chile, Argentina and Bolivia is a reference for seaborne lithium, but daily price moves are anchored by Chinese cathode and carbonate benchmarks.
Market data: RT
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Read More from The Rio Times