Key Facts
- —What happened FEMSA has shelved its plan to turn OXXO into a full bank, betting on its Spin payments app instead.
- —How big a jump Spin’s monthly transactions rose 61.5% year over year to 119.1 million in Q2 2026, with 11.5 million active users.
- —The real story Spin sidesteps heavy banking rules by staying a payments app, testing credit through a small pilot programme.
- —The catch The banking license is paused, not abandoned; the CEO says funding needs could bring it back later.
- —Who it touches Mexico’s 24,708 OXXO stores and millions of cash-based customers, plus investors watching FEMSA’s digital pivot.
- —What comes next If the credit pilot works, FEMSA may expand lending without a bank charter and could revisit the license later.
The Mexican retail giant is betting on its payments app instead of a bank license, and the numbers explain why.
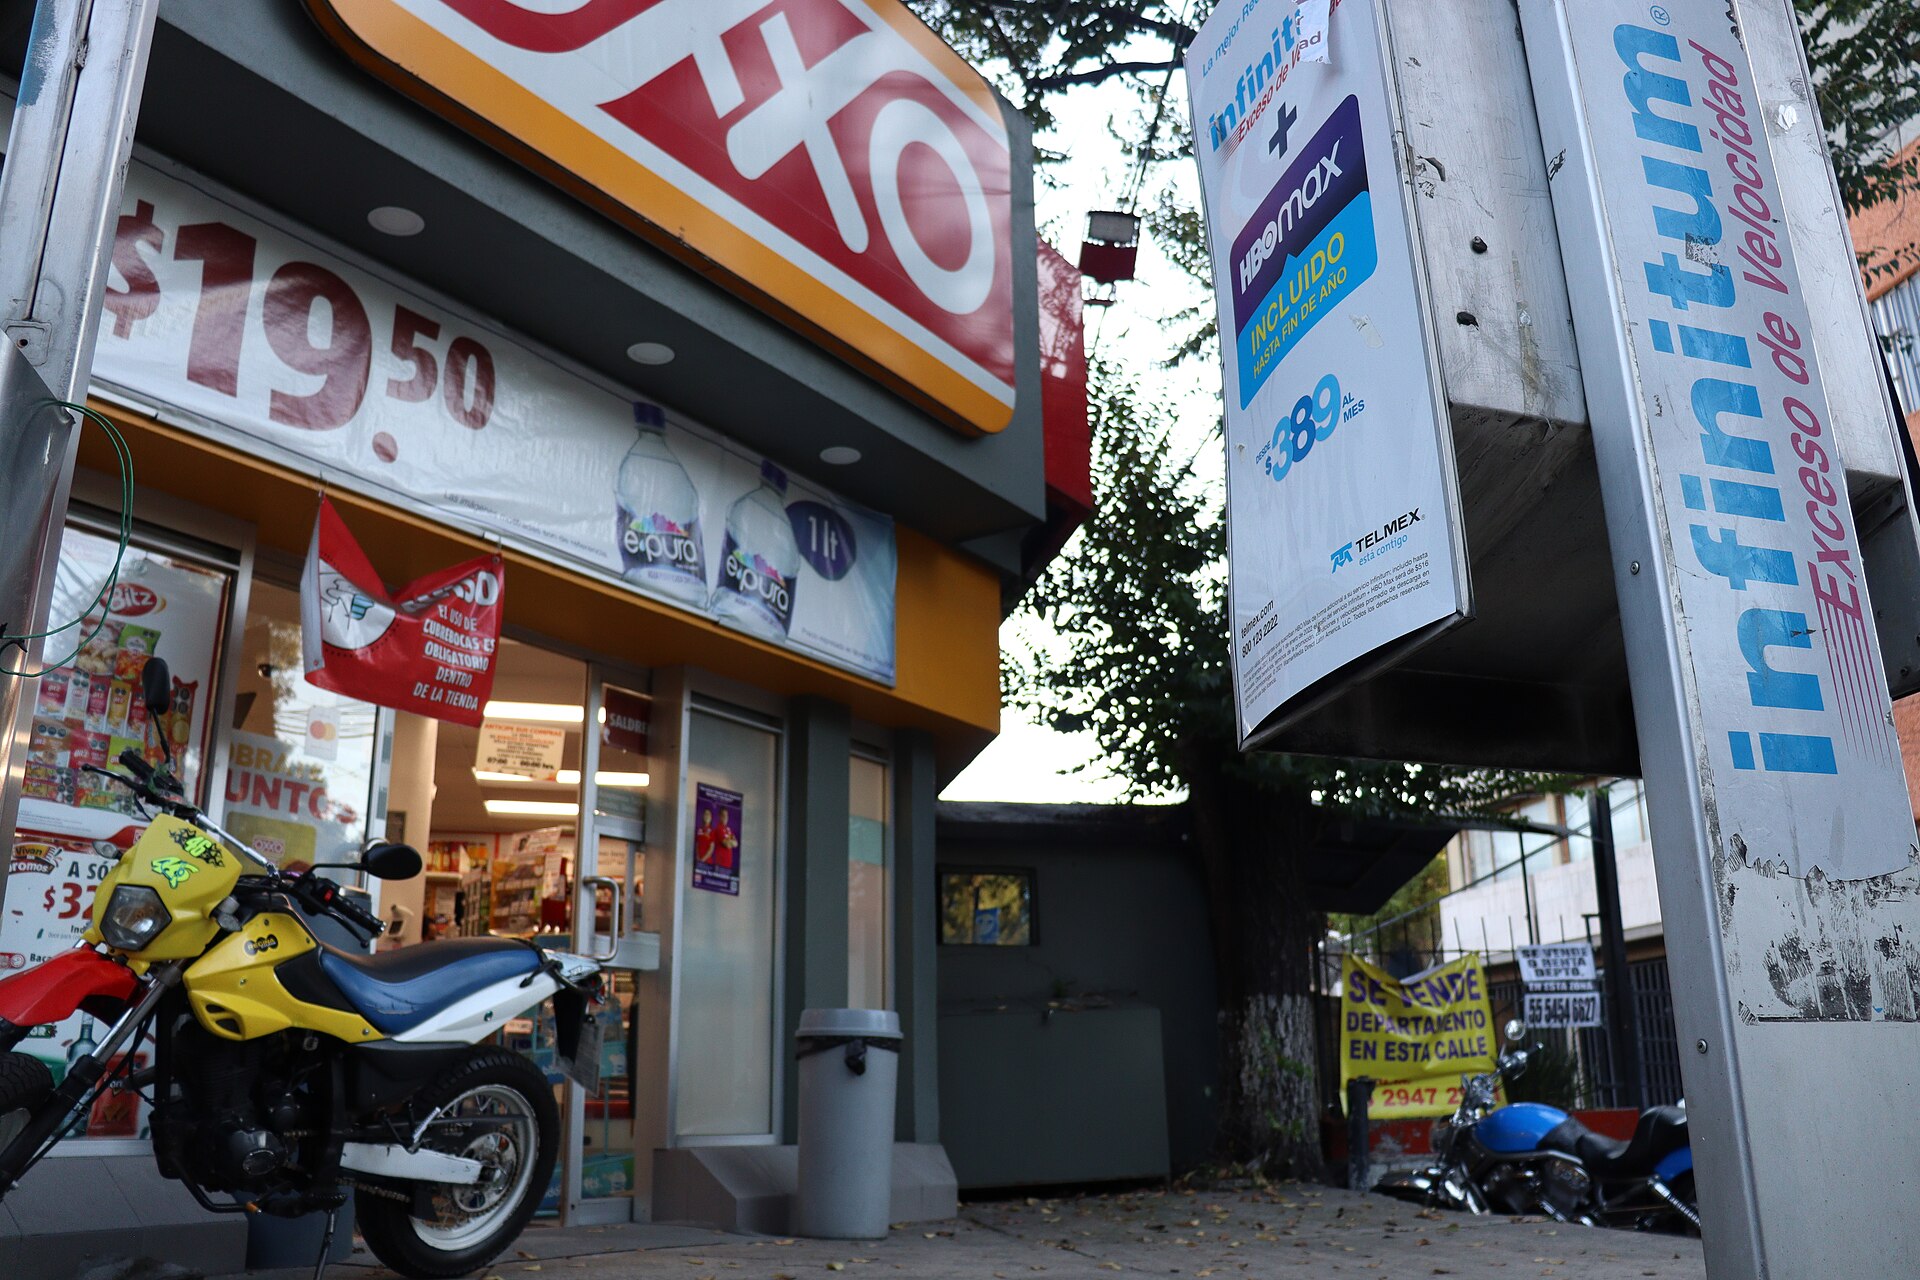
If you live in Mexico, you’ve probably bought a snack or paid a bill at an OXXO. Now FEMSA, the company behind those stores, has paused its plan to turn OXXO into a full bank. Instead, it’s pushing hard on Spin, its payments app, which processed 119.1 million transactions per month in the second quarter of 2026.
Why FEMSA changed course
FEMSA has not given up on banking. It has just paused that plan.
On 31 March 2026, CEO Jose Antonio Fernandez Garza-Lagueera told investors the banking-licence request is on hold.
The priority is to make OXXO stores more efficient and profitable. This is part of a plan called FEMSA Forward.
On the second-quarter call on 28 July 2026, he said FEMSA will need to find funding. That could include getting a banking licence.
Look at the numbers to understand this change. Spin had 119.1 million transactions per month in Q2 2026.
That is up 61.5% from the same time last year. Active users reached 11.5 million, up 22.1%.
This is strong engagement to build on. And it happens without the heavy rules of a bank charter.
Spin by OXXO is not a bank. It never was.
It is an IFPE, which means Institucion de Fondos de Pago Electronico. Mexico’s CNBV allowed this on 7 October 2022.
In simple words, Spin can hold and move money for customers. But it cannot lend deposits like a bank does.
That difference is the main point of this story.
FEMSA is testing a small credit pilot programme. CFO Martin Arias spoke about off-balance-sheet structures as the credit book grows.
Off-balance-sheet means the debts are not shown fully on FEMSA’s main financial reports. If this business matures, FEMSA could use that funding option.
Then it might look at a banking licence again later.
So this is a ‘maybe later’, not a ‘yes now’. For now, the plan is to use the Spin system to keep customers inside the OXXO world.
That includes payments, credit, and other services.
Credit is a big part of this new phase. After years of growing users and transactions, Spin now wants to make money.
Credit is one key way to do that. The small pilot is the first step.
If it works, FEMSA could expand it without needing a bank licence right away.
There is clear proof that the credit business is growing. QED Investors has bought a strategic equity stake in FEMSA’s lending unit.
FEMSA still keeps control of that unit.
If you follow Mexican retail or fintech, this shows where growth is. FEMSA is choosing a digital-first path instead of a traditional bank model.
It is betting that millions of store visits can turn into app use.
The credit experiment
Live Company IntelligenceFomento Económico Mexicano S.A.B. de C.V — the full investor dossier
What this means for investors and expats
For anyone living in Mexico, it means Spin could become a bigger part of daily life — paying for goods, maybe taking small loans. The US dollar was trading at 17.0188 pesos, so the stakes are clear: a successful fintech play could add large value in dollar terms.
And the market has taken notice.4% and up from 42 cents a year earlier. That earnings beat, driven partly by OXXO Mexico and Coca-Cola FEMSA, suggests the strategy is already paying off.
The pause on the banking license also reduces regulatory risk in the near term, which can be a plus for shareholders watching how FEMSA allocates capital. With the stock trading at $118.12 as of August 14, 2026, up 1.39% on the day, investors seem to be taking the news in stride.
The bigger fintech picture
FEMSA isn’t alone in chasing digital payments in Latin America. The region has seen a wave of app-based financial services, from Brazil’s Nubank to Argentina’s MercadoLibre, and Spin is FEMSA’s answer to that trend.
The key difference: OXXO’s physical footprint. With 24,708 stores in Mexico as of 30 June 2026, FEMSA has a distribution channel that pure digital players lack — a real advantage for cash-based customers making the leap to apps.
By keeping the banking license on the back burner, FEMSA can move faster and lighter, testing products like credit without the heavy compliance costs of a full bank. That flexibility is a competitive edge in a region where fintech is still evolving.
Why this matters for Latin America
This story isn’t just about one company. It’s a window into how big retailers across Latin America are choosing digital apps over traditional banking structures to reach millions of underbanked people.
For you, whether you’re a local or an expat, that means more options for everyday payments and credit, often with lower fees and faster approval times than traditional banks. And if FEMSA’s credit pilot succeeds, you could see similar moves from other retailers in the region.
FEMSA believes that small shops and big size will beat strict rules. If Spin keeps growing this fast, you may never need a bank branch.
Just use a corner store and a smartphone.
Background: our nearshoring mexico guide.
More: Mexico news in English, every day from The Rio Times.
Sources: FEMSA dijo adiós al plan de convertir a OXXO en banco …; Fomento Económico Mexicano, S.A.B. de C.V. (FMX): Running ..; FEMSA Files 2025 Annual Reports with U.S. and Mexican …; Spin by OXXO cambia de rumbo: FEMSA busca ganar dinero con e; FEMSA Q2 Earnings & Revenues Beat on OXXO Mexico & …
Frequently Asked Questions
Is FEMSA completely dropping its bank plans?
No. The plan to apply for a banking license for OXXO is paused, not abandoned. On the second-quarter call, the CEO said FEMSA will look for funding sources, which could include obtaining a banking license.
How many transactions does Spin process monthly?
Spin averaged 119.1 million transactions per month in the second quarter of 2026, a 61.5% increase compared to the same period in 2025. Active users came to 11.5 million, up 22.1%.
What is FEMSA focusing on instead of banking?
FEMSA is prioritizing Spin, its payments app, along with digital payments, credit services, and monetizing the OXXO network. It’s running a small-scale credit pilot program currently.
Why does this matter for anyone in Latin America?
It shows how major retailers are choosing digital payment apps over traditional banking structures, which could shape how millions of people access financial services in the region.
This article was produced by The Rio Times’ automated AI newsroom. Editorial responsibility: Matthias Camenzind, Publisher and Editor-in-Chief. The Rio Times also runs Ask Rio Times, which answers from 100,000+ of our own articles, the daily Latin America Power Map, and prediction-market odds on elections and markets.. How we use AI · Report an error