
CHILE · ANALYSIS
Key Facts
- —What is happening The ASEAN+3 Macroeconomic Research Office warned on 5 October 2026 that Asia’s AI-linked trade and finance are vulnerable to a sharp correction, which would cut copper and lithium demand.
- —Why it matters A price fall would hit exports, currencies and state revenues in both countries.
- —The numbers AMRO says an AI slowdown could cut ASEAN+3 growth by up to 1.5 percentage points in 2027; Cochilco forecasts a 2026 average copper price of US$5.95 per pound.
- —What to watch Chile’s Central Bank next meets on 26-27 October 2026.
- —What it means for you US-listed miners such as Freeport-McMoRan and Southern Copper could fall faster than commodity prices if an AI reversal tightens credit and investor confidence.
An AI boom reversal would hit copper and lithium demand first through financial markets and investment expectations, then through slower orders for data centres, grid equipment and batteries. For US investors holding miners, ADRs or chip-supply-chain stocks, the warning from Asia’s macroeconomic watchdog is a signal to reprice Latin American commodity exposure before physical demand data deteriorate.
Chile is the world’s largest copper producer and a major lithium supplier, while Peru and Argentina are also deeply tied to the same global technology cycle. This analysis explains what the Asia Intelligence Brief warning means for Latin America’s miners, budgets and US-listed securities.
The Warning From Asia’s Macroeconomic Watchdog
The ASEAN+3 Macroeconomic Research Office, known as AMRO, is the regional surveillance body for the ten Southeast Asian economies plus China, Japan and South Korea. On 5 October 2026 it published a financial stability report arguing that the region is unusually exposed to a reversal in the artificial-intelligence boom.
Stronger demand could keep lifting exports and investment, but weaker demand could reverse those gains.
The transmission channels AMRO identifies are direct and financial. Lower semiconductor and electronics exports, reduced capital expenditure by technology firms, portfolio losses, refinancing pressure on leveraged data-centre businesses and tighter credit conditions would all feed into slower growth.
Elevated equity valuations are not proof of an imminent reversal. The relevant question for commodity markets is whether elevated equity valuations are supported by continuing physical demand for servers, chips, electricity, networks and data centres.
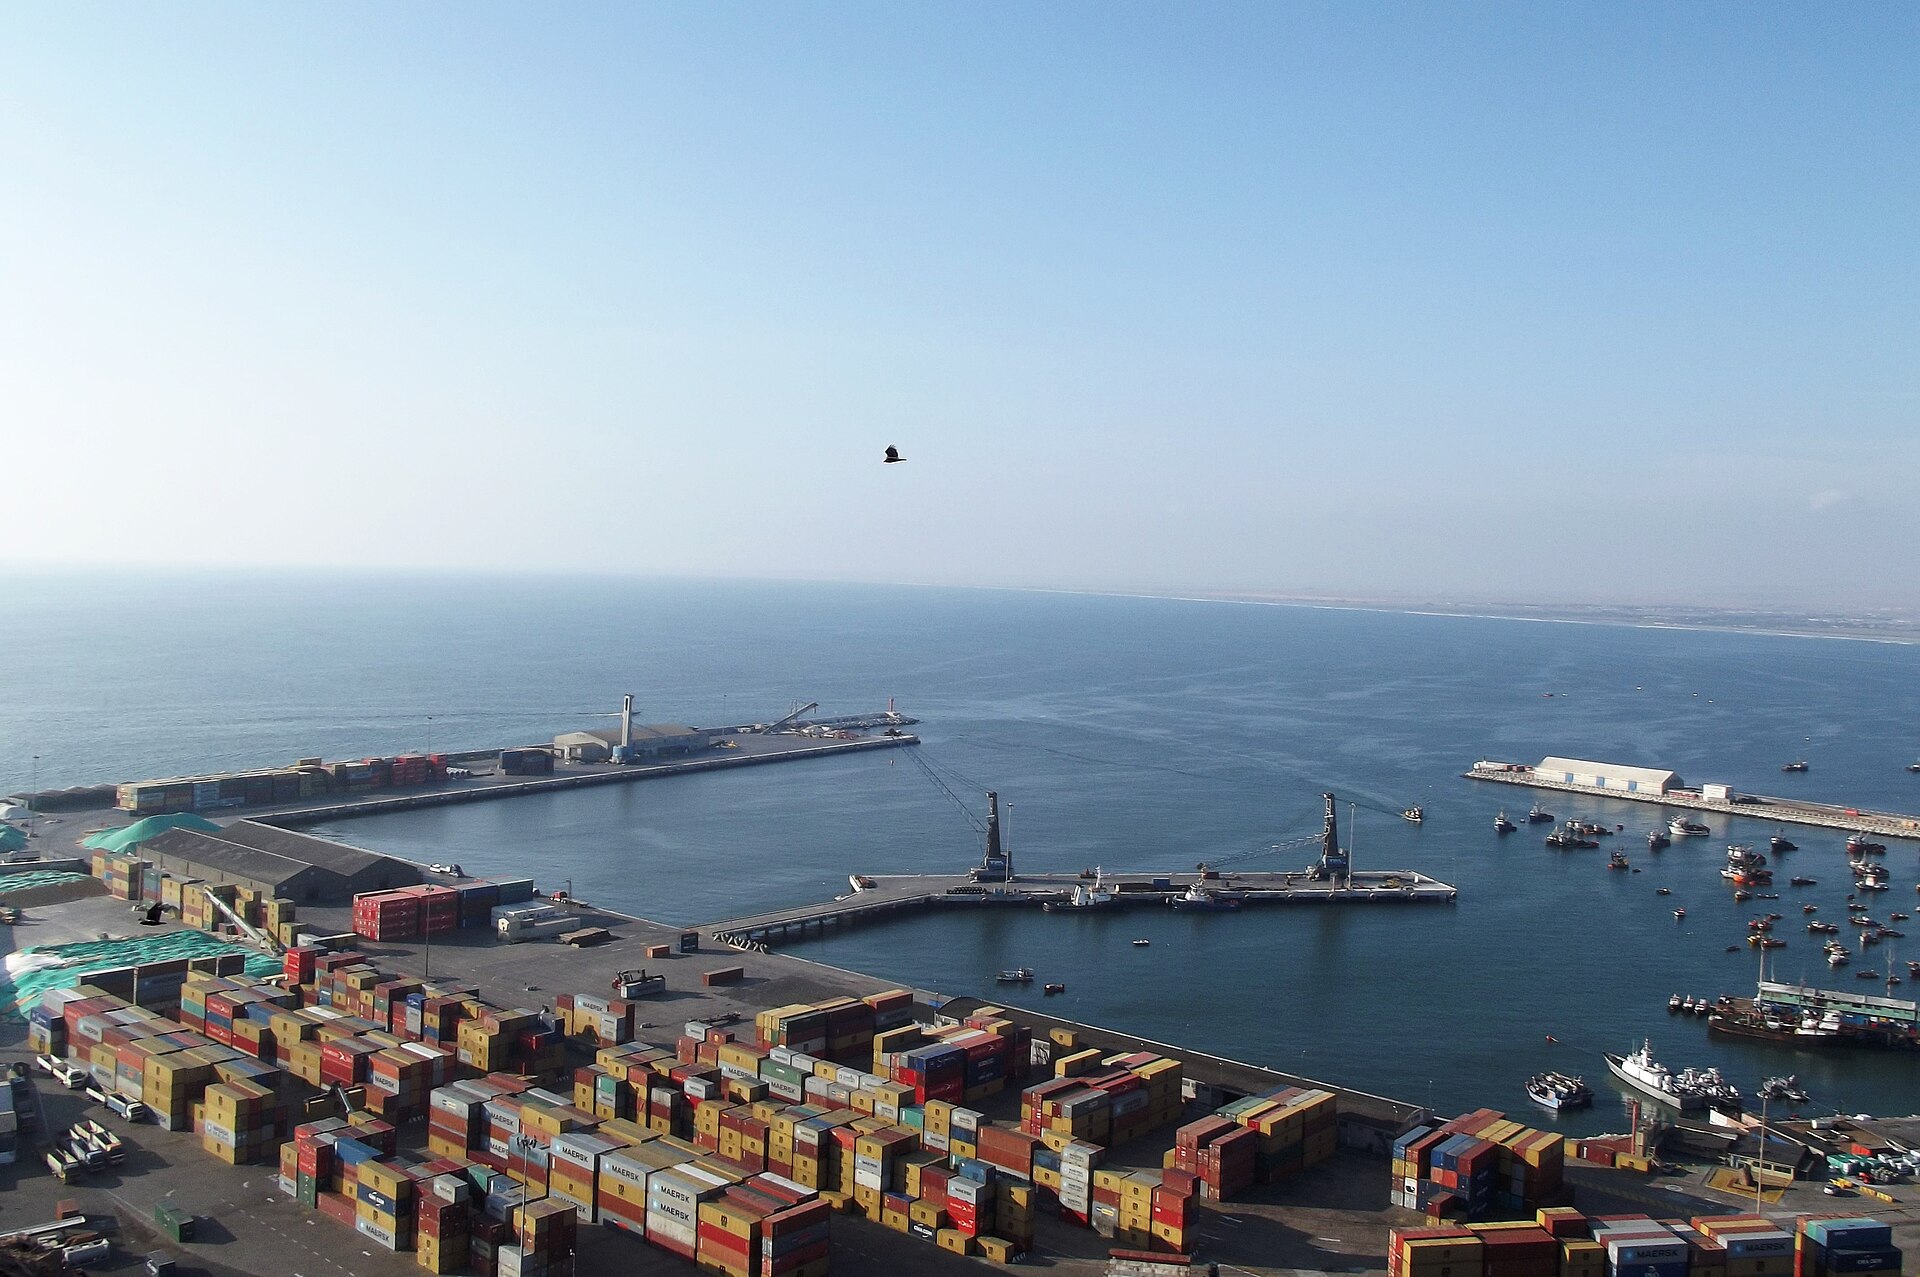
How an AI Reversal Would Hit Copper First
Copper has a strong structural connection to AI investment, but the link is indirect. Data centres, server racks, electricity generation and transmission, cooling systems, grid connections, networking equipment and semiconductor fabrication all use copper. A decline in AI capital expenditure would reduce the growth rate of copper consumption across construction, power infrastructure, electrical equipment and electronics.
The likely sequence would start in financial markets. Copper futures and mining equities would fall as investors priced lower future demand. Project deferrals would follow, then physical-demand slowdowns in orders for electrical equipment and grid infrastructure. High-cost producers would eventually cut output, limiting the price decline.
Copper would not necessarily collapse in proportion to AI spending. AI is only one component of global copper demand, alongside construction, transport, industrial machinery, power grids, defence and ordinary electronics. Grid investment linked to electrification and renewable generation can continue even if data-centre construction slows.
Chile’s Copper Sensitivity
Chile is especially sensitive because copper is central to exports, fiscal revenues, investment and the exchange rate. The Chilean Copper Commission, Cochilco, reduced its 2026 national production forecast on 11 August to 5.27 million tonnes, down 2.6% from 2025.
A lower copper price would affect Chile through lower export receipts, reduced mining-company profits and tax payments, weaker investment in mine replacement and infrastructure, pressure on the Chilean peso, and lower fiscal revenue. The Central Bank of Chile held its monetary-policy interest rate at 4.5% at its September 2026 meeting while flagging strong activity in economies connected to the AI production chain.
Chile’s exposure is not limited to the spot price. A prolonged fall could also affect the economics of projects requiring high capital expenditure, including underground mine development, water infrastructure, energy projects and processing capacity.
Peru’s Copper Sensitivity
Peru is also highly exposed to copper, but the transmission would run more strongly through mining investment, regional employment, tax revenues and the balance of payments.
A downturn would be most painful for new mine construction, brownfield expansions, mining-service companies, regions dependent on large copper operations, and public investment funded by mining-related revenues. Peru’s relatively large copper pipeline could provide a partial buffer if existing projects remain competitive, but new projects are more price-sensitive than producing mines.
Live Market IntelligenceChile — Live Market Board
Rio Times · Live Market Intelligence
Chile — Live Market Board
+0.08%
192,114.55
+2.63%
64,531.68
+1.10%
10,916.57
+0.08%
2,767,663
+0.32%
2,515.02
-0.59%
59,751.67
+0.18%
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IPSA | 10,916.57 | +0.08% | — | 10,908.18 | 11,210 | 10,984 | 1,513,213,483 |
| USD/CLP | 913.98 | +0.04% | -5.67% | 913.65 | 915.11 | 906.68 | — |
| COPPER | 6.61 | +0.03% | +46.70% | 6.61 | 6.71 | 6.61 | 39,543 |
| SQM-B | 65,305 | -0.84% | +49.03% | 65,860 | 66,949 | 64,978 | 76,539 |
| COPEC | 5,964 | -1.09% | -11.70% | 6,030 | 6,100 | 5,960 | 634,331 |
| BSANTANDER | 78.37 | -2.28% | +35.94% | 80.20 | 81.69 | 78.34 | 36,288,711 |
| FALABELLA | 6,334 | -1.48% | +23.28% | 6,429 | 6,450 | 6,300 | 26,085,814 |
| ENELAM | 87.09 | +0.10% | -10.13% | 87.00 | 87.40 | 86.50 | 13,106,417 |
| CENCOSUD | 1,946 | -2.19% | -35.30% | 1,990 | 2,010 | 1,945 | 966,528 |
| CMPC | 1,020 | -1.96% | -29.10% | 1,040 | 1,050 | 1,015 | 3,526,677 |
| BANCO CHILE | 184.96 | -1.01% | +32.87% | 186.85 | 189.99 | 184.33 | 18,101,240 |
| LATAM AIR | 24.08 | -1.11% | +16.61% | 24.35 | 24.59 | 23.88 | 573,612,753 |
| SOUTHERN COPPER | 193.97 | -0.26% | +104.01% | 194.48 | 199.36 | 192.59 | 367,102 |
Lithium Faces a Sharper Oversupply Risk
Lithium’s exposure to AI is real but less direct than copper’s. AI data centres use lithium-ion batteries in backup power systems, uninterruptible power supplies, energy-storage systems and grid-balancing installations. However, the lithium market is dominated by electric vehicles and stationary storage rather than AI hardware itself.
An AI reversal would affect lithium through two channels: less construction of data centres and associated storage systems, and a broader industrial and financial slowdown that weakens EV sales, battery investment and consumer demand. The main vulnerability is that lithium supply can expand faster than demand in some periods. If producers continue bringing capacity online while battery demand slows, prices can fall sharply.
Chile’s lithium is a non-concessionable resource, and the National Lithium Strategy seeks to expand production through public-private partnerships.
Argentina’s Lithium Exposure
Argentina is more exposed to lithium growth than to copper. The country has become one of the fastest-growing lithium jurisdictions, with production expanding from a relatively small base.
Argentina’s risks in an AI-related or broader battery downturn include lower lithium prices reducing export receipts, delays to new brine projects, more difficult financing for companies operating in Salta, Jujuy and Catamarca, and weaker provincial royalties and employment. Argentina also has a potential advantage: much of its lithium capacity is still in development, so a slowdown could prevent an excessively rapid buildout and allow the market to rebalance.
US-Listed Miners, ADRs and the Chip Supply Chain
US investors can obtain exposure through several layers. US-listed or US-traded miners with copper exposure include Freeport-McMoRan Inc., listed on the New York Stock Exchange, with major copper operations in the Americas; Southern Copper Corporation; Rio Tinto plc, whose American Depositary Receipts trade in the United States; BHP Group Limited, whose US ADRs provide exposure to its global mining portfolio; and Vale S.A., whose US ADRs provide broader metals exposure, though its dominant commodity is iron ore rather than copper.
For lithium, Sociedad Química y Minera de Chile S.A., known as SQM, is exposed to Chilean lithium and specialty chemicals. For Peru, Southern Copper is the clearest major US-listed vehicle with direct Peruvian copper exposure.
The share-price effect would not simply mirror copper or lithium prices. Investors would also price production guidance, cash costs, debt and refinancing needs, capital expenditure, political and permitting risk, hedging arrangements, dividend policy, currency movements and the valuation of undeveloped projects.
A copper or lithium slowdown could also affect US-listed companies tied to the chip supply chain, including semiconductor designers and manufacturers, equipment suppliers, memory-chip producers, data-centre infrastructure companies, and power-management and cooling-equipment suppliers. The financial channel AMRO describes could depress commodity prices even before physical consumption data deteriorate substantially.
What It Means for You
If you hold US-listed miners, Chilean or Peruvian ADRs, or semiconductor and data-centre stocks, the AMRO warning is a prompt to check your exposure to a single assumption: that AI capital expenditure will keep rising. Mining equities are likely to fall more than the underlying commodities at first, because share prices also reflect financing costs, project delays, country risk and expected future growth.
The Chilean peso and Peruvian sol could weaken if export revenues and portfolio inflows decline. Argentina’s impact would be filtered through its exchange-rate and capital-control regime. Fiscal revenues generally lag prices because contracts, tax payments and production decisions adjust with delays.
Copper’s downside would probably be greatest if an AI reversal coincided with a Chinese industrial slowdown, a US recession or a stronger dollar. Lithium’s downside would be greatest if weaker AI investment arrived alongside slower EV adoption, falling battery prices and continued supply expansion.
What Is Not Known
AMRO’s report is not a forecast that AI demand will collapse. It is a warning that the region’s growing dependence on AI-related trade and finance makes a correction unusually consequential. The timing and depth of any reversal remain unknown.
The exact price levels at which copper and lithium would stabilise are not established. Copper is supported by supply constraints, grid investment and declining ore quality, while lithium is potentially more volatile because supply additions can arrive quickly and prices are less standardised across chemical forms, purity, contract structure and location.
The outcome of Chile’s Centinela mine labour dispute is not yet known. Workers voted 98.73% in favour of strike action in voting held 26-28 September 2026, and government-mandated mediation began in early October 2026. A legal strike could follow only if mediation fails.
What to Watch
Chile’s Central Bank next meets on 26-27 October 2026. Its September statement flagged strong activity in economies connected to the AI production chain, so the October meeting will show whether the bank is adjusting its view.
A strike at a major Antofagasta Minerals operation would add supply-side pressure to the copper market at a sensitive moment.
Chile’s September 2026 copper-production data from the Instituto Nacional de Estadísticas is due in October 2026. August production was 369,500 metric tonnes, a 12.8% year-on-year decline and the lowest monthly figure since February 2011, according to INE data reported by Trading Economics.
Chile’s 2027 budget, submitted to Congress by the end of September 2026, has a 60-day approval window. The budget’s copper-price assumptions will be tested against market prices and the AMRO warning.
Related reading: Chile Culture, the Key Figures to Know in 2026; Chile Politics Explained, Who Holds Power in 2026; Chile Geopolitics Explained 2026; more from Chile.
What happens to copper demand if the AI boom turns?
Copper demand growth would slow because data centres, server racks, electricity infrastructure, cooling systems and networking equipment all use copper. The first impact would be in financial markets, with copper futures and mining equities falling before physical orders weaken.
How exposed is Chile to an AI reversal?
Copper is central to Chile’s exports, fiscal revenues, investment and exchange rate. A price fall would cut export receipts, mining profits, tax payments and pressure the Chilean peso.
What does AMRO’s warning say about Asia and AI?
The ASEAN+3 Macroeconomic Research Office said on 5 October 2026 that Southeast Asia, China, Japan and South Korea are unusually exposed to an AI correction because they sit at the centre of AI manufacturing supply chains. AMRO estimates an AI slowdown could reduce regional growth by up to 1.5 percentage points in 2027.
Which US-listed miners are most exposed to copper and lithium?
Freeport-McMoRan and Southern Copper are the clearest US-listed copper plays. Rio Tinto and BHP also have US ADRs with copper assets, and Vale’s ADRs provide broader metals exposure.
What could cushion a copper or lithium slowdown?
Grid investment linked to electrification and renewable generation can continue even if data-centre construction slows. High-cost producers would eventually cut output, limiting price declines, and Argentina’s lithium capacity is still largely in development, which could help the market rebalance.
When is Chile’s Central Bank next meeting?
The Central Bank of Chile next meets on 26-27 October 2026. Its September 2026 meeting held the monetary-policy interest rate at 4.5%.
Frequently Asked Questions
Sources: riotimesonline.com, chinadaily.com.cn, businesstimes.com.sg, businesstimes.com.sg, businesstimes.com.sg, riotimesonline.com. Retrieved 5 October 2026.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
In depth
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.