Argentina Neighbours Explained, the Southern Cone in 2026
ARGENTINA · SOUTHERN CONE
Key Facts
- —What it is Argentina shares land borders with Chile, Bolivia, Paraguay, Brazil and Uruguay, forming the core of the Southern Cone.
- —Why it matters Argentina neighbours absorb a large share of its exports, supply most of its imports and share the rivers, energy links and migration flows that define its economy.
- —The numbers In 2025 Argentina exported US$87.077 billion in goods and imported US$75.791 billion, a surplus of US$11.286 billion, according to INDEC data summarised by the Foreign Ministry.
- —The catch Argentina runs a large deficit with Brazil inside Mercosur, while its surplus with Chile depends on energy exports and Andean crossings that remain vulnerable to weather and congestion.
- —What it means for you A foreigner doing business in Argentina is really doing business with the Southern Cone: supply chains, ports, energy and labour all cross these borders.
Argentina neighbours are not a backdrop to the country; they are its operating system. Brazil, Chile, Paraguay, Uruguay and Bolivia shape how Argentina trades, where its energy flows and who crosses its borders.
Argentina sits at the centre of the Southern Cone, the southernmost economic and geographic bloc of South America. This guide explains the borders, rivalries, shared rivers, trade patterns and regional institutions that connect Argentina to its five immediate neighbours.
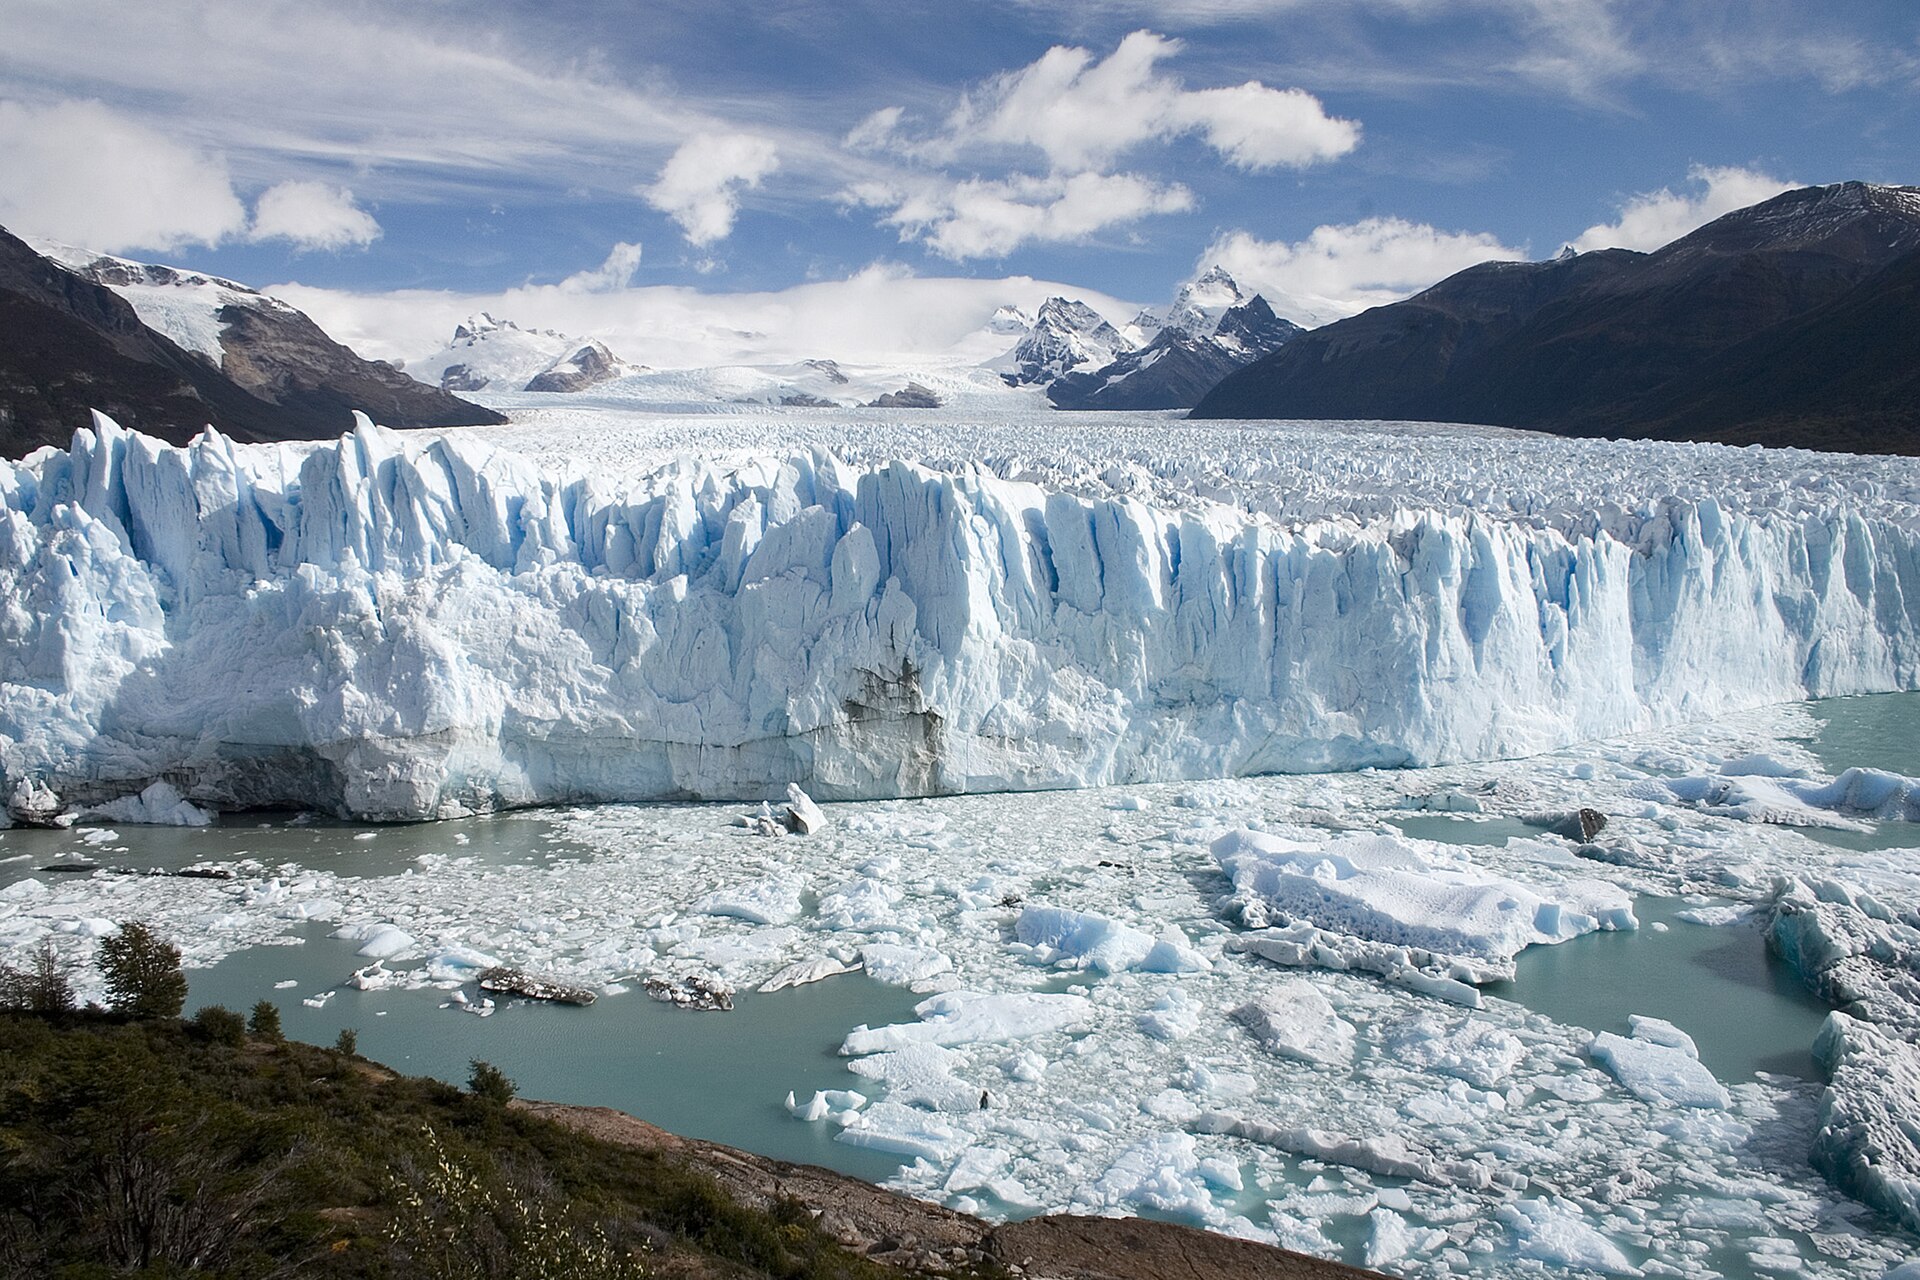
The Southern Cone map: five borders, one neighbourhood
Argentina shares land borders with five countries. Chile is the longest, at approximately 5,300 km, running the full length of the Andes. Paraguay follows at roughly 1,700 km, Brazil at about 1,263 km, Bolivia at around 750 km and Uruguay at approximately 580 km.
These are not equal relationships. Brazil is the dominant economic partner. Chile is the strategic Pacific link. Paraguay and Bolivia depend on Argentine rivers and roads for access to the Atlantic. Uruguay is the closest social and cultural neighbour, separated only by the Río de la Plata.
Argentina also claims a sector of Antarctica and several South Atlantic territories, including the Falkland/Malvinas Islands, South Georgia and the South Sandwich Islands. Those claims are not borders with sovereign neighbours, but they shape Argentina’s regional diplomacy and maritime posture.
The Southern Cone is not a formal political unit. It works through overlapping systems: Mercosur’s customs and transport network, the Paraná–Paraguay waterway, Andean crossings, energy interconnections and large cross-border migrant communities. Understanding Argentina neighbours means understanding these systems together.
Brazil: the essential partner and the principal commercial tension
Brazil is Argentina’s largest regional partner and most important neighbouring economy. The relationship combines industrial interdependence, presidential diplomacy and recurring disputes over trade policy, exchange rates and Mercosur’s future.
In 2025, Brazil accounted for 14.7% of Argentina’s merchandise exports and 24.3% of its imports, according to Argentina’s Foreign Ministry summary of INDEC data. The bilateral balance was nevertheless unfavourable for Argentina: a US$5.653 billion trade deficit with Brazil in 2025.
The main commercial links are automobiles and automotive parts, chemicals and petrochemicals, machinery, agricultural products, energy and manufactured food and beverages. These sectors are deeply integrated. Neither country can easily replace the other as a nearby market for manufactured exports or as a supplier of industrial inputs.
Brazil is also the dominant supplier within Mercosur.
The principal rivalry is not military. It concerns regional leadership and economic strategy. Brazil generally favours preserving Mercosur as a negotiating platform, while Argentina under President Javier Milei has advocated greater flexibility, lower barriers and stronger unilateral economic opening. The two positions can coexist, but they create friction over common tariffs, external trade negotiations and the bloc’s institutional direction.
Chile: the closest strategic partner outside Mercosur
Chile is Argentina’s most important western neighbour and its natural link to the Pacific. The Andes make the border physically difficult but economically indispensable. Unlike Brazil, Chile is not a Mercosur member. It is an associate country with its own extensive network of free-trade agreements.
The bilateral relationship is comparatively cooperative. It rests on the Argentina–Chile Free Trade Agreement, implemented through the Latin American Integration Association framework, plus energy and electricity exchanges, mining investment, tourism, family ties and road crossings through the Andes.
The trade relationship has traditionally favoured Argentina. In 2025, Argentina recorded a US$5.412 billion trade surplus with Chile, one of its largest bilateral surpluses. That surplus reflects Argentine exports of energy, fuels, agricultural products and manufactured goods, while Chile supplies machinery, chemicals, minerals and consumer products.
The main operational issue is not territorial rivalry. It is infrastructure capacity and winter reliability. The Cristo Redentor/Los Libertadores corridor near Mendoza is the principal commercial route, yet snowfall, congestion and customs delays can disrupt trade. Other corridors through Neuquén and northern Argentina are relevant to mining and energy projects.
Energy cooperation has become more important. Argentina’s Vaca Muerta shale formation can supply Chile through pipelines and electricity links, while Chile offers Pacific-facing infrastructure and potential access to liquefied natural gas and Asian markets. The strategic opportunity is a trans-Andean system connecting Argentine gas production, Chilean electricity and industrial demand, Pacific ports and mining operations in both countries.
Paraguay and Uruguay: rivers, electricity and close social ties
Paraguay is Argentina’s neighbour with the deepest dependence on shared waterways. The Paraná and Paraguay rivers link the two economies, while the Paraguay–Paraná waterway provides an outlet for landlocked Paraguay’s exports. The main shared interests are navigation, port access, hydroelectricity, customs, agricultural trade, migration and water management.
Argentina and Paraguay jointly operate or share interests in major hydroelectric infrastructure, particularly Yacyretá on the Paraná River, operated by the binational entity EBY. Yacyretá is one of Argentina’s most important sources of hydroelectric power and a major symbol of bilateral cooperation. Its performance depends on river flows, maintenance, transmission infrastructure and the financial relationship between the two countries.
The economic relationship is less balanced than Argentina’s relationship with Brazil. Paraguay is a major supplier of agricultural commodities and a significant participant in river logistics, while Argentina is an important market, transit route and service provider. Paraguay has periodically challenged Argentine tolls and administrative requirements on the Paraná waterway, arguing that charges affect its exporters and violate regional navigation arrangements.
Uruguay is Argentina’s most socially integrated neighbour. The Río de la Plata is a shared estuary, and the two countries have extensive family, tourism, investment and transport links. The relationship is also marked by periodic disputes over shared environmental and infrastructure issues, especially pulp mills, river navigation, port competition, bridge and ferry links, dredging and energy trade.
The most prominent modern dispute concerned pulp mills on the Uruguay River. Argentina brought the matter before the International Court of Justice, alleging that Uruguay had failed to comply with procedural obligations under the bilateral river statute. The Court’s 2010 judgment found procedural non-compliance but did not order the closure of the plant. The dispute subsequently moved toward monitoring and practical cooperation.
Trade with Uruguay is much smaller than trade with Brazil, but its political importance is disproportionate. In the first quarter of 2026, Argentina exported approximately US$180 million to Uruguay and imported about US$49 million, producing a surplus of roughly US$132 million. Buenos Aires and Montevideo form one of the Southern Cone’s most connected urban and commercial pairs.
Bolivia: borderland integration and energy transition
Argentina’s relationship with Bolivia is shaped by the northwestern border, migration, energy and the movement of goods through the Andes. The two countries share border communities and family networks, road and rail links, energy infrastructure, mineral and agricultural trade, Andean cultural ties and migration flows.
Bolivian nationals form one of Argentina’s largest foreign-born communities, particularly in Buenos Aires and the northern provinces. Bolivian migration is important in agriculture, construction, commerce, textiles and food distribution. Argentine migration to Bolivia is smaller but also significant in border cities, services and professional activities.
Energy has been central to the relationship. Argentina previously depended heavily on Bolivian natural gas, especially when domestic production was insufficient. The development of Vaca Muerta has reduced that dependence and changed the balance of the relationship. Argentina has increasingly sought to use domestic gas for its own market and to export to Chile, while Bolivia’s gas production has faced declining output and infrastructure constraints.
The border also connects Argentina to Bolivia’s lithium-producing regions. Argentina, Bolivia and Chile form the so-called lithium triangle, although their policy models differ. Argentina has generally encouraged private and foreign investment in lithium projects. Bolivia has pursued a more state-centred industrial model. Chile has used a stronger state role while permitting private participation under specific arrangements.
Shared rivers and the Southern Cone water system
Argentina’s international rivers are central to its regional role. The most important are the Paraná, the Paraguay, the Uruguay, the Río de la Plata, the Pilcomayo and the Bermejo. These waterways serve four functions simultaneously: transport, energy, water supply and diplomacy.
The Paraná–Paraguay waterway is the principal regional logistics spine. It connects Paraguay and parts of Bolivia and Brazil with Argentine and Uruguayan ports. Argentina therefore acts both as a trading partner and as a transit state. Its strategic advantage is geographic access to the Atlantic. Its vulnerability is that congestion, low water levels, labour disputes, customs procedures and port capacity can affect multiple economies simultaneously.
The Río de la Plata is governed by bilateral arrangements between Argentina and Uruguay. It is a shared estuary that supports navigation, fishing, tourism and port activity. The Uruguay River, which feeds into it, has been the site of the pulp mill dispute and remains a focus of environmental monitoring and cooperation.
For a foreigner, these rivers are not just geography. They are the arteries of regional trade. A shipment from Paraguay to the Atlantic passes through Argentine waters. A drought on the Paraná can raise freight costs across the Southern Cone. A dispute over tolls can delay exports from multiple countries at once.
Mercosur and regional bodies: where Argentina leads or follows
Mercosur is the main institutional frame for Argentina neighbours. Founded by Argentina, Brazil, Paraguay and Uruguay, it is a customs union with a common external tariff and a negotiating platform for trade agreements. Bolivia became a full member in July 2024 and has up to four years to adopt the bloc’s rules. Chile is an associate member.
Argentina’s role within Mercosur has shifted. Under President Javier Milei, Argentina has advocated greater flexibility, lower barriers and stronger unilateral economic opening. This puts it closer to Uruguay’s long-standing position and in tension with Brazil’s preference for preserving the bloc as a unified negotiating platform.
The numbers show the asymmetry. Argentina’s deficit with the bloc was US$1.877 billion. This means Argentina is both a major beneficiary of Mercosur market access and a net importer within it.
Other regional bodies matter too. The Latin American Integration Association provides the legal framework for the Argentina–Chile Free Trade Agreement. Binational entities like EBY manage shared infrastructure. The International Court of Justice has adjudicated river disputes. These institutions are not glamorous, but they keep the neighbourhood functioning.
What Argentina neighbours mean for foreigners, investors and expats
A foreigner doing business in Argentina is really doing business with the Southern Cone. Supply chains cross borders. Energy flows through shared pipelines and electricity links. Labour markets include large migrant communities from Bolivia, Paraguay and Uruguay. Ports and rivers connect landlocked neighbours to the Atlantic.
For investors, the key numbers are the trade balances. Argentina runs a large deficit with Brazil, a large surplus with Chile, and smaller surpluses with Uruguay and Paraguay. This means different sectors face different regional dynamics. Automotive and industrial supply chains are tied to Brazil. Energy and mining opportunities look toward Chile and the Pacific. Agricultural logistics depend on the Paraná–Paraguay waterway.
For expats, the neighbourhood shapes daily life. Buenos Aires has large Bolivian and Paraguayan communities. Montevideo is a short ferry ride away. Chilean ski resorts and beaches are popular destinations. Border towns like Posadas–Encarnación and the Mendoza–Santiago corridor are hubs of cross-border commerce and commuting.
The risks are real. Weather can close Andean crossings. River levels can fall. Toll disputes can delay exports. Political disagreements over Mercosur can create uncertainty about tariffs and trade rules. But the neighbourhood is also resilient. These countries have managed their differences through institutions, treaties and practical cooperation for decades.
What to watch in the Southern Cone
Several open questions will shape Argentina neighbours in the coming years. The first is Mercosur’s direction. Will Argentina and Uruguay succeed in pushing for more flexibility, or will Brazil’s preference for a unified bloc prevail? The answer affects tariffs, trade negotiations and investment rules across the region.
The second is energy. Vaca Muerta is changing Argentina’s role from gas importer to potential exporter. This affects Bolivia, which has lost a major market, and Chile, which could become a larger customer. The trans-Andean energy system is still under construction, both physically and politically.
The third is infrastructure. The Paraná–Paraguay waterway needs dredging, signalling and administration. Andean crossings need investment to reduce weather disruptions. Port capacity affects multiple countries at once. These are not glamorous issues, but they determine whether the Southern Cone can move goods efficiently.
The fourth is migration. Large cross-border communities are a source of labour, remittances and social connection. They also raise questions about border management, labour rights and public services. How Argentina and its neighbours manage these flows will shape their societies for decades.
The fifth is lithium. Argentina, Bolivia and Chile hold some of the world’s largest lithium reserves. Their different policy models will determine how much of that resource is developed, by whom and for whose benefit. This is a regional question, not a national one.
Frequently Asked Questions
Which countries border Argentina?
Argentina shares land borders with Chile, Bolivia, Paraguay, Brazil and Uruguay. Chile is the longest border at approximately 5,300 km, while Uruguay is the shortest at around 580 km.
Who is Argentina’s largest trading partner in the Southern Cone?
Brazil is Argentina’s largest regional trading partner. In 2025, Brazil accounted for 14.7% of Argentina’s merchandise exports and 24.3% of its imports, according to INDEC data summarised by the Foreign Ministry.
Does Argentina have a trade surplus or deficit with its neighbours?
It depends on the neighbour. In 2025, Argentina had a US$5.653 billion deficit with Brazil but a US$5.412 billion surplus with Chile. In the first quarter of 2026, it had a surplus of roughly US$132 million with Uruguay.
What is the Paraná–Paraguay waterway?
The Paraná–Paraguay waterway is the principal regional logistics spine. It connects Paraguay and parts of Bolivia and Brazil with Argentine and Uruguayan ports, giving landlocked countries access to the Atlantic.
Is Chile a member of Mercosur?
No. Chile is an associate member of Mercosur, not a full member. It has its own network of free-trade agreements, including the Argentina–Chile Free Trade Agreement implemented through the Latin American Integration Association framework.
What is the lithium triangle?
The lithium triangle is the region formed by Argentina, Bolivia and Chile, which hold some of the world’s largest lithium reserves. The three countries have different policy models for developing lithium, ranging from private investment in Argentina to a more state-centred approach in Bolivia.
Sources: indec.gob.ar, indec.gob.ar, indec.gob.ar, indec.gob.ar, indec.gob.ar, indec.gob.ar. Retrieved 2 October 2026.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
Read More from The Rio Times