Lithium Stocks Fall as Yields Rise: Albemarle Down 2.1%, SQM 2.6%
Key Facts
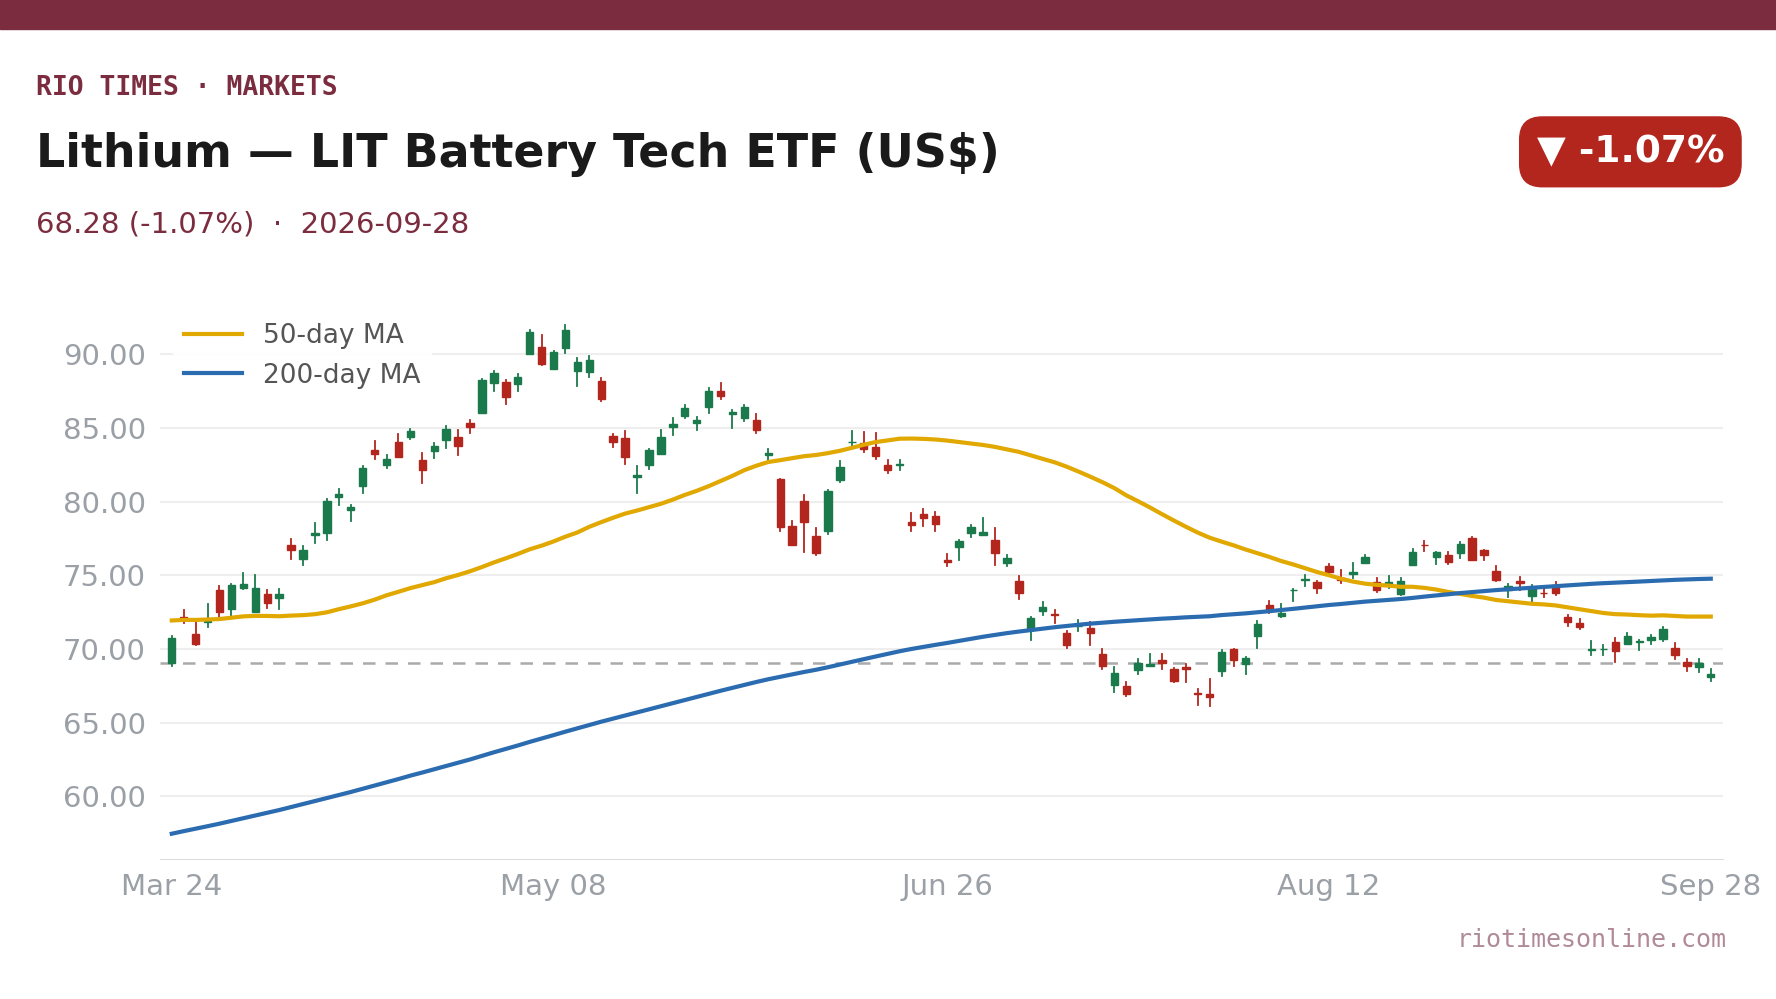
- LIT ETF fell 1.07% to US$68.28 on Monday, as investors sold lithium-mining equities alongside other rate-sensitive growth and commodity names.
- Albemarle dropped 2.13% to US$107.39, making one of the world’s largest lithium producers the second-worst performer among the three proxies tracked here.
- SQM fell 2.59% to US$65.16, the sharpest decline of the three proxies, with no company-specific news on the session.
- Lithium has no deep Western spot benchmark, so the LIT ETF and leading producer shares serve as equity-market proxies for the battery metal.
- Rising US Treasury yields and a firmer dollar were the dominant macro drivers across metals markets on Monday, weighing on future-earnings valuations.
- Chile, Argentina, Bolivia and Peru signed a cooperation declaration on 28 August, covering research and supply chains but setting no production targets or export quotas.
Today’s Focus
Lithium equities retreated across the board on Monday, September 28, 2026, as higher US Treasury yields and a stronger dollar made long-duration growth stories less attractive. The LIT ETF, a basket of lithium miners, refiners and battery-technology companies, fell 1.07% to US$68.28.
Albemarle, one of the world’s largest lithium producers, dropped 2.13% to US$107.39. Chile’s SQM declined even more sharply, losing 2.59% to US$65.16, with no company-specific news on the session.
Lithium has no deep Western spot benchmark, so these equity proxies are how most international investors express views on the battery metal. The session’s weakness mirrored broader selling in gold and other metals as US rate-hike bets rose.
For Latin America, the pullback is a reminder that lithium equities trade as much on US monetary policy as on actual demand for electric vehicles and grid storage.
What matters today. Lithium equities fell because rising bond yields and a stronger dollar compressed valuations for commodity-growth names, not because of any new supply disruption or demand shock in the battery market. Softer lithium prices in China added to the pressure.
01 The session in one read
Lithium equities fell on Monday, September 28, 2026, dragged lower by rising US bond yields and a stronger dollar. The LIT ETF, the closest thing to a broad lithium-equity benchmark, dropped 1.07% to US$68.28.
The two largest names in the battery-metal complex fell harder than the fund. Albemarle lost 2.13% to US$107.39, while Chile-based SQM slid 2.59% to US$65.16.
Monday’s declines were led by SQM and Albemarle, the two names with the most direct exposure to long-term lithium demand from electric vehicles and grid storage. With no new company-specific news on the session, the uniform selling pattern points mainly to a macro rates repricing, with softer Chinese lithium futures adding to the pressure. The variable to watch is the US 10-year Treasury yield at Tuesday’s open; if it keeps climbing, lithium equities may struggle to find support even with solid battery demand.
02 The board
The LIT ETF holds miners, refiners and battery-technology companies, so its move reflects investor appetite for the sector’s equities rather than a raw lithium price. Its 1.07% decline was the gentlest of the three, reflecting the fund’s diversification across geographies and business models.
Albemarle, one of the world’s largest lithium producers and a common vehicle for international investors seeking direct exposure, fell further to US$107.39. SQM’s steeper fall to US$65.16 came without company-specific news; its Chile operations carry extra contractual complexity through the Codelco joint venture.
| Asset | Level | Change |
|---|---|---|
| Lithium (LIT ETF) | US$68.28 | -1.07% |
| Albemarle | US$107.39 | -2.13% |
| SQM | US$65.16 | -2.59% |
Source: RT close, 2026-09-28. Where a commodity has no spot feed, an exchange-traded tracker or leading producer is shown as a labelled proxy.
Live Market IntelligenceThe live market board
Rio Times · Live Market Intelligence
Latin America — Cross-Market Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IBOV | 182,991.13 | -0.26% | +21.85% | 183,476.86 | 168,310 | 167,142 | — |
| IPSA | 11,137.59 | -1.06% | — | 11,256.80 | 11,210 | 10,984 | 1,513,213,483 |
| IPC MEX | 64,737.82 | -0.39% | +12.17% | 64,992.23 | 66,121 | 65,405 | 108,886,187 |
| MERVAL | 2,798,925 | -3.28% | +30.51% | 3,022,485 | 3,042,365 | 2,991,150 | — |
| COLCAP | 2,579.33 | -0.21% | — | 9.04 | 9.05 | 9.02 | 4,133 |
| BVL PERÚ | 60,698.35 | -0.79% | — | — | — | — | — |
| USD/BRL | 5.16 | +0.01% | -5.13% | 5.16 | 5.18 | 5.14 | — |
| EUR/BRL | 5.95 | +1.01% | -5.83% | 5.89 | 5.98 | 5.94 | — |
| USD/MXN | 17.06 | -0.24% | -8.58% | 17.10 | 17.08 | 17.01 | — |
| USD/CLP | 913.98 | +0.04% | -5.67% | 913.65 | 915.11 | 906.68 | — |
| USD/COP | 3,140 | +0.03% | -22.04% | 3,139 | 3,141 | 3,105 | — |
| USD/PEN | 3.36 | -0.66% | -4.82% | 3.38 | 3.38 | 3.35 | — |
| USD/ARS | 1,493 | +0.10% | +12.96% | 1,491 | 1,494 | 1,480 | — |
| USD/UYU | 40.27 | +1.24% | +1.80% | 39.77 | 40.27 | 40.23 | — |
| USD/PYG | 5,939 | +1.68% | -19.54% | 5,841 | 5,939 | 5,925 | — |
| USD/BOB | 11.64 | -0.76% | +72.04% | 11.73 | 11.72 | 11.64 | — |
| USD/DOP | 58.34 | +1.25% | -3.44% | 57.62 | 58.34 | 58.04 | — |
| USD/CRC | 445.92 | +0.89% | -9.71% | 441.97 | 448.50 | 445.92 | — |
Live Company IntelligenceSociedad Quimica y Minera de Chile SA ADR B — the full investor dossier
Wall Street view
Valuation & profitability
Price & risk
$39.7952-wk high
$96.09
Revenue trend · 6y
Ownership
Dividend
03 What moved it
The dominant driver on Monday was macro rather than lithium-specific: rising US Treasury yields and bets on higher Federal Reserve interest rates punished equities whose earnings are heavily weighted toward the future. The US 10-year yield rose to 5.24%. Gold fell 3.7% from Friday to US$4,127.10 an ounce, its lowest level in more than seven weeks on the same dynamic, confirming the cross-metal pressure.
There was no new supply disruption, export quota or contract announcement in the lithium complex. Lithium prices did weaken in China: the most-traded lithium carbonate futures contract was down 4.15% at the midday break on Monday, as domestic metals fell across the board. Albemarle’s second-quarter realised lithium price was US$19.53 per kilogram, versus US$12.17 a year earlier, but that backward-looking data did not shield its shares from the rates repricing.
04 The Latin American read
For the Lithium Triangle of Chile, Argentina and Bolivia, Monday’s selling was an equity-market event rather than a signal about the region’s resource endowment. Chile and Argentina are established producers, while Bolivia remains at an early commercial stage.
The cooperation declaration signed on 28 August by Chile, Argentina, Bolivia and Peru set no production targets, prices or export quotas, so it offers little near-term support against macro headwinds. Under the NovaAndino Litio joint venture, SQM keeps control of the Atacama operations until 2030, and state-owned Codelco takes majority control from 2031.
05 The names to watch
Albemarle remains the bellwether for global lithium pricing power, given its scale and exposure to both hard-rock and brine operations. Its US$19.53 per kilogram realised price in the second quarter shows how far contract pricing has recovered from a year earlier.
SQM is the Latin America-focused play, with second-quarter lithium sales of about 84,100 metric tons of lithium-carbonate equivalent and a Chile-centric corporate structure that keeps governance questions alive. The LIT ETF offers diversified access for investors who want the sector without betting on a single balance sheet.
06 The outlook
The lithium-equity complex faces a tug-of-war between strong underlying demand from electric vehicles and grid storage, and a macro environment that penalises long-duration growth assets. Electric vehicles remain the largest source of lithium demand, and grid storage is growing fast, so the demand floor remains intact.
The risk is that further Treasury yield increases keep compression pressure on lithium equities regardless of battery fundamentals. Tuesday’s trading will hinge on whether bond markets stabilise or extend their sell-off.
07 What to watch
- US 10-year Treasury yield: The single largest macro driver for lithium equities; a continued rise would pressure valuations further.
- Albemarle share reaction: Watch whether the sector leader finds buyers near US$107 or breaks lower, as it sets the tone for the complex.
- SQM-Codelco governance developments: Any fresh news on the 2031 majority-control transition could reprice Chile-specific risk.
- EV sales data from China and Europe: Battery-demand signals can counter macro weakness if they surprise to the upside.
Frequently Asked Questions
Why did lithium equities fall on Monday?
Rising US Treasury yields and a stronger dollar made future-earnings equities like lithium miners less attractive, pushing the LIT ETF down 1.07%, Albemarle 2.13% and SQM 2.59%.
Does the LIT ETF track the spot lithium price?
No. Lithium has no deep Western spot benchmark; the LIT ETF holds shares of miners, refiners and battery-technology companies, making it an equity-market proxy.
Is demand for lithium weakening?
No clear demand shock emerged. Electric vehicles remain the largest source of lithium demand and grid storage is growing fast, so the structural demand story remains intact.
Why did SQM fall more than Albemarle?
No company-specific news explained the gap. SQM fell 2.59% and Albemarle 2.13%; SQM’s Chile operations also carry extra contractual complexity through the NovaAndino Litio joint venture with Codelco.
Source: RT live market data, close of Monday 28 September 2026.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Read More from The Rio Times