Brookfield Buys US$148M in Brazilian Logistics Real Estate
Key Facts
—Buyer — Brookfield, the global alternative-asset manager, is the acquirer.
—Seller — the assets were bought from GLP.
—Assets — the deal covers nine logistics parks.
—Price — about R$750 million (about US$148 million).
—Space — roughly 350,000 square metres of warehouse area.
—Regions — spread across Brazil’s Southeast, Center-West and Northeast.
—Rate backdrop — Brazil’s Selic policy rate stands at 14.25%.
Brazilian logistics real estate changed hands again in late July as Brookfield acquired nine logistics parks from GLP for about R$750 million (about US$148 million), a portfolio of roughly 350,000 square metres that reads less like a growth bet than a yield trade.
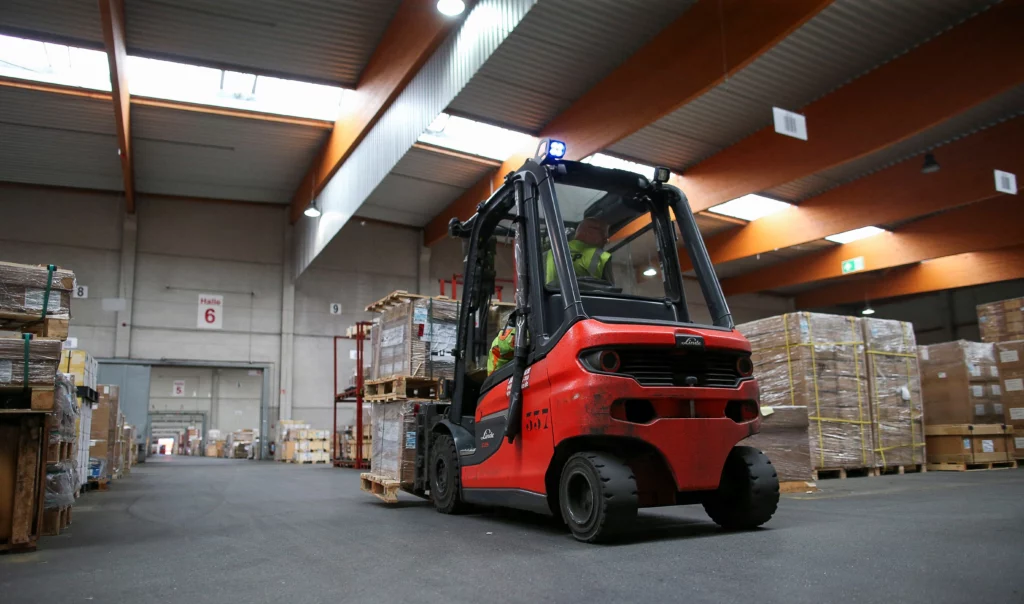
A yield trade, not a growth story
When a global manager buys a portfolio of warehouses in a market where the policy rate sits at 14.25%, the trade usually is not about expansion. Brookfield’s purchase of nine logistics parks from GLP, for about R$750 million (about US$148 million), fits that pattern: it is an income play, built on the rent those roughly 350,000 square metres already generate, rather than a wager on breakneck growth.
The logic is simple. High rates depress the price buyers will pay for future growth and reward assets that produce cash now. Well-let logistics parks, with tenants on multi-year leases, throw off predictable rent — exactly the profile that holds its value when money is expensive.
That is why the framing matters. This is foreign capital consolidating existing Brazilian logistics real estate, not building new capacity on a bet that demand will surge. The distinction shapes how the deal should be read.
What Brookfield bought from GLP
The transaction is defined by a short list of figures. Brookfield acquired nine logistics parks from GLP for about R$750 million (about US$148 million). The portfolio totals roughly 350,000 square metres and is spread across three of Brazil’s regions: the Southeast, the Center-West and the Northeast.
GLP is a large owner and developer of logistics property, and selling a package of stabilised parks lets it recycle capital into new projects or pay down its own funding. For a developer, rotating mature assets to a long-term holder is a normal part of the cycle.
For Brookfield, the appeal is the opposite side of that trade. It is acquiring assets that are already built and largely occupied, avoiding the time, cost and risk of development. The roughly 350,000 square metres come with existing tenants and existing rent, which is the point.
The geographic spread across the Southeast, Center-West and Northeast also matters. It gives the portfolio exposure to more than one regional economy, reducing reliance on any single market’s demand.
The Selic backdrop at 14.25%
No Brazilian real-estate deal in 2026 can be read without the Selic. At 14.25%, Brazil’s benchmark rate is among the highest in the major emerging economies, and it sets the hurdle every asset has to clear. Money parked in government paper earns a lot, so a warehouse portfolio has to offer a competitive yield to justify the risk.
That backdrop pushes buyers towards income and away from speculation. When safe rates are this high, paying up for future growth is expensive, and the assets that look attractive are the ones producing cash today. Logistics parks with signed leases fit the description.
It also helps explain the price discipline. About R$750 million (about US$148 million) for roughly 350,000 square metres implies a buyer focused on the rent yield those metres produce, not on a story about where rents might be in a decade.
If the Selic eventually falls, the calculus shifts. Lower rates would lift the value of exactly these cash-producing assets, which is part of what makes buying yield at a high-rate moment a defensible position.
Why foreign capital is consolidating warehouses
Brookfield is not alone in seeing Brazilian logistics as a place to deploy long-term capital. The sector has been reshaped by e-commerce, the need for modern distribution space and a shift away from ageing, inefficient warehouses towards larger, better-located parks.
For a global manager, the attraction is a combination of scale and structure. Brazil is a large consumer market with a still-maturing logistics footprint, which means demand for quality space has a long runway even if the near-term economy is soft. Owning the parks that serve that demand is a way to capture it.
Consolidation is the natural next step. As institutional buyers move in, ownership shifts from developers and local holders towards large, long-horizon funds that can hold assets through cycles. Brookfield’s purchase from GLP is one more move in that direction.
The risk is that high rates and a slow economy keep a lid on rent growth for a while. But for a buyer underwriting to current income rather than future upside, that is a manageable concern rather than a deal-breaker.
The rent case behind the parks
Strip away the strategy language and the deal rests on rent. Roughly 350,000 square metres of logistics space, spread across three regions and occupied by tenants who need distribution capacity, produces a stream of lease payments. That stream is what Brookfield is buying for about R$750 million (about US$148 million).
Logistics rent has a useful quality: it is tied to the plumbing of consumption. Retailers, distributors and manufacturers need somewhere to store and move goods regardless of the equity-market mood, which makes warehouse income relatively defensive.
The quality of that income depends on the tenants and the leases. Long contracts with creditworthy occupiers make the rent dependable; short leases or weak tenants make it fragile. The details of the nine parks will determine how solid the cash flow really is.
For a yield-focused buyer, that tenant quality is the whole game. The metres and the regions set the scale; the leases decide whether the trade delivers the income it promises.
What to watch next
The immediate question is whether this purchase is a one-off or the first step in a larger build-up. Global managers rarely enter a sector for a single portfolio, and further logistics acquisitions in Brazil would confirm that consolidation is the strategy rather than an opportunistic buy.
The second is the rate path. With the Selic at 14.25%, the deal is underwritten to today’s high-yield environment. Any eventual easing would flatter the economics, while a longer period of tight policy would keep pressure on values and rents.
The third is what GLP does with the proceeds. Recycling capital from about R$750 million (about US$148 million) of asset sales into new development would signal confidence that demand for modern space still justifies building, even at a difficult moment in the cycle.
For now, the read is straightforward. Foreign capital is buying Brazilian warehouse income at a high-rate moment, betting that dependable rent is worth more than a growth story that the current cost of money makes hard to price.
Key Facts
—Buyer. Brookfield, the global alternative-asset manager.
—Seller. GLP, a large logistics-property owner and developer.
—Assets. nine logistics parks totalling roughly 350,000 square metres.
—Price. about R$750 million (about US$148 million).
—Footprint. spread across Brazil’s Southeast, Center-West and Northeast.
—Backdrop. a Selic policy rate of 14.25%.
— Figures as reported for the late-July 2026 transaction; treat all totals as approximate.
This is reporting, not investment advice. Confirm current figures with official sources before acting.
Background: our buying property in brazil as a foreigner complete guide.
Frequently Asked Questions
What did Brookfield buy from GLP?
Nine logistics parks in Brazil, totalling roughly 350,000 square metres across the Southeast, Center-West and Northeast.
How much did the deal cost?
About R$750 million (about US$148 million).
Why buy logistics assets now?
With the Selic policy rate at 14.25%, buyers favour assets that produce dependable rent today over bets on future growth; the parks offer that income.
Is this a growth investment?
Not primarily. It is best read as a yield trade — foreign capital consolidating existing warehouse income rather than building new capacity.
What does the Selic rate have to do with it?
At 14.25%, safe returns are high, so real-estate buyers demand competitive yields and lean towards cash-producing assets like leased logistics parks.
Related reading
- Brazil’s logistics boom and the race for modern warehouse space
- What a 14.25% Selic means for Brazilian real estate
- Foreign funds and the consolidation of Latin American property
Connected Coverage
Brazil’s Financial Morning Call for Monday, August 3, 2026
Brazil’s 2026 Coffee-Festival Calendar: Dates, Cities, Context
Sources: Brookfield; GLP.
This article was drafted with automated assistance and reviewed before publication. How we use AI · Report an error
Read More from The Rio Times