Investing in Costa Rica as a Foreigner in 2026: One Threshold in Doubt
COSTA RICA · INVESTING
Key Facts
- —Where the limits sit Costa Rica concentrates its restrictions on foreign buyers in the coastal strip, not inland.
- —The public zone The first 50 metres from the high-tide line is inalienable national land under Law 6043.
- —The catch The investor residency threshold lost its anchor on 14 July 2026, and no authority has clarified it.
- —The concession rule Foreigners need five continuous years of residence in Costa Rica before holding a coastal concession.
- —Company tax Costa Rica charges 30% on net local company income, with lower bands for smaller firms.
- —What comes next Ask migration for written confirmation of the current amount before committing any capital.
Investing in Costa Rica as a foreigner is ordinary inland. At the coast, and at the residency desk, it is not.

Where This Fits
Investing in costa rica as a foreigner is usually described as unusually open. For most of the country that description holds.
The complications are concentrated in two places. One is the coastline, and the other is the residency file.
Both are worth understanding before money moves. Neither is obvious from the marketing.
Ownership Inland Is the Easy Part
Costa Rica does not spread nationality conditions across its property law. It concentrates them.
The restrictions that exist apply to the maritime zone, where land is held under concession rather than title. Away from that strip the ordinary registered-title system applies.
That is why so much foreign money has gone into the Central Valley and the inland hills. The paperwork there is conventional.
It also explains why beachfront deals generate most of the disputes. The rules there are not the rules elsewhere.
Anyone comparing listings should establish first which regime a property sits under. The price will not tell you.
The distinction is legal rather than scenic. A plot immediately behind the restricted band is ordinary titled land, with none of the coastal conditions attached.
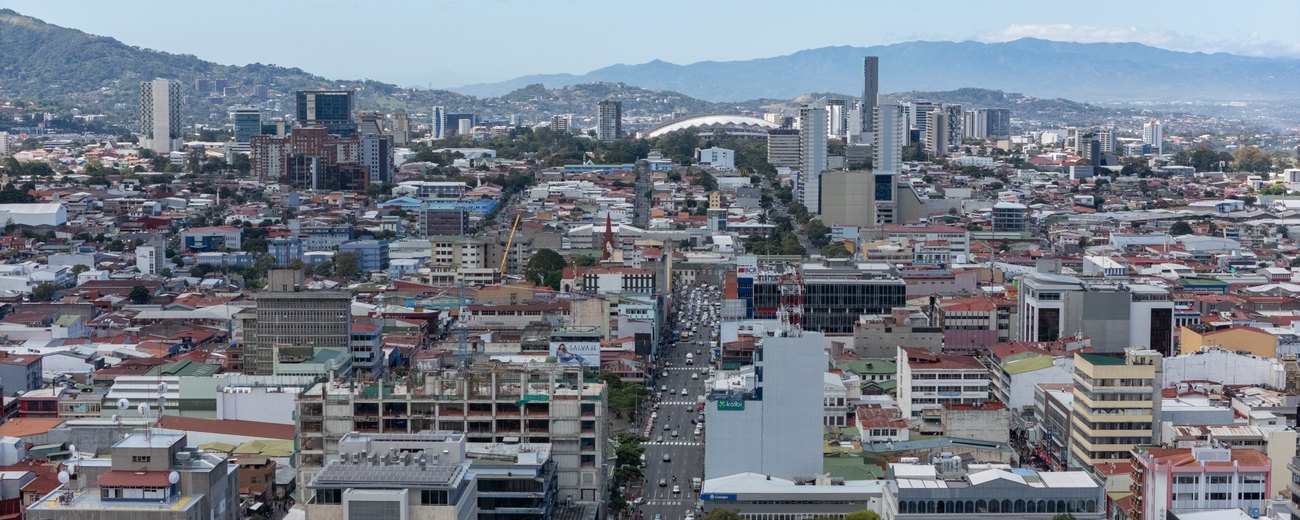
The Coast Runs on Different Law
The governing statute is Law 6043, the maritime terrestrial zone law, enacted on 2 March 1977. It splits the shoreline into two bands.
The first 50 metres from the high-tide line form the public zone. That land is inalienable national property, and no occupation or building right is granted over it.
The next 150 metres form the restricted zone. Municipalities may grant concessions there, which are use rights rather than ownership.
Article 47 sets who may hold one. A foreign national must have resided in Costa Rica for at least five continuous years.
A company holding a concession must be at least half owned by Costa Rican nationals. Entities with bearer shares, or incorporated abroad, are excluded outright.
Concessions run between five and twenty years, with the term set by the municipality. Renewal depends on still meeting the eligibility conditions.
The residence rule catches more buyers than the ownership cap does. Someone arriving with capital but no residence history cannot hold a concession in their own name.
That is why concession property is often marketed through local structures. The requirement for majority national ownership means control genuinely sits with someone else.
The US$150,000 Question Nobody Has Answered
Law 9996 was passed to attract investors, rentiers and pensioners. Article 8 set investor residency at no less than US$150,000.
Article 12 limited the law’s benefits to the first five years after it came into force. That period ended on 14 July 2026.
Here the drafting creates a gap. The sunset in Article 12 refers to the tax benefits in Article 5, such as duty-free imports and property transfer relief.
It does not attach an expiry to the investment amount in Article 8. The implementing regulations, Executive Decree 43926, likewise set no end date on the US$150,000.
The older figure of US$200,000 sat in the general migration regulations, Executive Decree 37112-GOB. That is a lower-ranking instrument than the statute.
No administrative authority has confirmed whether the amount reverted after July. Until one does, an applicant cannot know which figure their file will be judged against.
The practical response is not to guess. Request written confirmation from the migration directorate before committing capital.
The two figures are not interchangeable in practice. An applicant assessed on the higher amount after filing on the lower one loses time as well as money.
How Company Profits Are Taxed
The standard corporate rate is 30% on net income. Smaller companies pay less through a banded scale.
The reduced bands apply where gross income does not exceed 119,174,000 colones, about US$265,700. That conversion uses a rate of 448.50 to the dollar published by open.er-api.com on 18 September 2026.
Within that ceiling the first 5,621,000 colones of net income, about US$12,500, is taxed at 5%. The next slice up to 8,433,000 colones, about US$18,800, is taxed at 10%.
The slice up to 11,243,000 colones, about US$25,100, is taxed at 15%. Anything above that is taxed at 20%.
Registered micro and small businesses get a separate concession. They pay nothing in years one to three.
Then a quarter less in years four and five, and half less in year six. Registration with the relevant ministry is what unlocks it.
Territoriality Has Been Narrowed
Costa Rica taxes on a territorial principle. Only income considered to be of Costa Rican source falls into the net.
That principle is no longer a blanket shield. Since the 2023 reforms, foreign passive income can be taxed where the entity lacks proper substance in the country.
The categories caught include dividends, interest, royalties, capital gains and income from real estate. The test is whether the structure has real presence rather than a registered address.
This matters most to holding companies set up purely to sit offshore of the tax net. A shell with no operations is the case the reform was aimed at.
Anyone planning a structure on the old understanding should have it reviewed. The headline is still territorial and the application is narrower.
What We Could Not Price
Four points remain open and are not stated as facts here.
The first is which investment figure migration is applying today. That is the unresolved gap described above.
The second is the current schedule of migration filing fees. The third is whether temporary residence counts toward the five continuous years required for a concession.
The fourth is how the substance test is applied in practice. The rule is published; the threshold at which a structure passes is not.
What Investing in Costa Rica as a Foreigner Comes Down To
Two of the three main questions have clear answers. Inland title is ordinary, and company tax is a published scale.
The coast is clear too, in the sense that the law is explicit. It simply says something many buyers do not expect.
The open question is the residency threshold, and it is open because of drafting rather than policy. A difference of US$50,000 now rests on an unanswered interpretation.
That is a solvable problem for any individual applicant. It takes one written request to the authority before, not after, the money moves.
Read investing in costa rica as a foreigner as three separate regimes. Treating them as one is what produces the expensive surprises.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
Read More from The Rio Times