Mexico’s 2027 Budget Raises 140 Billion Pesos Without a New Tax
MEXICO · PUBLIC FINANCE
Key Facts
- —The measure A cap on corporate tax deductions, and a cut in the interest-deductibility limit from 30 percent to 20 percent.
- —The yield Hacienda estimates around 135 to 140 billion pesos.
- —Who is caught Firms with revenue above 50 million pesos. Small and micro businesses and companies under five years old are exempt.
- —The framing Sheinbaum: there will be no new taxes.
- —The benchmark The interest change aligns Mexico with OECD base-erosion recommendations.
- —The criticism Analysts describe the package as postponing fiscal adjustment rather than delivering it.
Mexico says it is not raising taxes. It is capping what companies can deduct, which produces the same 140 billion pesos by a different route.
The revenue side of Mexico’s 2027 economic package, presented on 8 September, rests on limiting what companies can deduct rather than on any new levy.
What Actually Changes
The package caps corporate tax deductions and cuts the limit on deductible interest from 30 percent to 20 percent. The finance ministry estimates the combined yield at close to 140 billion pesos.
It applies to firms with revenue above 50 million pesos. Small and micro businesses, and companies less than five years old, are exempt.
The interest-deductibility change tracks OECD recommendations on base erosion and profit shifting, which is the technical justification for describing it as anti-avoidance rather than as a tax increase.
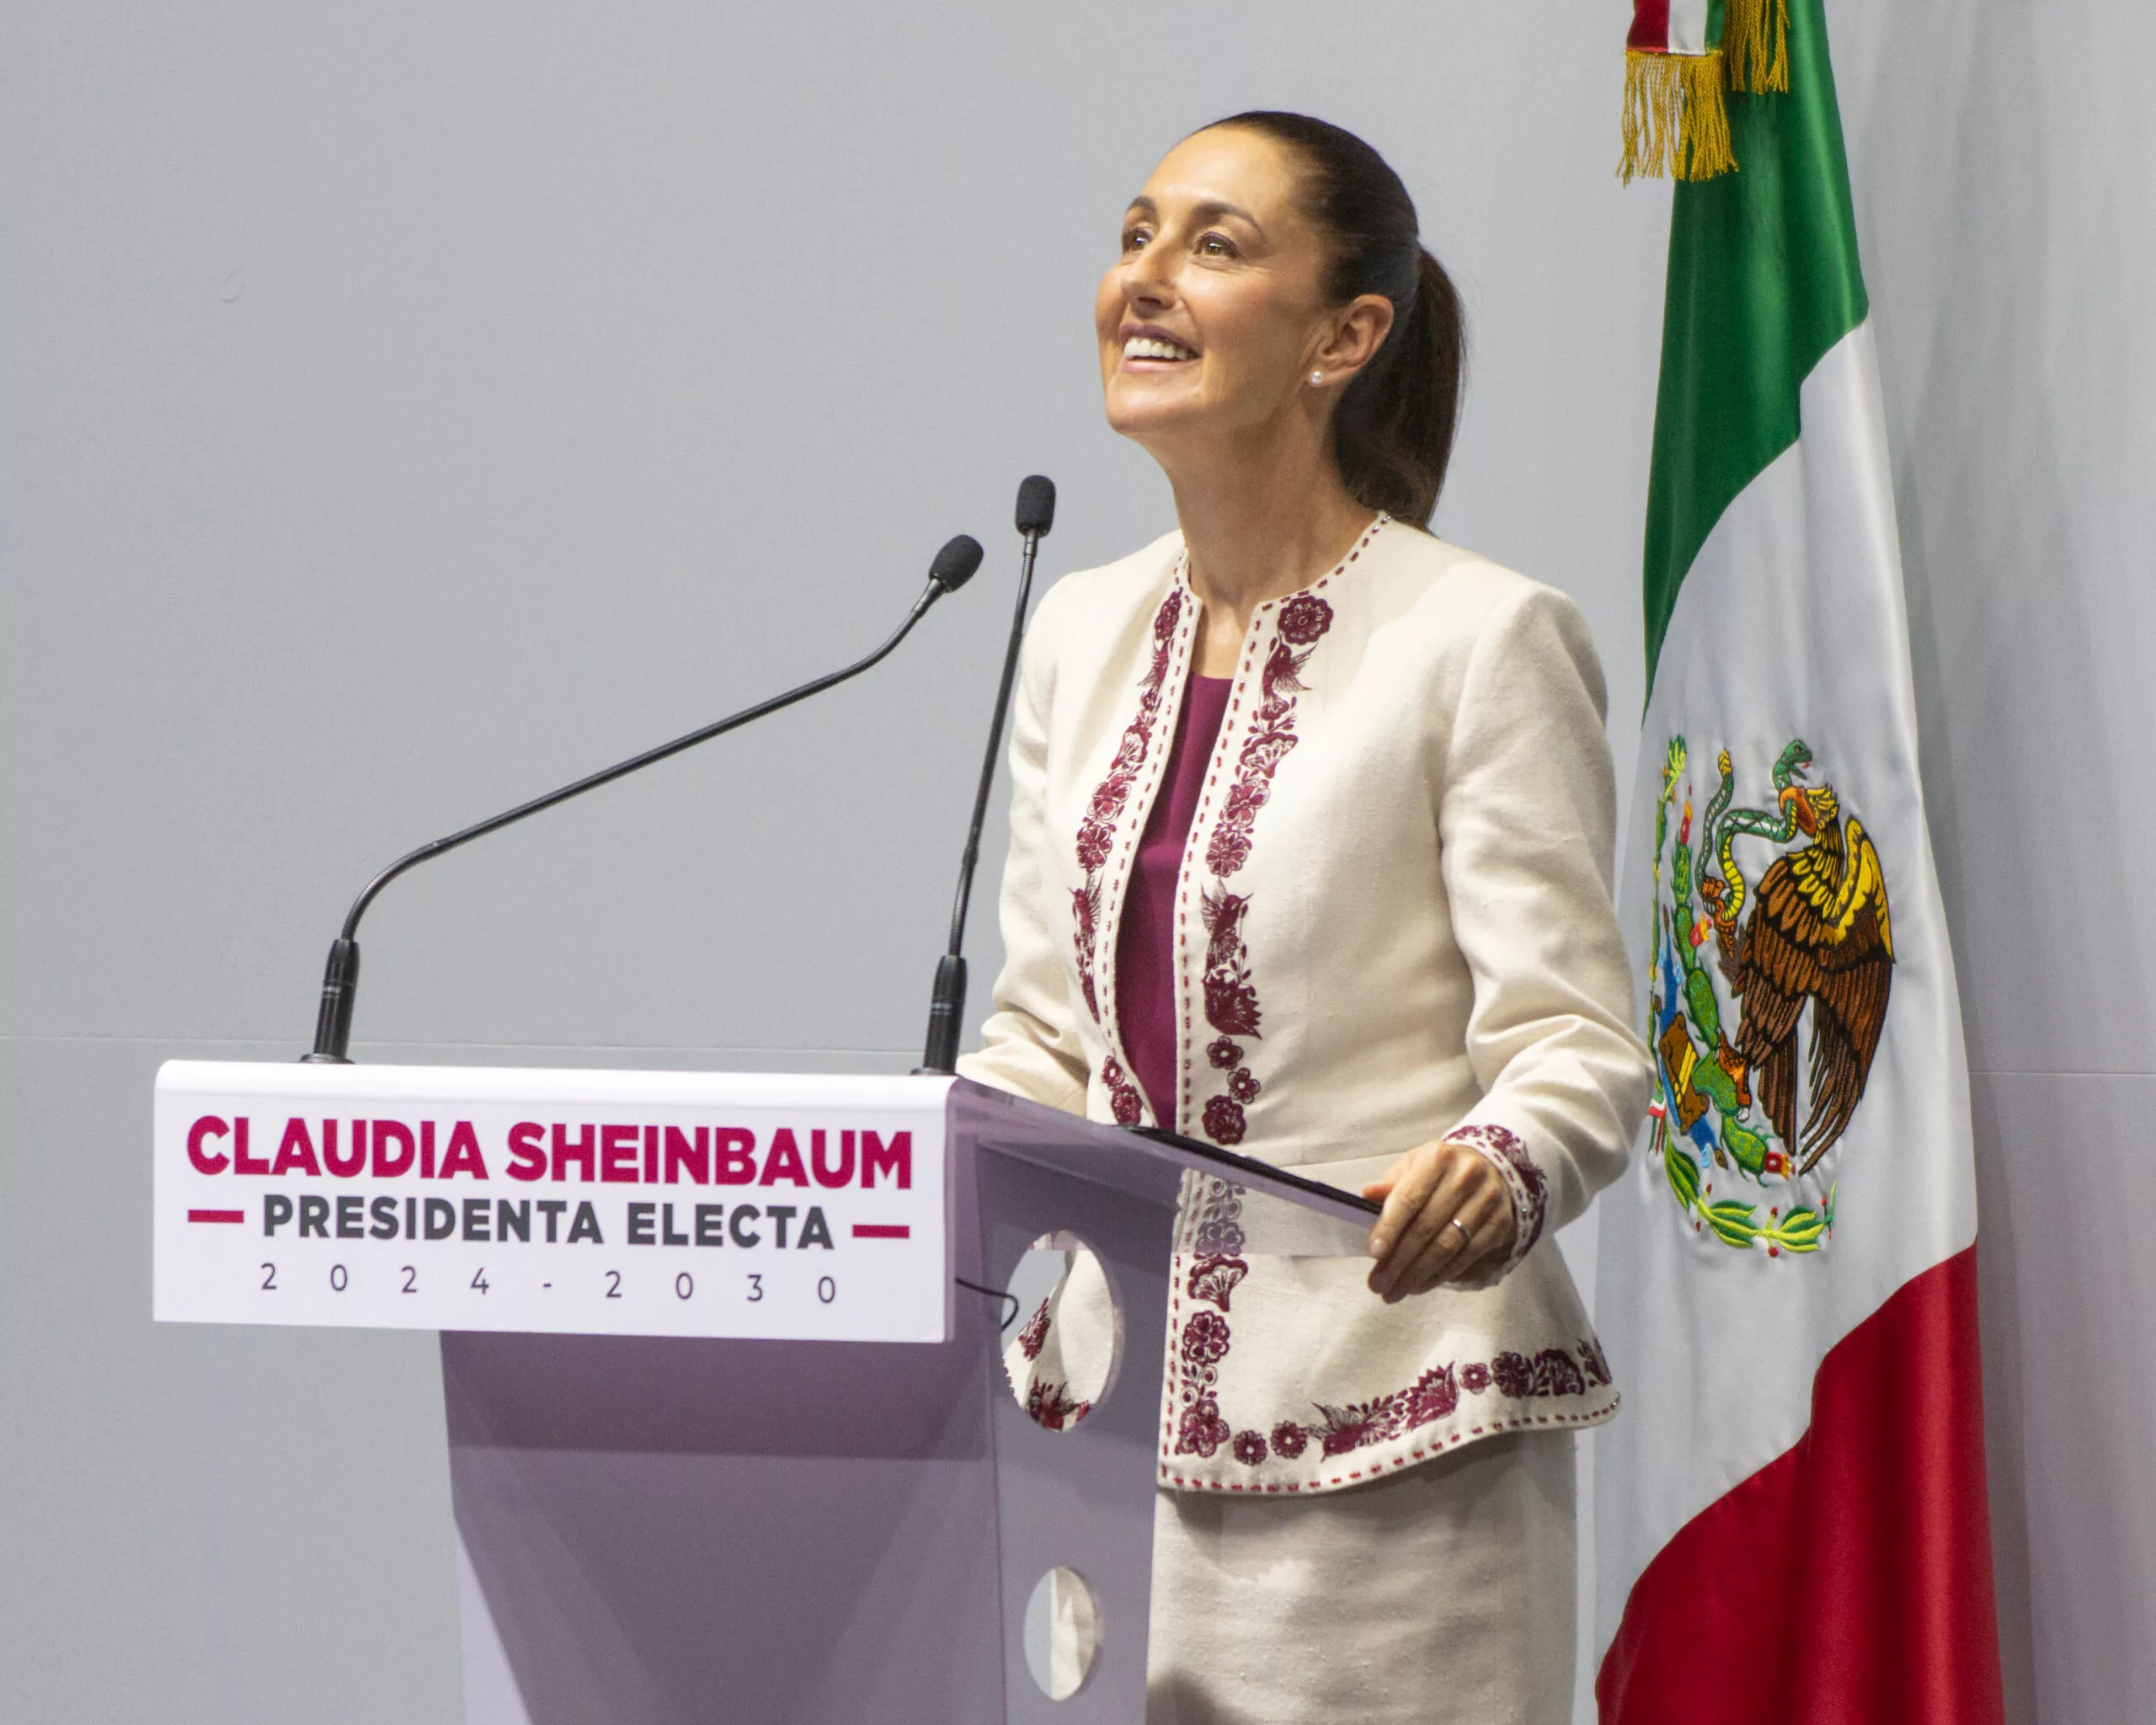
It was presented by Finance Secretary Edgar Amador Zamora, with revenue undersecretary Carlos Lerma and SAT head Antonio Martínez Dagnino. President Claudia Sheinbaum’s framing was unambiguous: there will be no new taxes.
The Framing Argument
Whether a deduction cap is a tax increase is a question of definition rather than of arithmetic. A company that could deduct an expense last year and cannot this year pays more tax. The rate did not change.
The government’s position is that the deductions being closed were being used to reduce liability beyond what the law intended, and that recovering them is enforcement rather than taxation.
That is a defensible reading of the interest limitation in particular, which is the kind of measure OECD members have been adopting for a decade specifically because interest deductibility is the easiest lever for shifting profit out of a jurisdiction.
What the Critics Say
Gustavo de Hoyos Walther, writing in El Financiero, put the objection this way: it has become a habit, the adjustment path is announced, it is not met, and the same path is announced again for the following year.
CIEP argued that isolated increases to the excise regime are temporary patches against a problem that requires a comprehensive restructuring of public finances. Coparmex called for actual compliance with fiscal commitments rather than temporary fixes.
Jorge Cano of México Evalua and Iván Arias of Banamex both warned that rating agencies have flagged slow deficit reduction as a risk to Mexico’s investment grade.
The common thread is not that 140 billion pesos is the wrong number. It is that a revenue measure of this size arrives instead of the structural adjustment that has been promised in successive packages.
How Interest Deductibility Is Used
The mechanism the reform targets is straightforward and entirely legal in most jurisdictions. A multinational lends money from a group entity in a low-tax country to its Mexican subsidiary. The subsidiary deducts the interest against Mexican profits. The interest is received where the tax rate is lower.
Nothing has moved except the internal accounting, and the group’s Mexican tax bill has fallen.
The OECD response was to cap deductible interest at a percentage of earnings before interest, tax, depreciation and amortisation, which is what Mexico’s existing 30 percent limit is. Cutting it to 20 percent tightens the cap.
The countries that have adopted this generally sit in the 20 to 30 percent band, so Mexico is moving to the stricter end of an international norm rather than inventing anything.
Who Actually Pays
The 50 million peso revenue threshold is not high. Plenty of ordinary mid-sized Mexican companies cross it, and they are not running cross-border profit-shifting structures.
A domestic manufacturer that borrowed from a Mexican bank to build a plant deducts that interest for entirely conventional reasons, and a tighter cap raises its tax bill for no policy purpose the reform articulates.
That is the standard objection to interest limitation rules everywhere. They are aimed at multinationals and they catch capital-intensive domestic firms, because both look identical in the tax return.
The exemption for companies under five years old softens the effect for startups. It does nothing for a twenty-year-old family manufacturer financing an expansion.
The Rating Question Underneath
The analyst warnings about investment grade are not rhetorical. Mexico’s sovereign rating sits close enough to the boundary that the deficit trajectory is a live question for the agencies, and Pemex is the other half of the problem.
What agencies have flagged is not the level of debt but the pace of adjustment. Successive budgets have projected consolidation that then did not arrive, and each miss reduces the credibility of the next projection.
That is precisely the point Gustavo de Hoyos Walther made: the path is announced, missed, and announced again.
A 140 billion peso revenue measure is real money. Whether it changes the trajectory depends on what happens to spending, and the pension line alone grows by a comparable amount each year.
More: Mexico news in English, every day from The Rio Times.
Frequently Asked Questions
What is in the 2027 revenue package?
A cap on corporate tax deductions and a cut in the interest-deductibility limit from 30 percent to 20 percent, estimated to yield around 140 billion pesos.
Who does it affect?
Companies with revenue above 50 million pesos. Small and micro businesses and firms under five years old are exempt.
Is it a tax increase?
The government says no, framing it as anti-avoidance. Affected companies will pay more tax without any rate changing.
Why the interest change?
It aligns Mexico with OECD recommendations on base erosion and profit shifting.
What do analysts say?
That the package postpones fiscal adjustment rather than delivering it, with rating agencies already flagging slow deficit reduction.
Sources: La Politica Online, Excélsior, El Financiero, Yahoo Noticias.
This article was drafted with automated assistance and reviewed before publication. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
In depth