Nasdaq Gains 1.1% as US Yields Hold Above 5% | Global Economy, Oct 20
Rio Times Global Economy Briefing
Key Facts
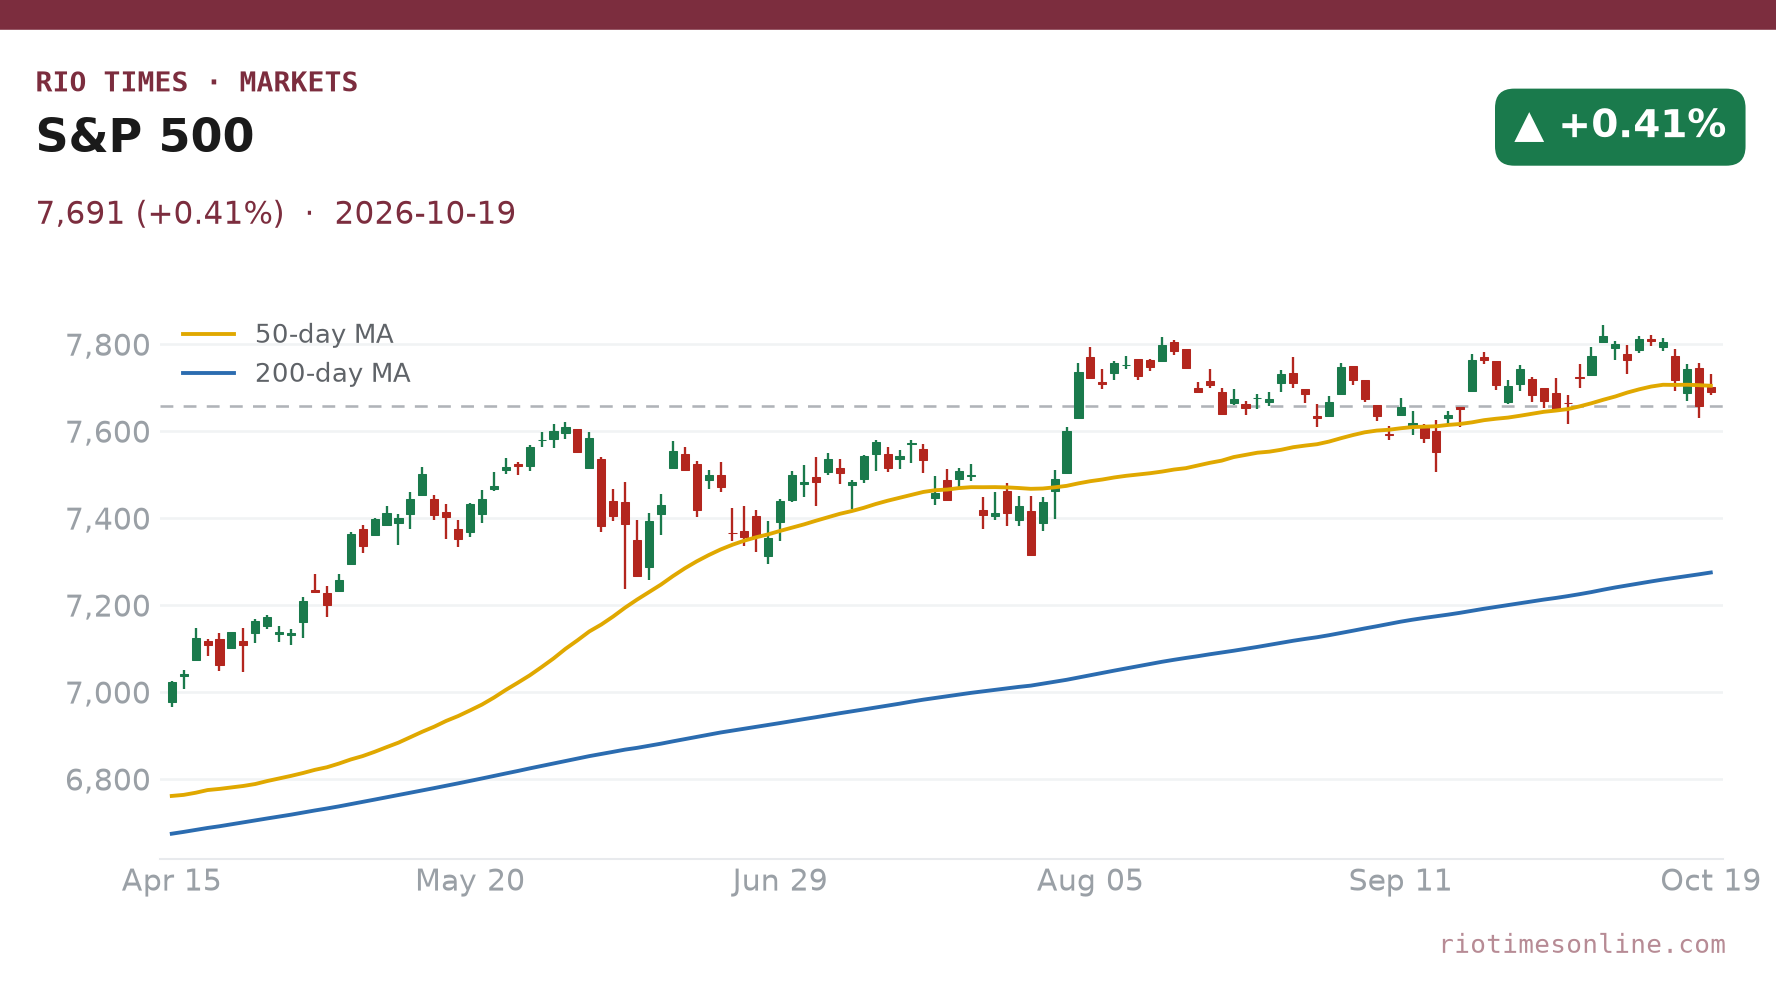
- Wall Street rebounded on Monday with the S&P 500 up 0.41% to 7,691 and the Nasdaq up 1.11% to 26,431, while the Dow slipped 0.07% to 51,966.
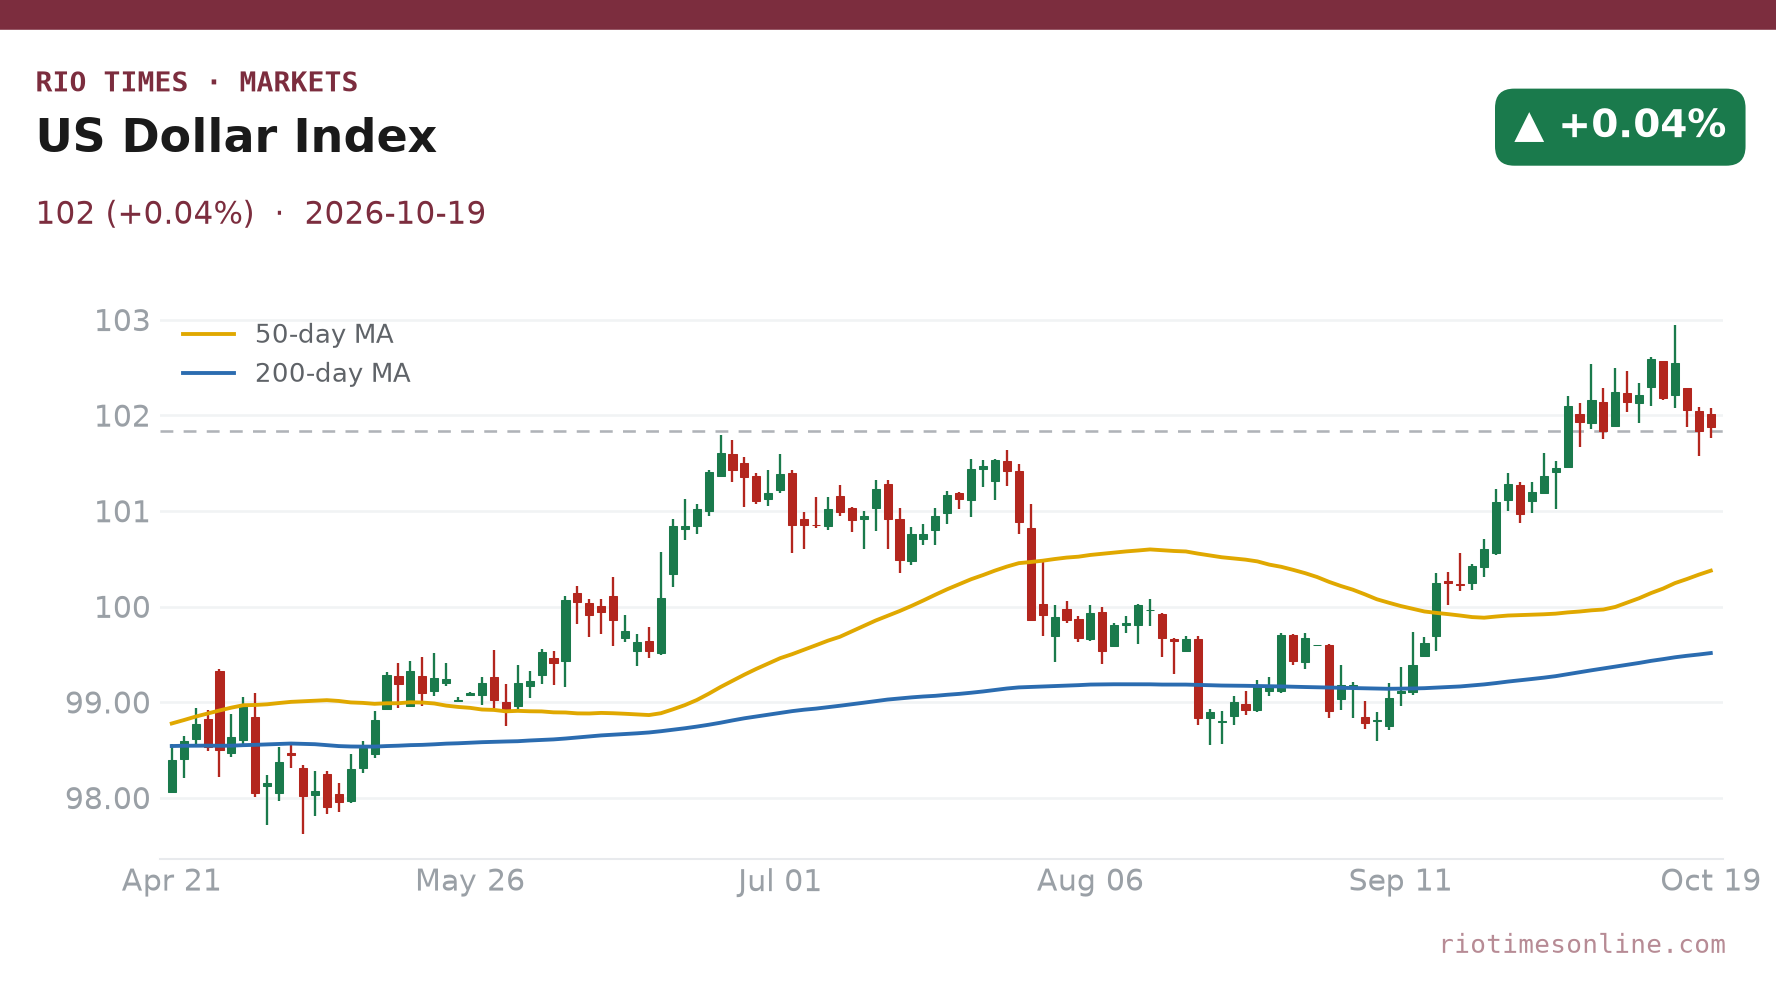
- The dollar index rose 0.11% to 101.946 and the VIX fear gauge fell 7.75% to 18.44.
- The US 10-year Treasury yield stood at 5.139%, about 5 basis points higher on the day.
- China’s third-quarter GDP grew 4.5% year on year against a 4.4% forecast, and Brazil’s IGP-10 inflation index rose 1.8% in October against a 1.4% forecast.
- Prediction markets Polymarket traders put no change at the Fed’s 27–28 October meeting at 85.5% and a 0.25-point rate rise at 14.5%, as of 10:30 p.m. ET on Monday, 19 October.
The Big Three
- Tech lifts as yields stay hot The Nasdaq added 1.11% to 26,431 while the S&P 500 gained 0.41% to 7,691, even with the 10-year yield above 5.1%.
- Fed blackout hands power to the data Officials are silent before the 27–28 October meeting, so housing data and Treasury yields now set the tone for the dollar.
- Brazil’s real waits on fiscal signals A firmer dollar index at 101.946 and a US 10-year yield at 5.139% raise the cost of carry for emerging-market positions.
United States
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| Pending Home Sales (m/m) | due 20 Oct, 10:00 ET | +0.3% | Watch for housing pulse |
| EIA Crude Stocks | due 21 Oct | -8.557m | Oil demand check |
Europe & United Kingdom
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| Bundesbank Nagel Speech | due 21 Oct | — | ECB tone watch |
| UK Unemployment Rate (Aug) | due 20 Oct | 4.9% | Rates-sensitive |
| UK HMRC Payrolls Change (Sep) | due 20 Oct | -26,000 | Rates-sensitive |
| Eurozone flash PMIs | 22 Oct | — | Growth pulse |
Asia-Pacific & Emerging Markets
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| Japan Balance of Trade (Sep) | due 20 Oct, 23:50 UTC | -1,105.6 | Trade momentum |
| Argentina Economic Activity | due 21 Oct | -1.4% | Deep contraction |
| Mexico Retail Sales (y/y) | due 21 Oct | 1.8% | Consumer pulse |
| Colombia Trade Balance | due 21 Oct | — | Import squeeze |
| Instrument | Level | Session |
|---|---|---|
| S&P 500 (US) | 7,691 | +0.41% |
| Ibovespa (Brazil) | 205,079 | -0.17% |
| USD/BRL | 5.0335 | -0.58% |
Source: market close, 19 October 2026.
Today’s Economic Calendar — Tuesday, October 20, 2026
| Time | Country | Event | Consensus | Prior |
|---|---|---|---|---|
| 01:15 | CN | Prime Rate | 3 | 3 |
| 01:15 | CN | Loan Prime Rate 1Y | 3 | 3 |
| 01:15 | CN | Loan Prime Rate 5Y | 3.5 | 3.5 |
| 03:35 | JP | 20-Year JGB Auction | — | 3.856 |
| 06:00 | DE | Producer Price Index | 0.8 | 1.1 |
| 06:00 | DE | Producer Price Index | 5.3 | 4.6 |
| 06:00 | GB | Unemployment Rate (Aug) | 4.9 | 4.9 |
| 06:00 | GB | HMRC Payrolls Change (Sep) | -15 | -26 |
| 09:00 | DE | Economic Sentiment | 30.2 | 34.7 |
| 09:00 | DE | ZEW Current Conditions | -45 | -47.1 |
| 09:00 | DE | ZEW Economic Sentiment Index | 32 | 34.7 |
| 09:30 | DE | Bond Auction | — | 2.49 |
| 09:30 | DE | Bund Auction | — | 3.6 |
| 12:30 | US | Housing Starts | 1.9 | -2.6 |
| 12:30 | US | Housing Starts | 1.31 | 1.275 |
| 12:30 | US | Building Permits | -0.7 | -2.1 |
| 12:30 | US | Building Permits | 1.4 | 1.403 |
| 12:55 | US | Redbook | — | 10.4 |
| 14:00 | US | Pending Home Sales | 1 | -4.7 |
| 14:00 | US | Pending Home Sales | -0.5 | 0.3 |
| 23:50 | JP | Adjusted Trade Balance | -0.21 | -0.84 |
| 23:50 | JP | Balance of Trade (Sep) | -181 | -1105.6 |
Live Market IntelligenceGlobal Markets — Live Board
Rio Times · Live Market Intelligence
Global Markets — Live Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| SPX | 7,751 | +0.29% | — | — | — | — | — |
| NDX | 29,799 | +0.93% | — | — | — | — | — |
| DJI | 53,810 | +0.03% | — | — | — | — | — |
| RUT | 3,041 | +0.46% | — | — | — | — | — |
| US10Y | 4.6760 | -0.17% | — | — | — | — | — |
| VIX | 14.60 | -4.45% | — | — | — | — | — |
| DAX | 26,331 | -0.23% | — | — | — | — | — |
| FTSE | 10,833 | -0.10% | — | — | — | — | — |
| CAC | 8,675 | -0.46% | — | — | — | — | — |
| STOXX | 659.48 | -0.16% | — | — | — | — | — |
| NIKKEI | 67,524 | +0.83% | — | — | — | — | — |
| HSI | 25,440 | -0.83% | — | — | — | — | — |
| KOSPI | 6,579 | +3.68% | — | — | — | — | — |
| CSI300 | 4,691 | +0.58% | — | — | — | — | — |
| NIFTY | 24,436 | -0.15% | — | — | — | — | — |
| TSX | 36,619 | +0.39% | — | — | — | — | — |
| GOLD | 4,461 | +1.78% | +33.20% | 4,383 | 4,503 | 4,421 | 139,824 |
| SILVER | 65.59 | +1.26% | +73.05% | 64.77 | 66.98 | 64.81 | 46,406 |
01 A rebound built on borrowed conviction
The S&P 500 closed at 7,691, up 0.41% after Friday’s fall, as investors shrugged off a 10-year yield parked at 5.139%.
Tech carried the day, with the Nasdaq rising 1.11% to 26,431, while the Dow slipped 0.07% to 51,966. The split shows growth bets are running hot even as the risk-free rate grinds higher.
The dollar index firmed to 101.946 and the VIX fell 7.75% to 18.44. For Latin America, the combination of a strong dollar, high US yields and falling volatility is misleading: it can invite carry trades today and punish them tomorrow.
02 The Fed is quiet, so the bond market speaks
The Federal Reserve is in its blackout before the 27–28 October meeting, leaving housing data and Treasury yields to set the mood.
With the US 10-year at 5.139%, the Treasury market is doing the tightening for the Fed. Pending home sales, due today, will show how quickly activity is cooling.
For Brazil, this is the central tension: the Selic at 13.75% still offers carry, but a 5.14% US Treasury raises the bar for real returns. The real can remain stable only if fiscal signals stay contained before the 25 October runoff.
03 China and the real’s two-way pull
China’s third-quarter GDP growth rate was 4.5% from a year earlier (forecast 4.4%, second quarter 4.3%) and 1.2% on the quarter (forecast 1.1%, previous 0.9%). That supports metals and grains, which Latin American exporters sell to China.
September industrial production rose 5.5% year on year (forecast 5.4%, previous 5.2%) and unemployment stood at 5.2% (forecast 5.3%). Retail sales grew 1.1% (forecast 0.5%), still far slower than industrial output.
Japan reports its September trade balance, adjusted and unadjusted, late on Tuesday (23:50 UTC), and the forecast is a deficit far narrower than August’s. A softer yen would feed the dollar story and keep emerging-market currencies defensive.
In Brazil, the FGV’s IGP-10 inflation index rose 1.8% in October (1.76% before rounding), above the 1.4% forecast and the 1.5% of September. That keeps inflation in focus just as higher Treasury yields make any slippage more expensive.
Stocks rebounded on Monday, but the US 10-year yield held above 5% and the dollar index firmed, so the recovery rests on technology rather than on easier financial conditions. The risk is that yields move higher before the Fed meets on 27–28 October.
The variable to watch is US pending home sales at 10:00 am ET today: a weak print would test the idea that high yields are already cooling housing.
04 What Prediction Markets Say
Traders on Polymarket, a prediction market, put the chance that the Federal Reserve leaves rates unchanged at its 27–28 October meeting at 85.5 percent at 10:30 p.m. ET on Monday, 19 October. They gave 14.5 percent to a 0.25-point rise, and about US$49.9 million had been traded on that market.
The same platform priced a 0.25-point cut at only 0.4 percent. These are bets by traders, not forecasts by the Fed or polls.
Why we show this: prediction markets turn real-money bets into a live probability that moves within minutes of the news, which is why investors, campaigns and newsrooms in the United States now follow them closely. We show them next to polls and official results, never instead of them.
What to watch today and this week
- Tuesday: US pending home sales, UK labour data, Germany’s ZEW survey, Japan’s late trade data and Argentina’s leading indicator.
- Wednesday: EIA oil stocks, UK inflation, Mexico retail sales and Colombia trade data.
- Thursday: Eurozone and UK preliminary PMIs; US preliminary manufacturing and services PMIs.
- Ongoing: Dollar direction, Treasury yields, Brazilian fiscal signals and the 25 October runoff.
Frequently Asked Questions
Why did the Nasdaq rise while the Dow fell?
Investors chased growth and technology names even with the 10-year yield at 5.139%, leaving rate-sensitive industrial and financial shares behind.
Why does the Fed blackout matter?
Officials are not providing guidance before the 27–28 October meeting, so markets rely on data, auctions and yields to set expectations.
What is Brazil’s Selic rate?
The Selic stands at 13.75% following the 0.25-point cut on 16 September, keeping Brazil’s carry trade attractive in local terms.
How do US yields affect Latin America?
Higher US yields and a firm dollar pull capital towards the United States, tightening financial conditions and raising local funding costs.
What should investors watch in Brazil this week?
Fiscal announcements, the real’s stability against the dollar, and positioning ahead of the 25 October runoff.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.