Retire in Brazil: Foreigners Face $2,000 Pension Visa Route
Brazil keeps the retirement visa path tied to a monthly pension transfer, shaping where foreigners can retire in Brazil and how much residence costs.

Guides · Brazil
—The stakes. A Brazilian retirement visa hinges on proving a qualifying pension stream that can be transferred to Brazil each month.
—The threshold. Resolução Normativa CNIg 40 of 2 October 2019 sets the benchmark at a monthly transfer to Brazil of US$2,000 per applicant.
—The mechanism. Applicants show retirement income or a death-pension benefit, with other regular income able to supplement the required amount.
—The residency step. After arrival, retirees register with the Federal Police to obtain the CRNM foreign-resident identity card used for daily formalities.
—The tax reality. Brazilian tax residents generally report worldwide income, including foreign pensions, under progressive personal rates that can reach 27.5 percent.
Brazil remains a retirement destination shaped less by a single national price tag than by visa mechanics, local bureaucracy, and neighbourhood-level choices. The retirement visa route still starts with a pension income benchmark, but the practical cost and comfort of residence depend heavily on city, district, and the retiree’s ability to manage Brazilian formalities.

The VITEM XIV retirement visa mechanism
Brazil’s standard long-stay route for retirees is the consular VITEM XIV visa, a temporary residence path for those receiving retirement income or a death-pension benefit. The operative rule is Resolução Normativa CNIg 40 of 2019, which requires proof of a monthly transfer to Brazil of US$2,000 per applicant. Dependents do not raise the figure. The older formula of R$6,000 (about US$1,180) for a family plus R$2,000 (about US$393) per additional dependent comes from Resolução Normativa 45 of 2000, which RN 40 expressly revoked, and it still circulates on immigration-marketing sites.
The threshold is generally stated in US dollars rather than reais, which matters because the applicant must show a recurring transfer linked to qualifying retirement income. Consular guidance allows other regular sources of income to complement the pension amount if the retiree does not reach the threshold through the pension alone. This means the visa is not purely a passive-income permit; the core basis remains retirement or pension income, with supplementary regular income used to complete the required monthly amount.
How the residence process works after approval
The VITEM XIV route begins abroad through a Brazilian consular post, where the retiree presents documentation supporting the pension and transfer requirement. After entering Brazil, the retiree must formally register with the Federal Police to obtain the foreign-resident identity credential used for routine identification.
That card is commonly referred to as the CRNM, or <em>Carteira de Registro Nacional Migratório</em>, and it is distinct from the earlier visa sticker that allowed entry. The CRNM then becomes the main document for opening accounts, signing housing contracts, and handling other formal interactions inside Brazil.
The CPF tax number as the key to daily life
The CPF, or <em>Cadastro de Pessoas Físicas</em>, is Brazil’s individual taxpayer identification number. It functions as a general identification key for far more than tax returns, including bank accounts, rental agreements, mobile phone plans, and many service registrations.
For a foreign retiree, obtaining a CPF early is essential because most formal transactions and private-sector registrations assume the person already has one. A property purchase is generally tied to the CPF because the buyer needs a formal tax identification record for notary, registry, and tax procedures. Maintaining the CPF as regularised is also important after residence begins, since an irregular taxpayer record can block everyday services even before any annual income filing.
Where retirees actually settle
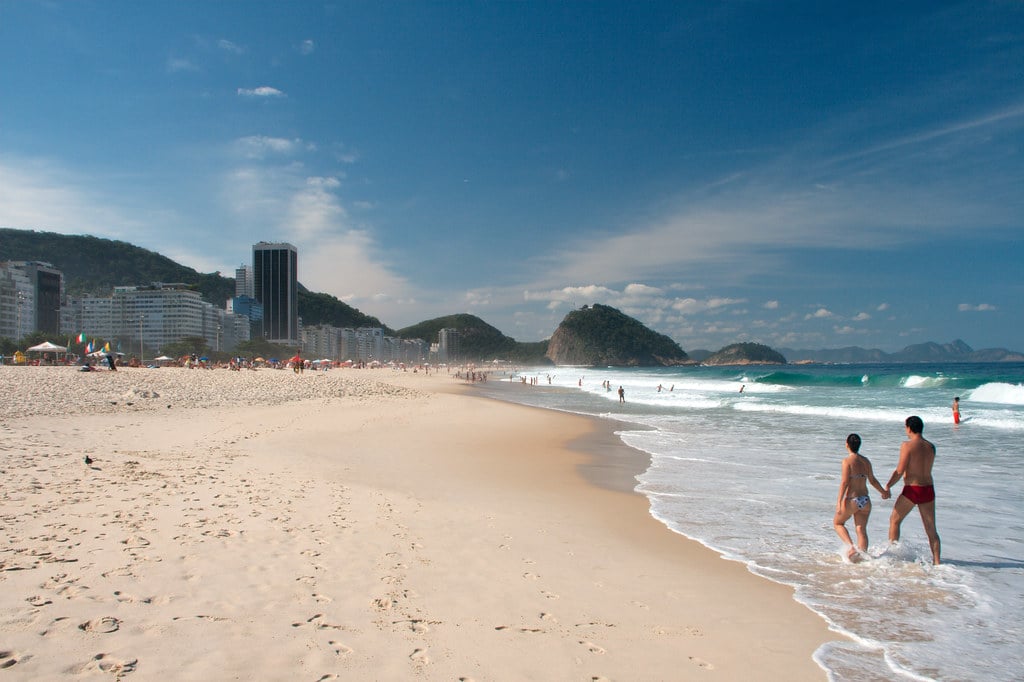
The commonly cited destinations for foreign retirees include Florianópolis, Rio de Janeiro, São Paulo, the Northeast coast, and the southern highlands. Florianópolis is usually framed as a beach-oriented choice with a milder climate and higher prices than many inland cities.
Rio de Janeiro offers the strongest international name recognition and major urban amenities, but safety concerns are highly visible and neighbourhood-specific. São Paulo is valued for services, specialty healthcare, and international connectivity, though it is expensive and less oriented toward a beach retirement lifestyle. The Northeast coast attracts retirees seeking warmer weather and often lower housing costs, while the southern highlands appeal to those wanting a cooler, quieter, more temperate setting.
Cost of living for a retired couple
There is no single authoritative national cost figure for a retired couple in the available official sources, so the useful framing is a range rather than one fixed budget. Living costs vary most by rent, private healthcare, imported goods, and whether the couple chooses a major coastal city or a smaller inland city.
A retired couple in Florianópolis or Rio de Janeiro should expect housing and services to consume more than in many mid-sized interior municipalities. In smaller Northeast coastal towns or highland communities, lower rent can reduce monthly spending, but access to specialty medical care and international goods may involve travel. For planning purposes, the practical approach is to model a city-specific budget that separates housing, health cover, food, transport, and exchange-rate exposure rather than relying on a national average.
Private health insurance for over-60s
Private health plans in Brazil are generally age-rated, meaning premiums rise as the insured person gets older. The regulator that oversees these plans is the ANS, or <em>Agência Nacional de Saúde Suplementar</em>, which sets rules for age bands and pricing structure.
For a retiree over 60, individual or family cover usually carries a materially higher premium than coverage for a younger adult. The safest description is age-banded pricing under ANS oversight, with the final cost depending on the plan, city coverage, network, and the applicant’s age bracket.
Buying property as a retiree
Foreign retirees can generally buy property in Brazil, but the process remains bureaucratic and tied to local registration, identification, and tax steps. A CPF is usually needed for the transaction because the buyer must be identifiable in notary and registry systems and must handle municipal property transfer taxes.
The process typically involves a notary for the purchase instrument and a real estate registry to formalise title, with municipal taxes and fees along the way. Retirees should not assume special property rights or exemptions simply from holding a retirement visa; the general property legal framework applies. Because land and urban property rules can vary by jurisdiction, a local lawyer should verify title, zoning, and any coastal or rural restrictions before payment.

Taxation of foreign pensions under Brazilian residence
Brazilian tax residents are generally taxed on worldwide income, including foreign pension and retirement benefits received while resident in Brazil. Foreign pensions and Social Security-type benefits are normally reported monthly through the <em>Carnê-Leão</em> system and then reconciled in the annual individual income tax return.
Brazil’s normal individual income-tax rates are progressive and can reach 27.5 percent for the highest income bracket. Receita Federal continues to publish an additional monthly exemption of R$1,903.98 (about US$374) on retirement and pension income for taxpayers aged 65 and over, and it applies in 2026 alongside the new general relief.
Tax treaties may change the result for a given foreign pension, so retirees should seek treaty-specific analysis before assuming a foreign tax credit or exclusive taxing right. The single most important change for 2026 is Lei 15.270, sanctioned on 26 November 2025 and in force from 1 January 2026. It effectively exempts monthly taxable income up to R$5,000 (about US$982) through a rebate applied to the existing progressive table, and tapers that relief away between R$5,000 and R$7,350 (about US$982 to US$1,440). Above that the ordinary table governs, still topping out at 27.5 percent.
For a retiree aged 65 or over the two reliefs stack. The general exemption sits on top of the long-standing additional monthly exemption of R$1,903.98 (about US$374) on retirement and pension income for taxpayers in that age group, which Receita Federal continues to publish for 2026.
The same law introduced a minimum tax on high incomes. Residents with annual income above R$600,000 (about US$118,000) face a progressive minimum rising to 10 percent, applied in full above R$1.2 million (about US$236,000), and a 10 percent withholding on dividend distributions above R$50,000 (about US$9,820) a month from a single entity.
A foreign pension is not withheld at source in Brazil, so a resident retiree pays monthly through carnê-leão at the progressive rates, converting at the central bank rate on the day of receipt, and reconciles the year on the annual return. Whether the source country also taxes it depends on the treaty. Brazil has agreements with Portugal, Germany, Japan and France among others, and the outcome is treaty-specific rather than uniform.
Safety considerations by city and neighbourhood
Safety in Brazil varies sharply by city and neighbourhood, so a citywide label is less useful than a district-level assessment. Rio de Janeiro generally carries the strongest safety concern among commonly cited retirement destinations because risk can be highly local and visible.
São Paulo is often more functional for daily infrastructure but still requires careful neighbourhood selection, especially around transport hubs and after dark. Florianópolis is often viewed as safer than the largest metros in many residential areas, though theft and opportunistic crime remain relevant. Northeast coastal towns can feel relaxed in some tourist zones, but safety still varies widely by municipality and the specific area where a retiree lives.
Practical bureaucracy for new retirees
The first bureaucratic sequence is usually CPF, then bank account, then rental or property contract, then local service registrations such as phone and utilities. Without a CPF, many institutions will not open accounts or register housing and mobile services in the retiree’s name.
The Federal Police registration is required to obtain the CRNM, which becomes essential for banking and other formalities in Brazil. Retirees should keep passport, visa page, entry documentation, CPF, proof of address, and CRNM copies together because different public and private offices request different combinations. The overall process is not linear; a single missing document or irregular taxpayer status can block a later step even after the visa itself is approved.
What the retirement visa does not solve
The VITEM XIV route establishes a legal basis for residential stay, but it does not automatically create local credit history or simplify private-sector decisions. Bank accounts may initially be limited until the retiree has a regularised CPF, CRNM, proof of address, and sometimes a minimum deposit or income record.
Healthcare access through private plans will still be priced by age and contract terms, and public health use may depend on registration and local capacity. Tax residence can begin even when the retiree retains foreign assets, so world income reporting and treaty analysis should be planned before arrival. The practical lesson is that the visa is the entry point, while CPF, CRNM, banking, health cover, and tax compliance form the longer chain of residence.
Connected Coverage
Borrowed Logins, a Church Account and Six Bank Directors: What the Vorcaro Files Show
180 Missing Documents: Brazil’s Chief Justice Sets a 24-Hour Banco Master Deadline
The Big Picture
Latest developments
- LatAm Expat & Nomad Daily Guide for Monday, November 2, 2026 — 2 November 2026
- What to Do in Nairobi in November 2026: Fashion Week — 1 November 2026
- What to Do in Lima in November 2026: Taemin, Gorillaz — 1 November 2026
- What to Do in Playa del Carmen in November 2026 — 1 November 2026
This article was produced by The Rio Times’ automated AI newsroom. Editorial responsibility: Matthias Camenzind, Publisher and Editor-in-Chief. The Rio Times also runs Ask Rio Times, which answers from 100,000+ of our own articles, the daily Latin America Power Map, and prediction-market odds on elections and markets.. How we use AI · Report an error
Expat Guide to Brazil
What The Rio Times publishes for foreigners who live in or move to Brazil.
Start here
- Florianópolis Rents by Neighborhood in 2026
- São Paulo Rents by Neighborhood in 2026
- Rio de Janeiro Rents by Neighborhood in 2026
- Brazil Taxes Nomads After 184 Days
City guides
Rio de Janeiro, São Paulo, Florianópolis, Salvador, Belo Horizonte, Fortaleza, Curitiba, Porto Alegre, Brasília
Coming up in Brazil
- Caetano Veloso in São Paulo, 21 November 2026 21 Nov
- Loyle Carner Plays a 1,110-Ticket Club 24 Nov
- Natal em Blumenau 2026: Dates, Parades and Visitor Guide 26 Nov
- Tricky São Paulo Concert on 26 November 26 Nov
Understand Brazil