Brazil’s Morning Call — Thursday, August 27, 2026
Key Facts
- Copom wager remains the anchor the Selic was cut to 14.00% on 5 August, the fourth straight reduction, and B3 options were pricing roughly 95% odds of that cut by the eve of the meeting, so today is about judging how much further easing is already in the price
- Today’s domestic catalyst is labour data the continuous PNAD unemployment rate lands at 9:00 BRT, with the market expecting around 5.3–5.4% against a prior 5.4%, a reading that will shape rate-cut expectations for the next Copom meeting
- The real enters slightly softer but on guard USD/BRL closed at 5.1513, up 0.01% on the session, and traders will use the jobs and current-account numbers to test whether that level holds before the New York open
- Jackson Hole opens today the Fed’s symposium begins in Wyoming, with chair Kevin Warsh speaking on Friday — the same day as US payrolls, Brazil’s Caged jobs report and IGP-M inflation
- Corporate calendar is quiet but not empty no verified earnings or ex-dividend events were captured in the feed, though Habib’s judicial recovery filing, with R$265 million in debts, keeps consumer stress in view
Today’s Focus
The B3 open this Thursday, August 27, is about one question: is the market still comfortable that the central bank, the Copom, will ease again, and at what pace. The Selic, Brazil’s benchmark interest rate, was cut to 14.00% on 5 August, the fourth straight reduction, and B3 options had implied around 95% odds of that move by the eve of the decision. Today’s session is a real-time test of whether that easing story still holds up against fresh data.
The main domestic number is the continuous PNAD unemployment rate at 9:00 BRT. The consensus looks for around 5.3–5.4%, versus 5.4% previously, which would signal a still-resilient labour market. Traders will read it carefully: a hotter-than-expected print could raise the cost of cutting rates as aggressively as some investors hope.
The real finished at 5.1513 to the dollar, down 0.22% on the day, and the early session will show whether that level survives the current-account and foreign-direct-investment figures due at 11:30 BRT. A wider current-account deficit than the expected US$6.6 billion would remind traders that Brazil still runs a structural external gap.
There is no verified corporate earnings or ex-dividend calendar today, which means the open will be driven by macro positioning and rate-sensitive names such as banks, utilities and consumer companies. Globally, the Jackson Hole symposium opens today, with Fed chair Kevin Warsh’s speech and US payrolls both landing on Friday.
What matters today. Today’s B3 open hinges on whether the PNAD jobs data and current-account figures reinforce the market’s generous odds of another Copom rate cut, or force traders to trim those bets.

Today’s Economic Events
| Instrument | Level | Session |
|---|---|---|
| Ibovespa (Brazil) | 174,586 | +0.01% |
| S&P 500 (US) | 7,676 | -0.02% |
| USD/BRL | 5.1513 | +0.22% |
Source: market close, 26 August 2026.
01 The setup in one read
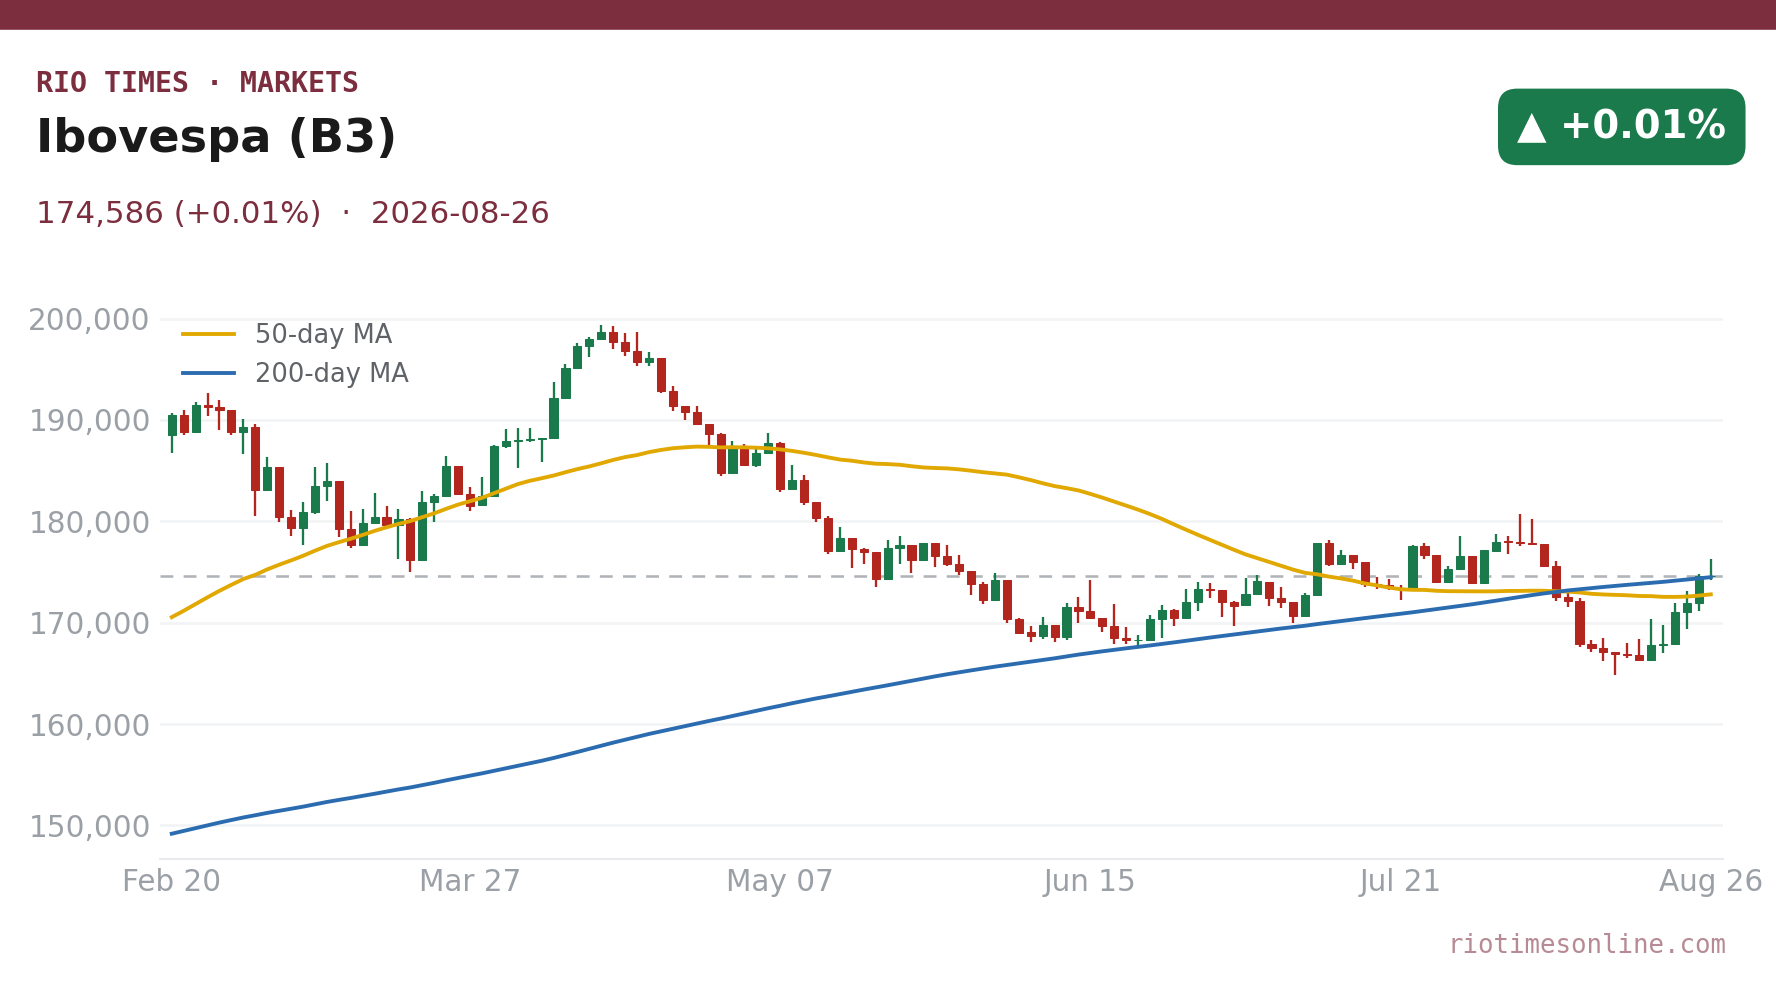
B3, Brazil’s main stock exchange, opens this Thursday with traders focused on the central bank’s next move, not on yesterday’s flat close. The Copom, Brazil’s monetary policy committee, cut the Selic rate to 14.00% on 5 August, and the debate now is whether the economic data still support another cut.
The day’s anchor is the continuous PNAD unemployment survey at 9:00 BRT. Economists expect around 5.3–5.4%, versus 5.4% previously, which would tell the Copom that the labour market remains firm even as rates fall.
The real, Brazil’s currency, begins the session at 5.1513 per dollar after slipping 0.22% on Wednesday. Traders will use the jobs and current-account numbers to decide whether to defend that level or push for a test of the early-August lows near 5.08.
There is no verified corporate earnings or dividend event on the domestic calendar. That absence puts the full weight of today’s open on macro positioning and the rate-sensitive sectors that dominate the Ibovespa, Brazil’s main stock index.
The evidence is mixed but leans cautiously constructive for Brazilian assets. The real has held near 5.15 to the dollar, the Ibovespa has climbed for six straight sessions, and the Copom has now delivered four straight cuts, the latest a unanimous one on 5 August. Options markets were pricing roughly 95% odds of that move by the eve of the meeting, so the question is how much more easing this cycle still has to give.
If the PNAD unemployment rate lands at or below the 5.3–5.4% consensus area, the labour market looks tight enough to keep services inflation sticky, which argues for a more patient Copom. A rising real and falling long-term rates would actually help the stock market, but only if the central bank can ease without reigniting price pressure. The variable to watch is the current-account deficit: a print much wider than US$6.6 billion would dent the real’s carry appeal.
02 Where Brazil is set to open
| Instrument | Last close | Indicated | Watch today |
|---|---|---|---|
| Ibovespa | 174,586 (+0.01%) | — | PNAD jobs, Copom bets, rate-sensitive banks and utilities |
| USD/BRL | 5.1513 (+0.22%) | — | Current account, FDI, Jackson Hole, US dollar tone |
The board shows the real slipping 0.01% to 5.1513 to the dollar, a modest move that signals traders are comfortable holding positions ahead of today’s data. The Ibovespa also ended the prior session flat, but that masks six straight sessions of gains for the index.
For foreign investors using the real as a carry trade, the key test is whether the current-account deficit, expected at US$6.6 billion, stays within the range that makes Brazilian rates attractive. Any surprise widening would raise the cost of holding long-real positions into the weekend. Rio Times · Live Market Intelligence
Live Market IntelligenceBrazil Morning Call — Live Board
Brazil Morning Call — Live Board
Instrument Last Change YoY Prev. High Low Volume
IBOV
205,079.25
-0.17%
+21.85%
205,430.33
168,310
167,142
—
USD/BRL
5.16
+0.01%
-5.13%
5.16
5.18
5.14
—
EUR/BRL
5.95
+1.01%
-5.83%
5.89
5.98
5.94
—
SELIC
14.00%
—
—
—
—
—
BRENT
88.88
-0.03%
+34.42%
88.91
90.07
88.12
29,713
WTI
83.11
-0.11%
+31.57%
83.20
84.35
82.40
166,848
IRON ORE
161.91
—
+58.10%
161.91
161.91
1
GOLD
4,461
+1.78%
+33.20%
4,383
4,503
4,421
139,824
SILVER
65.59
+1.26%
+73.05%
64.77
66.98
64.81
46,406
LITHIUM
75.20
+1.47%
+62.95%
74.11
75.80
75.08
89,275
SOY
1,184
+3.20%
+17.05%
1,148
1,199
1,168
163,179
CORN
480.50
+10.02%
+29.34%
436.75
480.75
459.50
341,248
WHEAT
655.00
+3.93%
+29.70%
630.25
657.75
631.50
128,793
COFFEE
317.25
-5.51%
+0.67%
335.75
321.20
313.55
21,747
SUGAR
16.43
-1.79%
-3.01%
16.73
17.11
16.22
171,992
ORANGE JUICE
138.55
-0.47%
-45.38%
139.20
141.05
137.50
703
COTTON
85.03
+2.33%
+26.78%
83.09
82.90
81.96
16,546
BEEF
223.60
-3.93%
-5.18%
232.75
226.40
223.00
16,126
CATTLE
339.10
-3.16%
-1.82%
350.17
345.50
338.60
10,164
COCOA
5,719
+3.18%
-34.96%
5,543
5,779
5,574
26,773
PETR4
41.64
-0.05%
+35.19%
41.66
41.97
41.15
41,499,400
VALE3
72.97
+0.83%
+30.75%
72.37
73.54
72.66
17,658,000
SUZB3
41.33
+2.35%
-23.55%
40.38
41.48
40.35
3,914,900
KLABIN
17.69
+0.80%
-2.95%
17.55
17.74
17.48
2,057,400
SLCE3
13.34
+0.30%
-12.25%
13.30
13.42
13.20
1,454,200
ABEV3
14.89
-0.80%
+21.91%
15.01
15.07
14.81
16,453,100
ITUB4
38.60
-1.03%
+4.57%
39.00
39.34
38.39
29,487,800
BBDC4
16.85
+0.36%
+3.50%
16.79
16.90
16.67
19,416,900
BBAS3
19.37
+0.47%
+0.73%
19.28
19.44
19.16
11,069,200
B3SA3
14.26
-0.21%
+12.73%
14.29
14.47
14.11
33,037,800
WEGE3
47.59
+0.49%
+29.99%
47.36
48.08
47.36
3,364,600
PRIO3
59.14
-0.19%
+50.67%
59.25
59.81
58.74
3,325,600
RENT3
34.68
-0.09%
+0.84%
34.71
34.96
34.35
7,979,100
AZZA3
15.89
-2.63%
-53.76%
16.32
16.42
15.82
1,330,300
CSNA3
4.30
+0.47%
-42.65%
4.28
4.41
4.26
10,076,100
GGBR4
24.69
+2.19%
+51.38%
24.16
24.85
24.18
7,047,600
ENEV3
24.21
-1.38%
+70.49%
24.55
24.64
23.99
9,297,000
LREN3
11.87
-1.33%
-28.65%
12.03
12.17
11.83
9,683,300
03 On the B3 radar today — labour data and central-bank positioning
| Item | When | Why it matters |
|---|---|---|
| Continuous PNAD unemployment rate | 9:00 BRT | Consensus around 5.3–5.4% vs prior 5.4%; a tight labour market could slow the Copom’s cutting pace |
| Current account | 11:30 BRT | Expected -US$6.6bn; gauges Brazil’s external financing need, a key driver for the real |
| Foreign direct investment | 11:30 BRT | Expected US$7.9bn; shows foreign appetite for long-term Brazilian assets |
| US initial jobless claims | 10:30 BRT | The last labour read before Friday’s payrolls report |
| Jackson Hole symposium opens | All day | Fed chair Kevin Warsh speaks Friday; positioning starts today |
| Corporate events / earnings / ex-dividends | — | No verified items captured in the calendar feed |
The morning is deliberately front-loaded. At 9:00 BRT the PNAD unemployment print lands, and at 11:30 BRT the central bank publishes the current account and foreign direct investment, a burst of data that will set the tone for the afternoon.
Friday then brings the next wave: IGP-M wholesale inflation, the Caged payrolls report — with the market expecting roughly 115,000 new formal jobs — bank-lending figures and fiscal data. US payrolls and the Warsh speech land the same day.
The external accounts are the swing factor for the currency. A current-account gap close to the US$6.6 billion consensus, funded by solid FDI, keeps the real’s carry story intact.
04 Copom and the macro backdrop
The Copom cut the Selic by 0.25 points to 14.00% on 5 August, its fourth straight reduction, and did so unanimously. B3 options were pricing roughly 95% odds of that move by the end of July, which means the decision was largely anticipated.
Today’s question is whether the data flow since that decision still supports further cuts. The PNAD jobs number is the most important domestic input: a print in the 5.3–5.4% area would show that the labour market is absorbing workers without generating runaway wages.
The current-account deficit, expected at US$6.6 billion, is a reminder that Brazil still relies on foreign capital. A wider gap would put pressure on the real and complicate the carry trade that has drawn so much money into Brazilian assets.
Foreign investors are watching the central bank’s communication carefully. The official Copom calendar and the BCB’s Focus survey — which last showed the Selic ending 2026 at 13.75% and the dollar at R$5.20 — remain the authoritative guides for any shift in the rate path.
05 Corporate stories to watch today
There is no verified corporate earnings, dividend or ex-dividend event on today’s B3 calendar. That does not mean the corporate front is lifeless; it means the open will be driven by macro positioning rather than single-stock news.
The most rate-sensitive names are where the action is likely to be. Large private banks such as Itaú Unibanco and Bradesco, the state-controlled Banco do Brasil, and utilities like Sabesp tend to absorb the first wave of any shift in rate expectations.
Commodity-linked exporters, including Vale and Petrobras, remain secondary actors today. Their share prices will track global commodity moves more than any domestic release, and there is no major commodity announcement on the overnight slate.
One domestic corporate story worth holding in mind is the Habib’s restaurant group’s judicial recovery filing, with R$265 million in debts — about US$51 million — accepted by a São Paulo court on Wednesday. It is a vivid symptom of how high real interest rates have squeezed consumer-facing businesses, but it is unlikely to move the index today.
06 The levels to watch at the open
For the real, 5.1513 is the anchor. If the jobs and current-account data come in as expected, the currency could drift back toward the lower end of its recent range, with the early-August low near 5.08 the first target and the May low around 4.89 the longer-term marker for carry traders.
For the Ibovespa, the 52-week high near 198,657 is far in the distance after the index closed at 174,586, roughly 12% below that peak. The more relevant short-term level is whether the index can extend its six-session winning streak despite the lack of fresh corporate catalysts.
A softer-than-expected PNAD number, say 5.2% or below, would likely juice rate-sensitive stocks and pull the index higher. A hotter print, above 5.4%, would do the opposite and could snap the recent rally.
The real’s variable to watch is the current-account deficit. A print much wider than US$6.6 billion would test the market’s patience with Brazil’s external financing needs and could push USD/BRL toward the Focus survey’s year-end call of R$5.20.
07 What to watch
- PNAD unemployment rate at 9:00 BRT: Whether the labour market is cooling enough for the Copom to keep cutting Selic, or tight enough to force patience
- Current account and FDI at 11:30 BRT: Brazil’s external financing gap, in US dollars; a wider deficit could weaken the real and stall the carry trade
- Jackson Hole opens, US jobless claims at 10:30 BRT: Global rate positioning starts today, ahead of Fed chair Kevin Warsh’s Friday speech
- Friday queue: IGP-M wholesale inflation, Caged payrolls, bank lending and fiscal data in Brazil, plus US payrolls
Background: Brazil’s Real Recovers as Forecasters Hold Their Dollar Call.
Background: Grains Wrap: Corn Extends Rally, Soy Rebounds.
More: Brazil news in English, every day from The Rio Times.
Frequently Asked Questions
What is the Selic and why does it matter today?
The Selic is Brazil’s benchmark interest rate, set by the Copom. It was cut to 14.00% on 5 August, and today’s jobs data will influence whether traders keep betting on another cut or start trimming those bets.
What is the PNAD unemployment rate?
It is Brazil’s main labour-market survey, published by the statistics agency IBGE. Economists expect around 5.3–5.4% today, versus 5.4% previously, and it is the single most important domestic data point for rate expectations.
Why is the current account important for the real?
Brazil’s current account measures the gap between what the country earns abroad and what it spends. A larger deficit than the expected US$6.6 billion would mean Brazil needs more foreign financing, which tends to weaken the real.
Are there any big corporate events on B3 today?
No verified earnings, dividend or ex-dividend events were on the calendar at the time of writing. The open will therefore be driven by macro data and rate positioning rather than company-specific news.
Market data: RT
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.