Brazil’s Financial Morning Call for Monday, July 6, 2026
Key Facts
- Selic sits at 14.25%, after a third straight quarter-point cut in June, and the market is now debating whether the Copom delivers again on 5 August or pauses as inflation runs above target.
- Fenabrave auto data lands midday, with new car sales seen at −7% versus a prior +10.6% and production seen at −13% against +6.3%, a sharp swing that reads directly on domestic demand and the rate cycle.
- USD/BRL closed at 5.1686, down 0.66% and a hefty 7.5% below its 52-week high, leaving the real firm within a 4.8909–5.5901 band as carry keeps foreign money engaged.
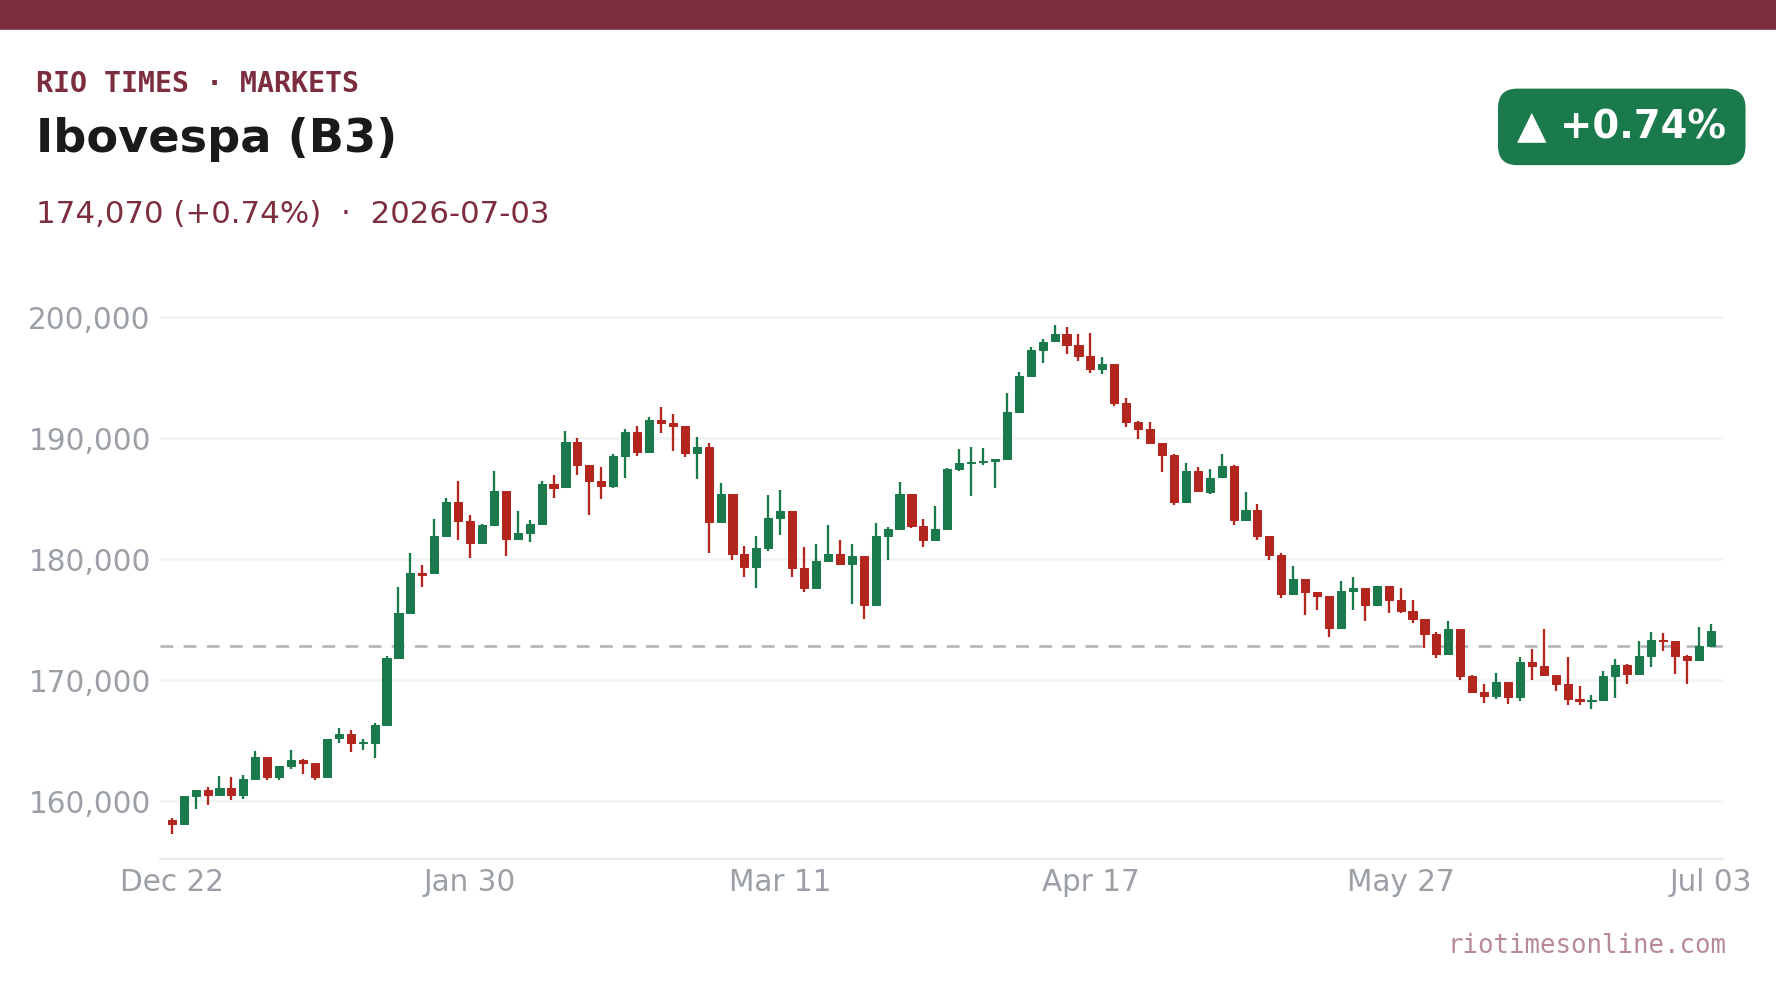
- The Ibovespa enters at 174,070, up 0.74% for a second straight gain but still 12.4% shy of its 198,657 peak, room to run if the auto print and Focus survey cooperate.
- VALE3 led turnover at R$614m, ahead of BPAC11 at R$607m and ITUB4 at R$422m, showing where conviction money is sitting before the bell.
Today’s Focus
Brazil opens the week with the calendar, not the tape, in the driver’s seat — the Focus survey readout, midday auto data and the IGP-DI wholesale print all land before the August Copom meeting comes into view.
The rate debate is finely balanced: the Selic stands at 14.25% after three consecutive quarter-point cuts, but inflation expectations for 2026 sit stubbornly above the 4.5% target ceiling, keeping the easing path slow and data-dependent.
For equities, that means the domestic cyclicals — retail, homebuilders, autos — trade on every downward inflation nudge, while Vale and Petrobras dance to iron ore, Brent and dividend headlines rather than the local curve.
The real remains the release valve: firm at R$5.17 and well off its 52-week weak point, it is doing the heavy lifting on the carry trade even as election-year fiscal noise lurks.
What matters today. Whether the midday auto slump and the Focus survey harden or soften the case for another cut at the 5 August Copom.

01 The setup in one read
Monday is a domestic-data day for B3 — the weekly Focus survey lands mid-morning, the IGP-DI wholesale inflation gauge follows at 11:00, and Fenabrave’s auto sales and production numbers hit around midday.
The through-line is the rate cycle: with the Selic at 14.25% and the next Copom decision due 5 August, every print is filtered through one question — does the central bank cut again or hold as inflation runs hot.
The tape enters with a tailwind, the Ibovespa having posted a second straight gain to 174,070, but the index sits 12.4% below its 52-week high, leaving both room and a reason for caution.
The real, firm at R$5.1686 and 7.5% off its weakest point of the year, is the quiet stabiliser — a strong currency softens imported inflation and keeps the carry trade attractive to foreign desks.
The setup favours a cautious, range-bound open: the Ibovespa carries momentum from two up days but faces a heavy domestic data slate and no clear catalyst to break 175k, while the real’s firmness caps import-cost worries. The variable to watch is the Focus survey’s 2026 IPCA line — another upward revision would stiffen the hawkish case into the August Copom and cap rate-sensitive names.
02 Where Brazil is set to open
| Instrument | Last close | Indicated | Watch today |
|---|---|---|---|
| Ibovespa | 174,070 | Flat to firmer | 175,000 resistance; Focus survey and auto data set the tone |
| USD/BRL | 5.1686 | Steady | R$5.15 support; a break signals stronger carry demand |
| Vale (VALE3) | — | Iron-ore led | R$614m turnover leader; tracks ore and China FX reserves |
| Petrobras (PETR4) | — | Brent-led | Dividend yield near 10%; Brent and payout headlines |
| S&P 500 (context) | 7,483 | — | Flat overnight; US trade data at 12:30 BRT |
The read is a market waiting on its own calendar rather than Wall Street — with the S&P 500 flat at 7,483 and only 1.7% off its high, the external cue is neutral and the domestic data does the work.
Vale’s R$614m turnover crown signals where conviction sits; a firm real and steady ore prices argue for a constructive but unspectacular open around the 174k–175k zone. Rio Times · Live Market Intelligence
Live Market IntelligenceBrazil Morning Call — Live Board
Brazil Morning Call — Live Board
Instrument Last Change YoY Prev. High Low Volume
IBOV
184,853.65
+0.56%
+21.85%
183,827.59
168,310
167,142
—
USD/BRL
5.16
+0.01%
-5.13%
5.16
5.18
5.14
—
EUR/BRL
5.95
+1.01%
-5.83%
5.89
5.98
5.94
—
SELIC
14.00%
—
—
—
—
—
BRENT
88.88
-0.03%
+34.42%
88.91
90.07
88.12
29,713
WTI
83.11
-0.11%
+31.57%
83.20
84.35
82.40
166,848
IRON ORE
161.91
—
+58.10%
161.91
161.91
1
GOLD
4,461
+1.78%
+33.20%
4,383
4,503
4,421
139,824
SILVER
65.59
+1.26%
+73.05%
64.77
66.98
64.81
46,406
LITHIUM
75.20
+1.47%
+62.95%
74.11
75.80
75.08
89,275
SOY
1,184
+3.20%
+17.05%
1,148
1,199
1,168
163,179
CORN
480.50
+10.02%
+29.34%
436.75
480.75
459.50
341,248
WHEAT
655.00
+3.93%
+29.70%
630.25
657.75
631.50
128,793
COFFEE
317.25
-5.51%
+0.67%
335.75
321.20
313.55
21,747
SUGAR
16.43
-1.79%
-3.01%
16.73
17.11
16.22
171,992
ORANGE JUICE
138.55
-0.47%
-45.38%
139.20
141.05
137.50
703
COTTON
85.03
+2.33%
+26.78%
83.09
82.90
81.96
16,546
BEEF
223.60
-3.93%
-5.18%
232.75
226.40
223.00
16,126
CATTLE
339.10
-3.16%
-1.82%
350.17
345.50
338.60
10,164
COCOA
5,719
+3.18%
-34.96%
5,543
5,779
5,574
26,773
PETR4
41.64
-0.05%
+35.19%
41.66
41.97
41.15
41,499,400
VALE3
72.97
+0.83%
+30.75%
72.37
73.54
72.66
17,658,000
SUZB3
41.33
+2.35%
-23.55%
40.38
41.48
40.35
3,914,900
KLABIN
17.69
+0.80%
-2.95%
17.55
17.74
17.48
2,057,400
SLCE3
13.34
+0.30%
-12.25%
13.30
13.42
13.20
1,454,200
ABEV3
14.89
-0.80%
+21.91%
15.01
15.07
14.81
16,453,100
ITUB4
38.60
-1.03%
+4.57%
39.00
39.34
38.39
29,487,800
BBDC4
16.85
+0.36%
+3.50%
16.79
16.90
16.67
19,416,900
BBAS3
19.37
+0.47%
+0.73%
19.28
19.44
19.16
11,069,200
B3SA3
14.26
-0.21%
+12.73%
14.29
14.47
14.11
33,037,800
WEGE3
47.59
+0.49%
+29.99%
47.36
48.08
47.36
3,364,600
PRIO3
59.14
-0.19%
+50.67%
59.25
59.81
58.74
3,325,600
RENT3
34.68
-0.09%
+0.84%
34.71
34.96
34.35
7,979,100
AZZA3
15.89
-2.63%
-53.76%
16.32
16.42
15.82
1,330,300
CSNA3
4.30
+0.47%
-42.65%
4.28
4.41
4.26
10,076,100
GGBR4
24.69
+2.19%
+51.38%
24.16
24.85
24.18
7,047,600
ENEV3
24.21
-1.38%
+70.49%
24.55
24.64
23.99
9,297,000
LREN3
11.87
-1.33%
-28.65%
12.03
12.17
11.83
9,683,300
03 On the B3 radar today — Fenabrave auto data and the Focus survey
| Item | When | Why it matters |
|---|---|---|
| BCB Focus Market Readout | 11:25 BRT | Weekly economist poll; 2026 IPCA and Selic paths feed the August Copom call |
| IGP-DI Inflation | 11:00 BRT | Wholesale price gauge (prev +0.87%); early read on pipeline pressure |
| Fenabrave New Car Sales | 14:00 BRT | Est −7% vs prior +10.6%; direct gauge of domestic demand and credit |
| Fenabrave Car Production | 14:00 BRT | Est −13% vs prior +6.3%; reads on industry and jobs |
| CFTC BRL net positions | 19:30 BRT | Prev 43.7k; tracks foreign speculative appetite for the real |
The Focus readout is the day’s anchor — a fresh upward nudge to the 2026 IPCA median would reinforce the slow-cut narrative and pressure rate-sensitive cyclicals from the open.
The Fenabrave auto figures carry a violent swing in the estimates — a plunge to −7% sales and −13% production from strong prior gains would flag a cooling consumer, ammunition for the doves ahead of August.
04 Copom and the macro backdrop
The Selic sits at 14.25% after the June cut, the third straight quarter-point move in a cautious easing cycle the central bank calls a calibration rather than a dash to lower rates.
The complication is inflation: annual inflation accelerated to 4.72% in May, remaining above the target range, while inflation expectations for 2026 and 2027 stayed elevated at 5.3% and 4.1%, respectively.
The Focus median has crept higher for weeks — the market raised its year-end Selic forecast to 13.50% and 2026 inflation to 5.11% as the energy shock kept price pressure sticky.
With the next decision on 5 August, today’s data feeds a live debate — a soft auto print supports another cut, while a hot Focus reading argues for a pause; the balance is genuinely open.
05 Corporate stories to watch today
Petrobras remains the income anchor of the board — Morningstar data show a dividend yield (trailing) of 10.19%, keeping PETR4 a magnet for yield desks despite political overhang on payout policy.
Vale leads turnover at R$614m and trades on the copper-and-transition-metals story as much as iron ore; Bradesco BBI raised its VALE3 target to R$102 by end-2026, reiterating a buy call.
Among Friday’s movers, ONCO3 spiked +11.9% on thin R$23m turnover and Magazine Luiza (MGLU3) rose +4.2% on R$76m — the retailer is a pure rate-cycle play that lives on every dovish Focus line.
On the downside, ISAE4 slid −4.3% on a heavier R$181m turnover, a reminder that utilities and regulated names swing on the long end of the curve rather than the headline Selic.
06 The levels to watch at the open
For the Ibovespa, 175,000 is the near resistance to clear; a close above it opens the path back toward the 198,657 high, while support sits around Friday’s base near 172,000.
On the currency, R$5.15 is the line in the sand — a break below signals intensifying carry demand for the real, which trades a comfortable 7.5% off its weak point in a 4.8909–5.5901 range.
Watch VALE3 and BPAC11, the twin turnover leaders at R$614m and R$607m, as the market’s tell on whether conviction money is adding or trimming risk before August.
The wildcard is the midday auto data: a print near the −7% and −13% estimates would validate the soft-landing thesis and support rate-sensitive retail and homebuilder names into the bell.
07 What to watch
- Copom 5 August: Whether today’s auto slump and Focus survey tip the balance toward another quarter-point cut or a pause at 14.25%
- The real at R$5.15: A break below support would confirm carry-trade demand and ease imported-inflation worries
- Auto demand: Fenabrave’s sharp estimated drop to −7% sales tests the strength of Brazil’s credit-fuelled consumer
- Turnover leaders: VALE3 and BPAC11 flows signal whether foreign desks are adding or trimming Brazil risk before August
Background: Argentina’s Merval Grinds Higher as Country Risk Sinks to an Eight-Year Low.
More: Brazil news in English, every day from The Rio Times.
Frequently Asked Questions
Where is the Ibovespa indicated to open?
Flat to firmer around 174,070, its second-straight up close, with 175,000 the resistance to clear and the Focus survey and midday auto data setting the tone.
What is the current Selic rate and when does Copom next meet?
The Selic stands at 14.25% after June’s cut; the next Copom decision is 5 August 2026, with the market split between another quarter-point cut and a pause.
Why do the auto data matter today?
Fenabrave sales and production are seen swinging sharply lower (−7% and −13%), a direct read on domestic demand and credit that feeds the rate-cut debate.
What is driving USD/BRL?
The real is firm at R$5.1686, 7.5% off its 52-week weak point, supported by Brazil’s high carry; R$5.15 is the key support to watch.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Read More from The Rio Times