UEMOA Bond Markets Favour States Over Private Companies in 2025
UEMOA · MARKETS
Key Facts
- —What happened States captured 3,507.8 billion CFA francs, or 95.19% of bond mobilisations in the West African Economic and Monetary Union in 2025.
- —How big Private-sector issuers raised 117.1 billion CFA francs, or 3.18%, while regional bodies took 60 billion CFA francs, or 1.63%.
- —The catch Investors prefer sovereign paper because it is seen as safer and more liquid, crowding out corporate bond issues.
- —Who it hits Private companies face a thinner equity market and fewer corporate bond issues across the eight-nation currency union.
- —What comes next The regional legal framework keeps a preference scheme capped at 15% in public procurement directives, reinforcing state dominance.
UEMOA bond markets remain overwhelmingly tilted toward governments, with states taking 95.19% of all bond mobilisations in 2025 while private companies secured just 3.18%. The imbalance reflects investor preference for sovereign paper and a legal framework that privileges public issuers.
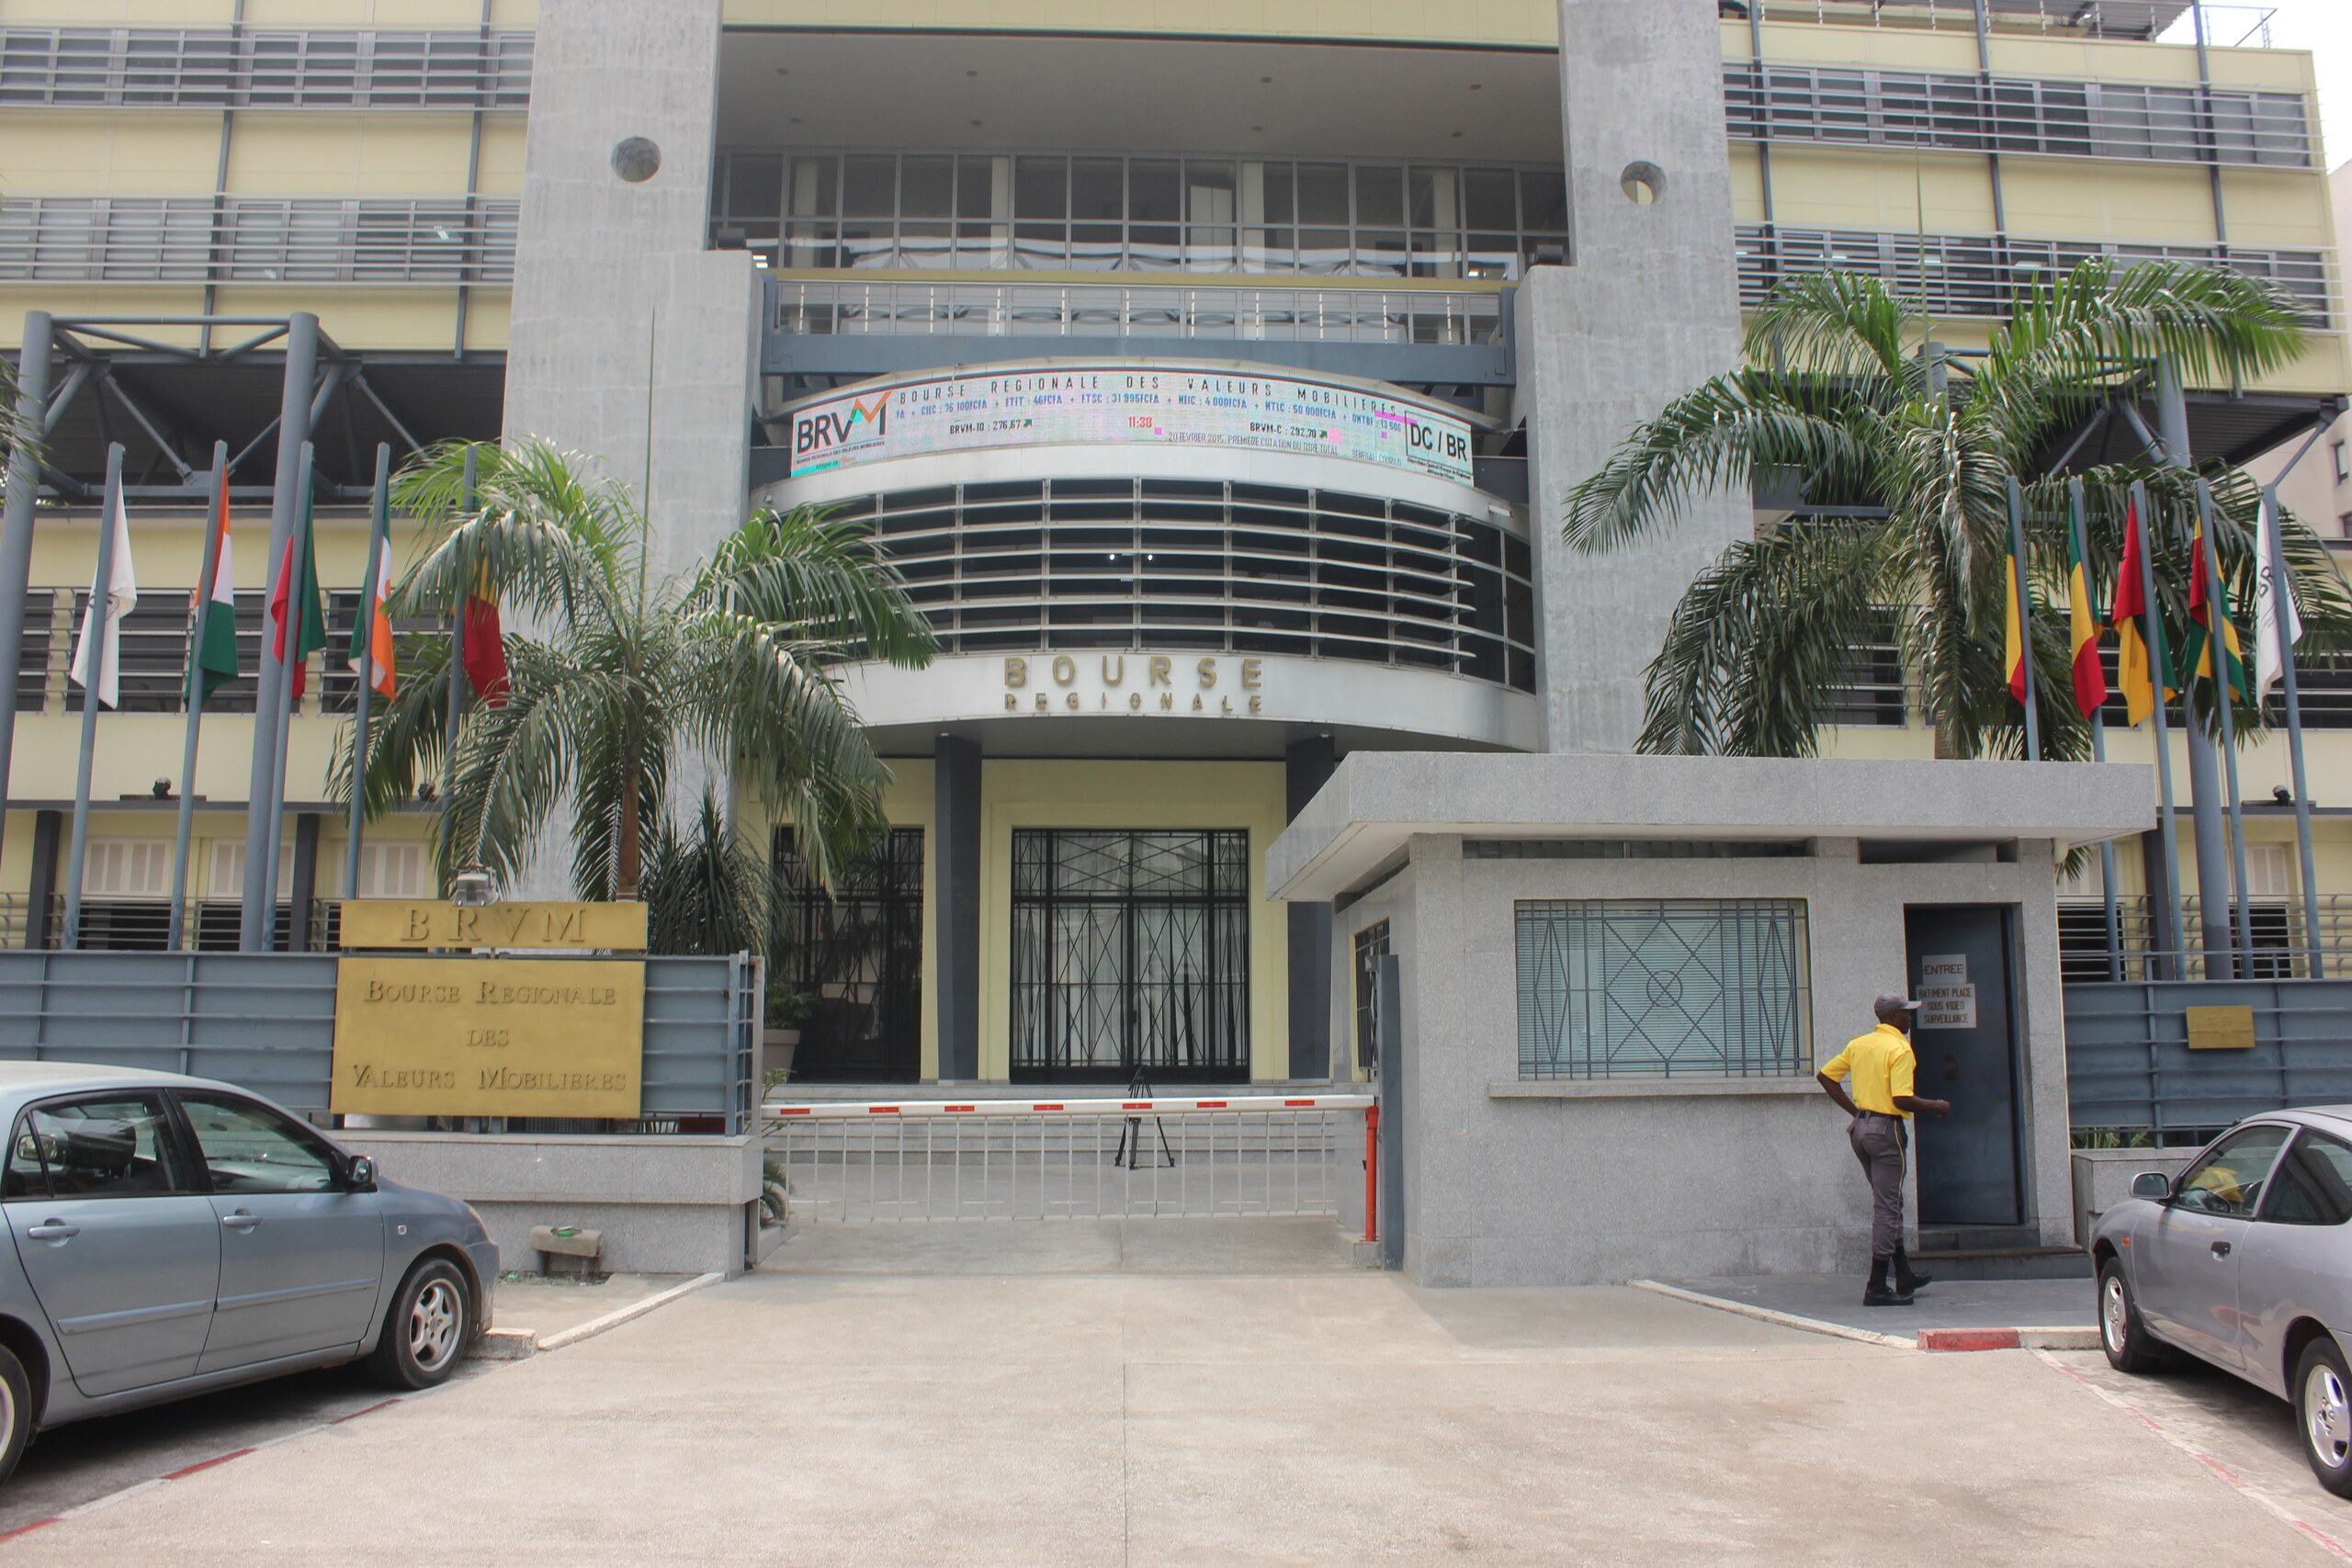
The West African Economic and Monetary Union, known by its French acronym UEMOA, channelled almost all of its bond-market activity toward governments in 2025. States raised 3,507.8 billion CFA francs, leaving private companies and regional bodies with only a sliver of the total.
The numbers behind the sovereign tilt
In 2025, states captured 3,507.8 billion CFA francs, or 95.19% of obligational mobilisations across the eight-nation currency union. Private-sector issuers raised 117.1 billion CFA francs, representing 3.18% of the total.
Regional bodies accounted for 60 billion CFA francs, or 1.63%. The figures come from regional market data compiled on the UEMOA bond market and reported by AllAfrica in March 2026.
The longer stock of outstanding bonds tells the same story. States held 19,504 billion CFA francs, or 87.3% of the total, compared with 1,206 billion CFA francs, or 5.4%, for private-sector issuers.
Private companies alone held just 264 billion CFA francs, or 1.2% of outstanding bonds. The gap between new mobilisations and the existing stock shows the trend is deepening rather than narrowing.
Why investors prefer sovereign paper
The crowding-out effect is not accidental. Investors and banks in the region view sovereign bonds as safer and more liquid than corporate debt.
Private issuers face a thinner equity market and fewer corporate bond issues, which makes it harder for them to compete for capital. The result is a self-reinforcing cycle where governments borrow routinely while companies struggle to access the same pool of funds.
The Central Bank of West African States, known as BCEAO, and the regional market infrastructure make sovereign borrowing routine and predictable. This strengthens the fiscal and political centrality of governments across the union.
For companies, the path to bond-market financing remains narrow. The preference for state paper leaves little room for corporate issuers to build a track record that might attract investors over time.
A legal framework that favours the state
The regional market’s legal framework also privileges public procurement and community firms. UEMOA directives include a preference scheme capped at 15% for public contracts.
This preference scheme, documented in UEMOA Directive 2005-04 on the execution of public procurement, gives domestic and community firms an edge in winning state contracts. The cap is meant to balance regional integration with local protection.
In practice, the scheme reinforces the position of governments as the dominant economic actors. Private companies must navigate a system where the state is both the main borrower and the main buyer of goods and services.
The African Development Bank has supported UEMOA private-sector competitiveness, but that support remains small compared with state-dominated domestic funding channels. External financing competition has not shifted the internal balance.
The wider money-power picture
UEMOA states finance themselves heavily through the regional market, which deepens their fiscal and political centrality. The bond market is not just a funding tool; it is a mechanism of power.
When governments borrow routinely and predictably, they become the anchor of the financial system. Banks and investors build their portfolios around sovereign paper, and the private sector is left to find capital elsewhere.
This dynamic matters for the broader West African region. The eight UEMOA member states share the CFA franc and a common central bank, which makes their bond market a key test of regional integration.
The pattern also echoes wider trends across frontier markets, where state borrowing often crowds out private investment. For readers following the competition for capital and influence, the UEMOA story fits the larger picture covered in Africa: The New Scramble.
What to watch next
The key question is whether private issuers can break the cycle. A deeper corporate bond market would require investors to accept more risk and companies to build stronger balance sheets.
Regulatory changes could help, but the preference scheme capped at 15% in UEMOA directives suggests that governments are not rushing to level the playing field. The legal framework remains tilted toward public issuers.
For now, the numbers point in one direction. States dominate new bond mobilisations, and the outstanding stock of debt is even more concentrated in sovereign hands.
Investors, professionals and companies watching the region should track whether private-sector mobilisations rise above the 3.18% share recorded in 2025. Any shift would signal a meaningful change in how capital flows through the UEMOA bond market.
Frequently Asked Questions
What share of UEMOA bond mobilisations went to states in 2025?
States captured 3,507.8 billion CFA francs, or 95.19% of bond mobilisations in the West African Economic and Monetary Union in 2025.
Why do investors prefer sovereign bonds over private company bonds in UEMOA?
Investors and banks see sovereign paper as safer and more liquid, while private issuers face a thinner equity market and fewer corporate bond issues.
How much did private companies raise in the UEMOA bond market in 2025?
Private-sector issuers raised 117.1 billion CFA francs, or 3.18% of total bond mobilisations, while private companies held 264 billion CFA francs, or 1.2%, of outstanding bonds.
Connected Coverage
Sources
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Read More from The Rio Times