Global Economy Briefing — July 1, 2026
Chipmakers drove the Nasdaq up 1.5% and the Dow to a third record as Wall Street closed its best quarter since 2020; Colombia surprised with a rate hike.
Rio Times Global Economy Briefing
The Big Three
- Chipmakers powered a second day of gains. The Nasdaq rose 1.5% and the Dow set a third consecutive record as Nvidia added 2.6%, AMD jumped 7.7% and Intel climbed 6%, with investors looking past worries about lofty AI valuations.
- Wall Street closed its strongest quarter since 2020. Over the three months, the S&P 500 rose about 14%, the Nasdaq roughly 20% and the Dow more than 12% — a remarkable rebound given the year’s oil shock and hawkish Fed.
- Colombia surprised with a bigger rate hike. The central bank raised its benchmark more than expected, underscoring how much harder the inflation battle remains across parts of Latin America.
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| Dow Jones (close) | 52,319.20 | 52,182.74 | Record |
| S&P 500 (close) | 7,499.36 | 7,440.43 | +0.79% |
| Nasdaq (close) | 26,213.72 | 25,820.15 | +1.52% |
| JOLTS Job Openings (May) | 7.594M | 7.585M | Beat |
| CB Consumer Confidence (Jun) | 91.2 | 90.6 | Below hopes |
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| German CPI (YoY, Jun) | 2.3% | 2.6% | Cooler |
| French CPI (YoY, Jun) | 1.8% | 2.4% | Sharp cool |
| Italian CPI (YoY, Jun) | 3.0% | 3.2% | Easing |
| German Retail Sales (YoY, May) | 1.8% | −0.6% | Strong beat |
| UK GDP (QoQ, Q1) | 0.6% | 0.1% | Accelerating |
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| Colombia rate decision (Jun) | — | — | Hawkish surprise |
| China Caixin Manufacturing PMI (Jun) | 51.7 | 51.8 | Expanding |
| South Korea Exports (YoY, Jun) | 70.9% | 53.4% | Surge |
| Japan Tankan (large manufacturers, Q2) | 22 | 17 | Beat |
| Brazil CAGED Jobs (May) | 72.96K | 85.89K | Missed |
Live Market IntelligenceGlobal Markets — Live Board
Rio Times · Live Market Intelligence
Global Markets — Live Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| SPX | 7,751 | +0.29% | — | — | — | — | — |
| NDX | 29,799 | +0.93% | — | — | — | — | — |
| DJI | 53,810 | +0.03% | — | — | — | — | — |
| RUT | 3,041 | +0.46% | — | — | — | — | — |
| US10Y | 4.6760 | -0.17% | — | — | — | — | — |
| VIX | 14.60 | -4.45% | — | — | — | — | — |
| DAX | 26,331 | -0.23% | — | — | — | — | — |
| FTSE | 10,833 | -0.10% | — | — | — | — | — |
| CAC | 8,675 | -0.46% | — | — | — | — | — |
| STOXX | 659.48 | -0.16% | — | — | — | — | — |
| NIKKEI | 67,524 | +0.83% | — | — | — | — | — |
| HSI | 25,440 | -0.83% | — | — | — | — | — |
| KOSPI | 6,579 | +3.68% | — | — | — | — | — |
| CSI300 | 4,691 | +0.58% | — | — | — | — | — |
| NIFTY | 24,436 | -0.15% | — | — | — | — | — |
| TSX | 36,619 | +0.39% | — | — | — | — | — |
| GOLD | 4,461 | +1.78% | +33.20% | 4,383 | 4,503 | 4,421 | 139,824 |
| SILVER | 65.59 | +1.26% | +73.05% | 64.77 | 66.98 | 64.81 | 46,406 |
01 The chips lead, and Wall Street shuts a banner quarter
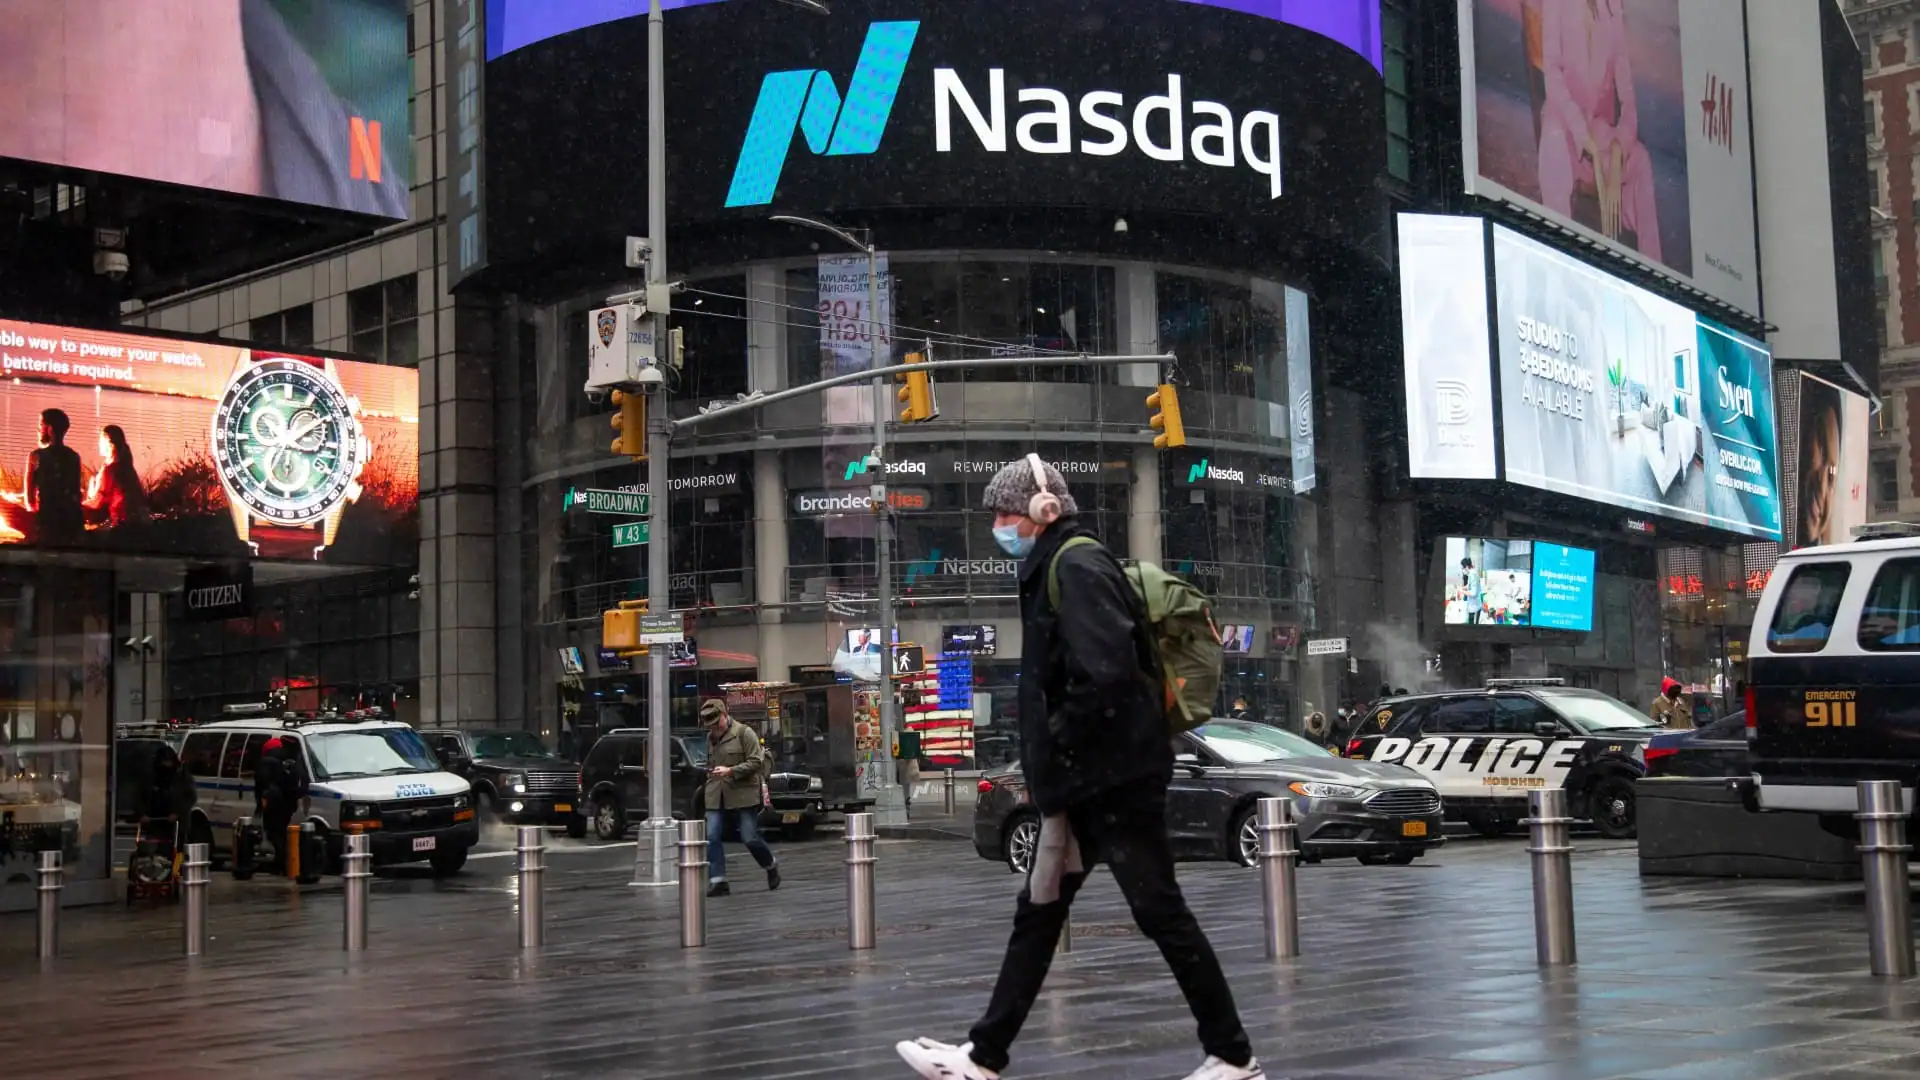
The rebound in technology stocks that began the week gathered force on Tuesday, and this time the semiconductor makers led it. Nvidia rose 2.6%, AMD leapt 7.7% and Intel added 6%, as investors set aside their recent fears that artificial-intelligence shares had simply grown too expensive.
The Nasdaq climbed 1.5% and the S&P 500 gained 0.8%, while the Dow edged up to a third record close in a row. The gains carried a milestone with them: the quarter that ended on Tuesday was Wall Street’s best since the recovery of 2020, with the S&P 500 up roughly 14% over three months and the Nasdaq up about 20%.
The reason investors could enjoy the rally is the same reason it has held together — oil. With crude still near its pre-conflict lows, the fear that the Federal Reserve might be forced into an aggressive round of rate increases has faded, and that alone has been enough to let the technology trade breathe again. Yet the rally’s foundation remains fragile: the IMF has cautioned that the war shock and a repricing of risk still threaten the global outlook, and the ECB raised rates to 2.25% in June, signaling it will stay restrictive as the Middle East conflict fans fresh inflation pressures across the euro area.
02 Colombia hikes, and the two Latin Americas come into view
While Wall Street celebrated, Colombia’s central bank delivered a jolt. It raised its benchmark rate by a larger step than markets had penciled in, a clear signal that policymakers there still see inflation as the enemy rather than a problem already solved. The move aligns with the IMF’s recent warning that global disinflation has stalled, with the war shock and a repricing of risk remaining key threats to the 3.0% growth outlook for 2026.
It is a very different posture from Brazil’s, where the central bank began cutting rates this month.
That contrast is the story worth watching. Latin America is not moving as one bloc: some central banks are easing as inflation cools, while others are still tightening because it has not.
The dividing line is largely about credibility and the path of prices at home, and Colombia’s surprise is a reminder that the region’s disinflation is uneven and far from finished.
For Brazil, the read-through is reassuring but comes with a caveat. Cheaper oil and cooling inflation have let Brasília start lowering the Selic from 14.25% while much of the neighborhood tightens, which speaks well of its position. But Tuesday also brought a weaker signal from Brazil’s own fiscal accounts — the primary budget balance deteriorated and gross public debt climbed to 81.1% of output. A confident central bank still has to answer to a government that is spending more than it collects, and that tension is the quiet limit on how far and how fast Brazil can ease.
03 The paradox: a record quarter that its own leaders sat out
Here is the curiosity in the numbers. The quarter that just closed was the best in six years, yet for most of June the market’s biggest names — the megacap technology stocks that usually drive it — went nowhere, and at times fell hard.
The quarter was made in its final days, by a late burst in the very shares that had been sitting on their hands.
One seasoned market watcher put the doubt plainly: a bounce powered by short-covering and end-of-quarter positioning in the most beaten-down stocks is not the same as a market in robust health. The names that rescued the quarter were the ones that had spent it as laggards.
Which leaves an honest question hanging over the celebration. A banner quarter that leaned on a two-day sprint at the finish is a triumph on paper, but whether it becomes a durable trend depends entirely on what happens next — and the next few sessions, thin and holiday-shortened, may not settle it.
What to watch today and this week
- Wednesday: Fed Chair Kevin Warsh speaks at the ECB’s Sintra forum alongside Lagarde, Bailey and Macklem — his first appearance abroad and a rare chance to read his intentions on rates.
- Wednesday: A wave of US data — ADP private payrolls, ISM manufacturing and job-cut figures — sets the stage before the main event.
- Thursday: The June jobs report arrives a day early because of the holiday; a strong number would revive talk of a Fed rate hike.
- Friday: US stock and bond markets are closed for Independence Day; expect quiet, early trading around it.
- This week: Whether the chip-led rally broadens into the rest of the market or fades once quarter-end buying is done.
Frequently Asked Questions
Why did chip stocks rise so sharply?
Semiconductor companies had been among the hardest hit during the recent worry that artificial-intelligence shares had climbed too far, too fast. On Tuesday, investors reversed that judgment, encouraged by upbeat guidance from chipmakers even as the big cloud companies keep spending heavily. Because chips sit at the center of the AI story, a rebound in names like Nvidia and AMD tends to pull the whole technology-heavy Nasdaq up with them.
Why does Colombia raising rates matter to Brazil?
It highlights that Latin America is not moving in step. Colombia is still raising rates to fight inflation, while Brazil has begun cutting — a sign that Brazil’s inflation has cooled enough to allow it, thanks partly to cheaper oil.
For investors, the contrast is a useful reminder to judge each country on its own inflation and its own credibility, rather than treating the region as a single trade.
What made this quarter the best since 2020?
A combination of relief and momentum. Oil prices fell back to where they sat before this year’s Middle East conflict, easing fears of runaway inflation and aggressive Fed rate hikes.
That let investors return to the technology and AI shares that dominate the indexes. The result was gains of roughly 14% for the S&P 500 and about 20% for the Nasdaq over three months — an unusually strong run.
Why is Brazil’s budget data a concern if inflation is cooling?
Because interest rates are only half the picture. Brazil’s central bank can lower the Selic as inflation eases, but if the government keeps spending more than it raises in taxes, its debt grows — and rising debt can eventually push borrowing costs back up and weaken the currency.
Tuesday’s figures showed the budget balance worsening and public debt climbing, which sets a practical limit on how far the central bank can comfortably cut.
Why is everyone watching Fed Chair Warsh’s speech in Portugal?
Because he has deliberately stopped offering the detailed guidance markets were used to, so investors now parse his tone for clues. Wednesday’s panel in Sintra is his first public appearance outside the United States since taking over and since his hawkish debut meeting in June.
Any hint about whether the Fed’s next move is a hike could move the dollar, bond yields and, by extension, emerging-market currencies like the real.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.