Brazil’s Q1 2025 Fiscal Numbers Looked Strong on Paper, but Delayed Payments Cloud Outlook
Brazil’s Central Bank reported a first-quarter 2025 primary surplus of 54.5 billion reais ($9.73 billion), more than double the 20.2 billion reais ($3.61...
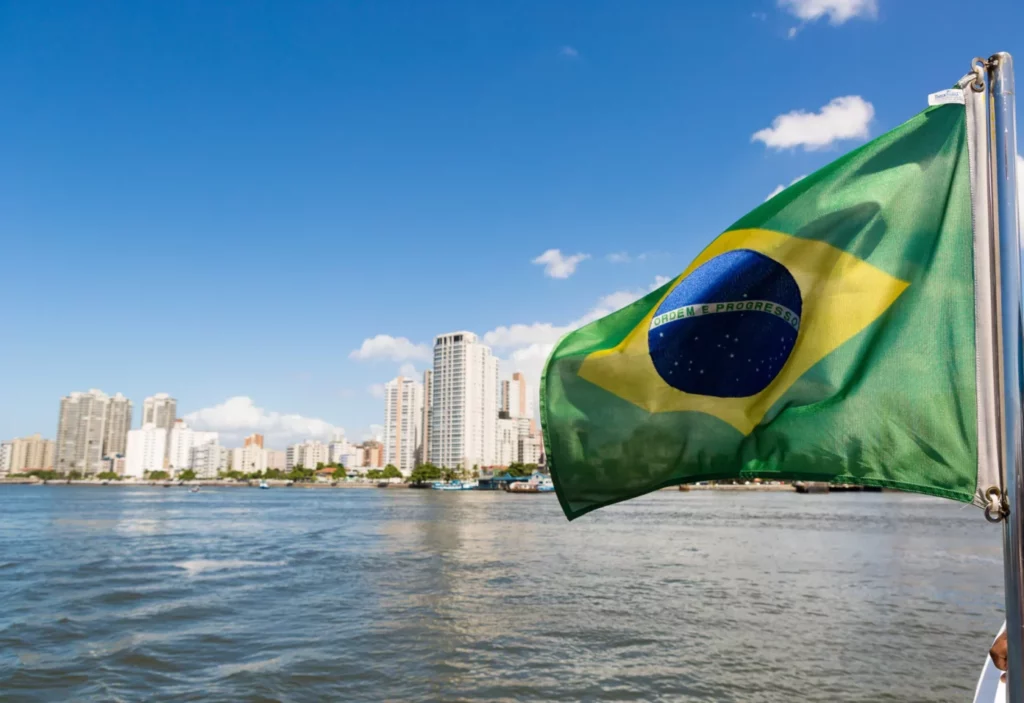
Brazil’s Central Bank reported a first-quarter 2025 primary surplus of 54.5 billion reais ($9.73 billion), more than double the 20.2 billion reais ($3.61 billion) surplus from the same period in 2024.
The government achieved this result by delaying 31 billion reais ($5.54 billion) in court-ordered payments, a move that shifted these expenses to July. Treasury Secretary Rogerio Ceron described this as a strategy to prevent fiscal expansion early in the year and to support efforts to slow inflation.
In March, the central government posted a primary surplus of 1.1 billion reais ($0.2 billion), slightly below market expectations. Still, the quarter’s numbers looked strong on paper.
The timing of court-mandated payments explains much of the improvement, not a fundamental shift in Brazil’s fiscal position. Most of these payments occurred in February last year, but this year’s schedule pushed them later, flattening early-year spending.
Brazil’s gross debt-to-GDP ratio fell to 75.9% in March from 76.2% in February. This drop resulted from a mix of nominal GDP changes, net debt redemptions, and exchange rate effects.
The country’s gross debt averaged 76.1% of GDP over the last decade, peaking at 90.7% in 2020 and bottoming at 61.7% in 2015. Analysts expect the debt ratio to rise again, reaching 78% in 2026 and 80% in 2027.
Brazil’s Fiscal Strain
Despite the primary surplus, Brazil’s nominal budget deficit in March reached 71.6 billion reais ($12.79 billion), higher than the 63 billion reais ($11.25 billion) deficit in March 2024.
The central government and state-owned companies both posted deficits, while regional governments recorded a surplus. The government’s first surplus in a year came in January, at 63.7 billion reais ($11.38 billion), the highest since January 2022.
That month, the debt-to-GDP ratio dropped to 75.3%, the lowest in a year. Brazil’s heavy interest burden continues to weigh on public finances. The central bank attributed the February rise in gross debt mainly to interest payments.
Since September, policymakers have raised interest rates by 375 basis points to 14.25%, aiming to control inflation above the official 3% target. High rates increase debt servicing costs, making fiscal management more challenging.
President Luiz Inacio Lula da Silva’s administration aims for a zero primary deficit in 2025, allowing a margin up to 0.25% of GDP. However, with much of the early surplus due to delayed payments, the sustainability of fiscal gains remains uncertain.
The government faces a fiscal tightrope: it must balance spending needs, debt reduction, and inflation control while managing the timing of large, unavoidable expenses.
Brazil’s headline surplus in early 2025 signals resilience, but the underlying story shows ongoing fiscal risks. The numbers reflect tactical moves and temporary factors, not a structural turnaround.
Investors and businesses should view the figures with caution, as the real test will come when postponed obligations come due and interest costs persist.
More: Brazil news in English, every day from The Rio Times.
This article was produced by The Rio Times’ automated AI newsroom. Editorial responsibility: Matthias Camenzind, Publisher and Editor-in-Chief. The Rio Times also runs Ask Rio Times, which answers from 100,000+ of our own articles, the daily Latin America Power Map, and prediction-market odds on elections and markets.. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Brazil runoff, Sunday, October 25: Brazil runoff start time and results schedule. Latest: Brazil runoff polls, Flávio 51%, Lula 49%.