Brazil’s Bank Cleanup Hits 13 Liquidations After the Master Collapse
Brazil · Banking & Regulation
Key Facts
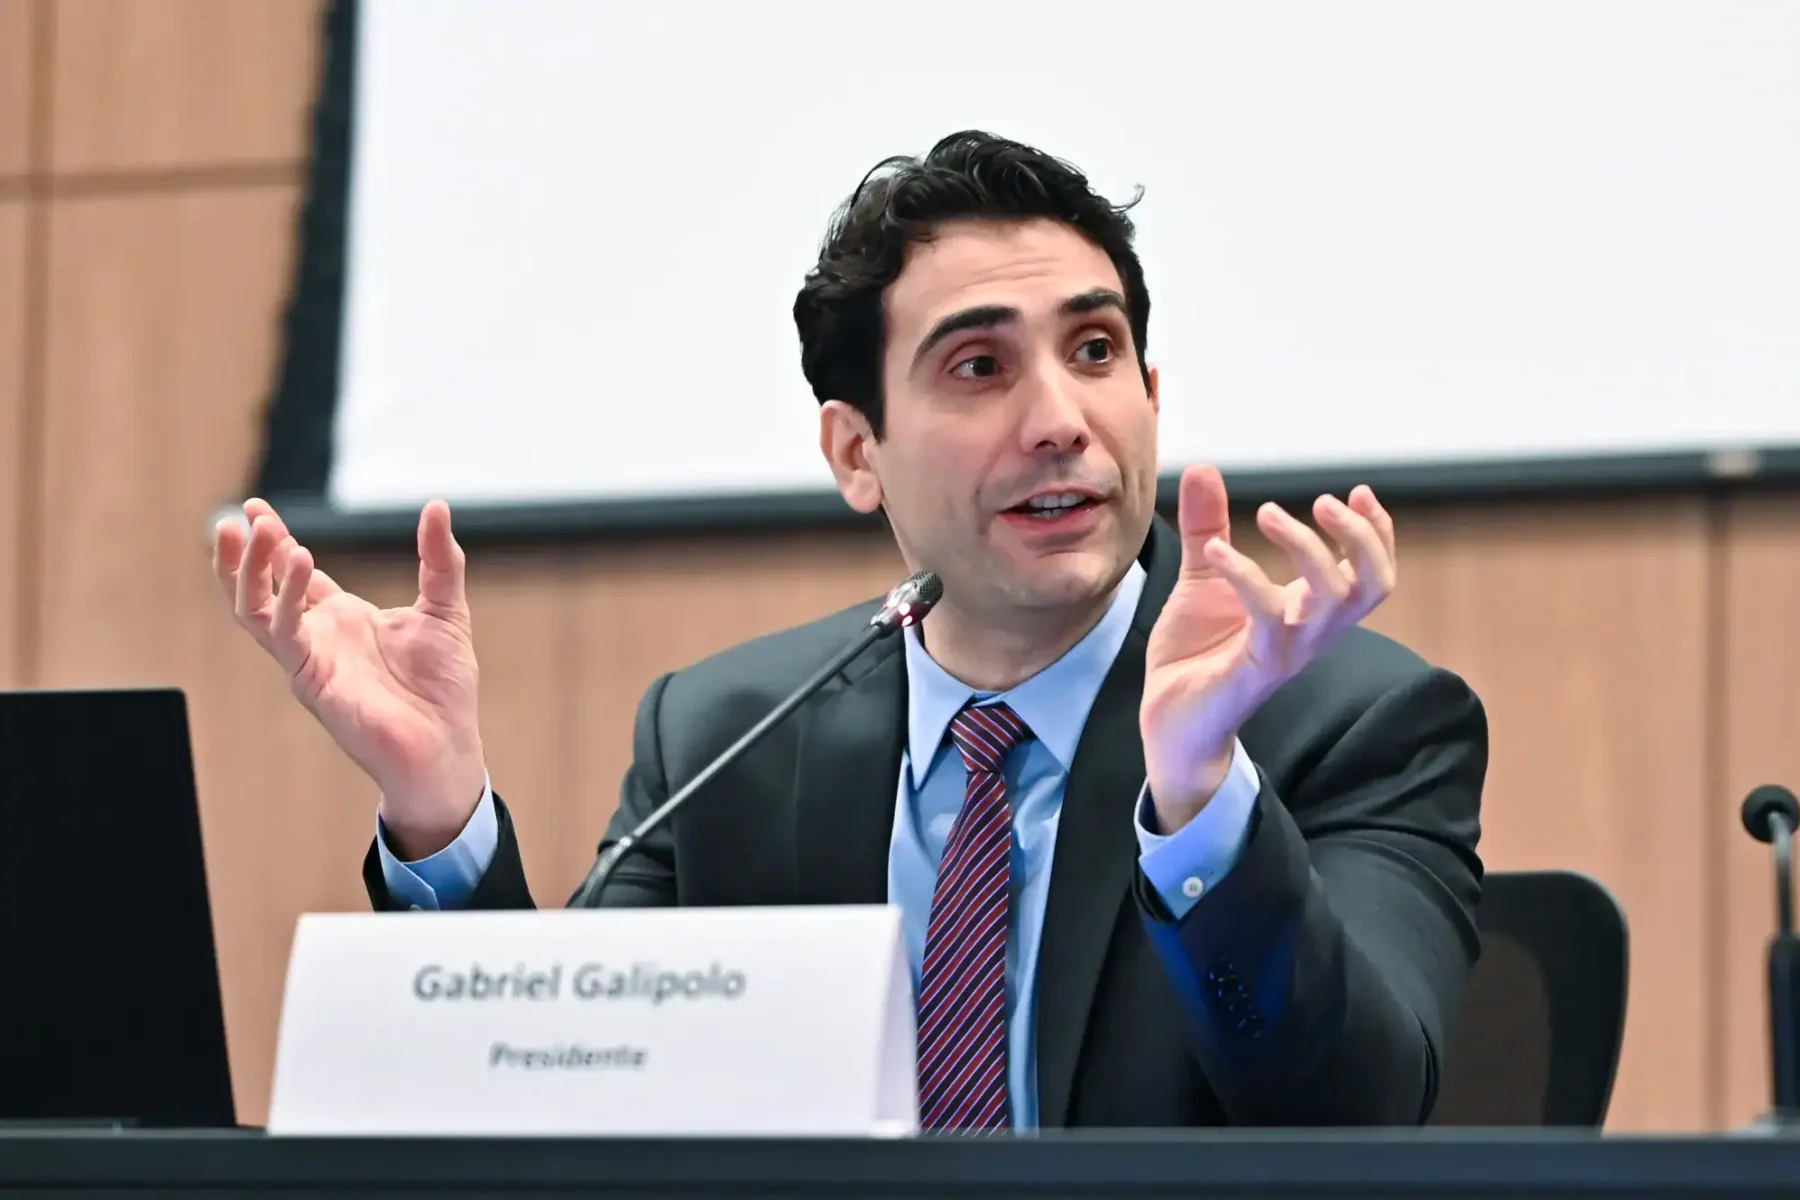
—13 banks liquidated since 2025. Central bank president Gabriel Galipolo told the Senate on May 19 that Brazil’s regulator has wound down 13 financial institutions since 2025, a record run.
—The problem was the asset side, not the deposits. Galipolo said the Master issue was not its liabilities but how the captured money was used, funneled into low-quality, opaque assets.
—Master was a “third-division” bank. He stressed it posed no systemic risk, holding under 0.5% of the banking system’s total equity, but said the misuse of funds was alarming.
—The resolution law dates to 1975. Galipolo warned the legal framework for liquidating banks is half a century old, even as digital banks, fintechs and cooperatives multiply.
—The regulator is stretched thin. The bank has lost roughly 1,200 to 1,300 staff over a decade and faces about 100 retirements in supervision this year alone.
—Liquidators are running short. So many institutions have been wound down that the central bank is now struggling to find enough qualified liquidators to manage them.
Six months after the Banco Master collapse, the question facing Brazil’s Senate is no longer who is to blame, but whether the machinery built to catch the next failure is fit for purpose. Gabriel Galipolo’s answer, delivered under hours of questioning, was uncomfortable: the regulator is doing more bank funerals than ever, with fewer people and a rulebook written in 1975.
What did Brazil’s central bank tell the Senate?
The Rio Times, the Latin American financial news outlet, reports that Brazil central bank president Gabriel Galipolo told the Senate’s economic affairs committee on May 19 that the regulator has liquidated 13 financial institutions since 2025, a record pace. The hearing, repeatedly delayed and politically charged, centered on the central bank’s handling of the Banco Master failure ordered last November.
Senators pressed him on whether the regulator missed warning signs at Master, which grew rapidly on the back of deposit-insurance-backed funding. Galipolo defended the central bank’s response as swift, while conceding it faces real structural, technological and staffing limits in policing a fast-growing financial system.
Why does Galipolo say the deposits were not the problem?
His central point was that the danger lay on the asset side of the balance sheet. The concern, he said, was that money raised from investors was being steered into low-quality assets, opaque operations and structures that were hard to verify. As he put it, what alarmed people was not the liabilities but what was being done with the cash.
The regulator’s core worry, he explained, is a mismatch between deposit-insurance-guaranteed liabilities and the assets a bank actually buys. Master had drawn billions by offering above-market yields on instruments covered by the guarantee fund, then parked much of the proceeds in illiquid holdings such as court-ordered government debt and stakes in troubled companies.
How big a risk was Banco Master?
By Galipolo’s account, small in systemic terms. He described Master as a “third-division” institution, classified in the lower regulatory tiers and holding less than 0.5% of the banking system’s total equity. On that measure, its collapse posed no threat to the stability of Brazil’s large banks.
The catch is that a small bank inflicted an outsized cost. The failure, together with affiliates, drained tens of billions of reais from the deposit-insurance fund and hit well over a million customers, showing how digital distribution can turn a minor lender into a system-scale liability. Galipolo was careful to say he was not minimizing the losses, only the systemic reach.
Why is the regulator under strain?
Two reasons, both structural. The legal framework the central bank uses to resolve and liquidate banks dates to 1975, written for a financial system that bears little resemblance to today’s mix of digital banks, fintechs, finance companies and cooperatives. Galipolo argued the rulebook is simply out of step with the institutions it must police.
The second is capacity. The regulator has shed roughly 1,200 to 1,300 staff over the past decade and expects about 100 more retirements in supervision this year, even as the number of liquidations climbs. Galipolo said the bank is now struggling to find enough qualified liquidators and pressed for investment in technology and artificial intelligence, warning that without more people and resources it may have to focus only on the highest-risk institutions.
What should investors and analysts watch next?
- Resolution-law reform: any move to replace the 1975 framework would be the most consequential structural change to Brazilian bank supervision in decades.
- Central-bank autonomy bill: the long-stalled proposal to give the regulator control over its own staffing, technology and budget gains urgency from Galipolo’s warnings.
- The two suspended officials: the case of two former central bank staff linked to Master remains a live integrity question for the institution.
- Deposit-insurance reform: tighter rules on how banks use guarantee-backed funding are the direct regulatory legacy of the Master case.
- Supervisory triage: if staffing is not reinforced, the regulator may concentrate on systemically important banks, leaving smaller players less closely watched.
More: Brazil news in English, every day from The Rio Times.
How many banks has Brazil’s central bank liquidated?
Brazil central bank president Gabriel Galipolo told the Senate on May 19 that the regulator has liquidated 13 financial institutions since 2025, a record pace led by the Banco Master collapse. The volume is now so high that the bank is struggling to find enough qualified liquidators.
What was the real problem at Banco Master?
According to Galipolo, the problem was not Master’s deposits but how the money was used. The bank funneled funds raised through high-yield, guarantee-backed products into low-quality, illiquid and opaque assets, creating a dangerous mismatch with its insured liabilities.
Did Banco Master threaten Brazil’s financial system?
No. Galipolo described it as a “third-division” bank holding under 0.5% of the banking system’s equity, posing no systemic risk to large lenders. But its failure still drained tens of billions of reais from the deposit-insurance fund, showing how a small bank can inflict outsized cost.
Why is Brazil’s bank-resolution law a concern?
The framework the central bank uses to liquidate banks dates to 1975, long before digital banks, fintechs and cooperatives existed. Galipolo argued it is out of step with the modern financial system and leaves the regulator with outdated tools to manage failures.
Why is the central bank short-staffed?
The regulator has lost roughly 1,200 to 1,300 employees over a decade and expects about 100 more supervision retirements this year. Galipolo warned that without more staff and investment in technology, the bank may have to focus only on the highest-risk institutions.
Connected Coverage
The scale of the damage is set out in our reporting that Banco Master left a record hole in Brazil’s deposit fund. Galipolo’s earlier account is covered in our piece on how he defended the Master liquidation and cleared his predecessor before the Senate inquiry. The full chronology runs through our Banco Master scandal timeline.
Reported by Sofia Gabriela Martinez for The Rio Times — Latin American financial news. Filed May 20, 2026 — 09:30 BRT.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief